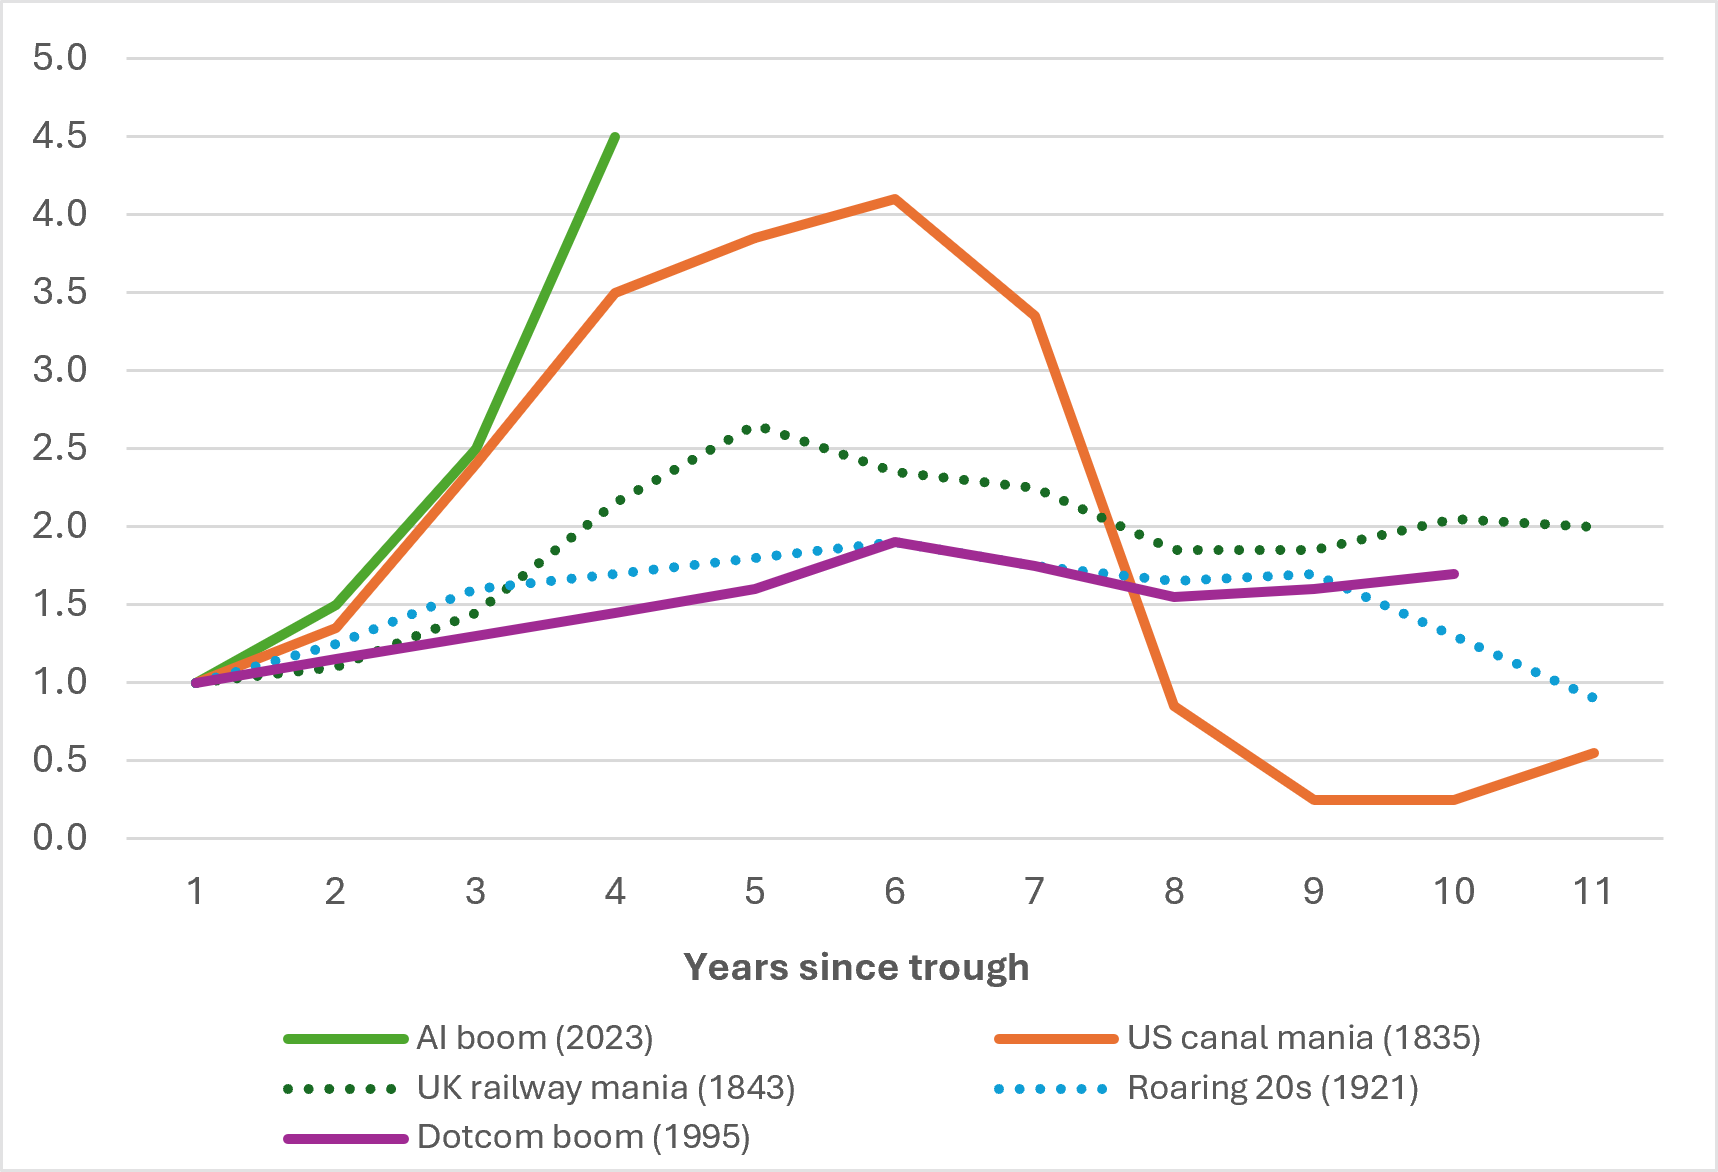
With its capital expenditure cycle in full swing, AI investment in fixed assets is up ~4.5x in three years. Outside of war times, this growth in fixed assets has no precedent, easily eclipsing the US canal mania of 1835 and sits well above last century’s dotcom boom (Chart 1).
Chart 1. AI build-out is eclipsing previous investment booms (Index, pre-boom trough = 1)
Source: ASR, Jul 2026.
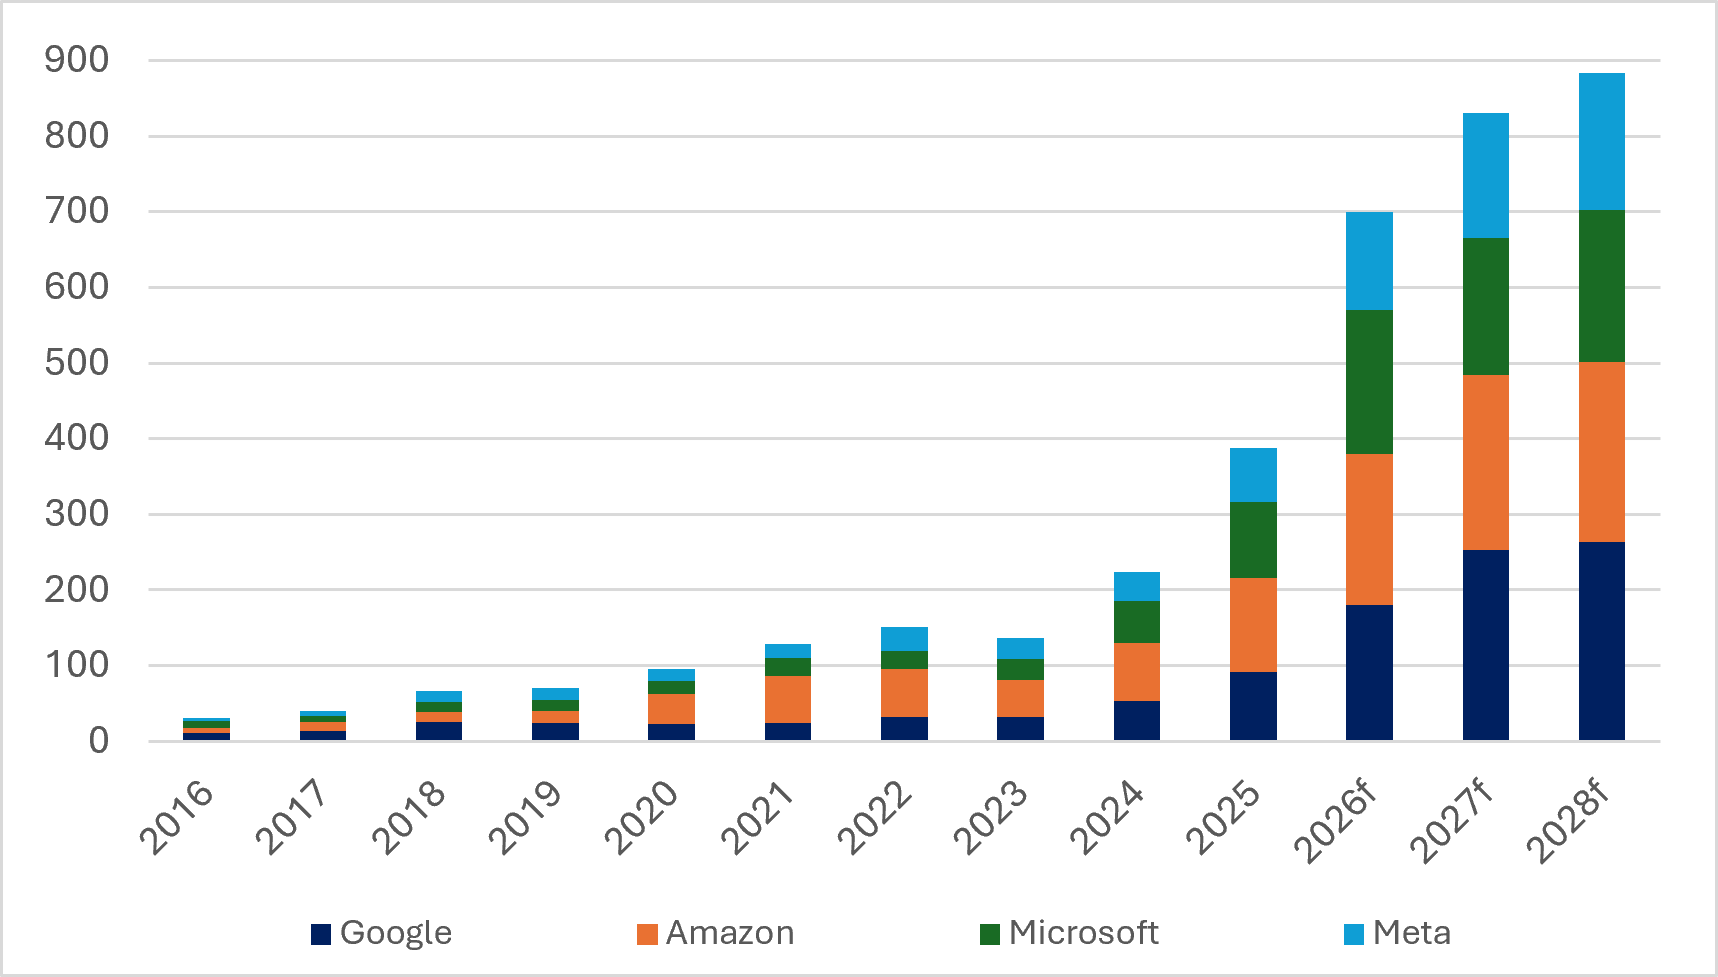
Among the hyperscalers (Google/Amazon/Microsoft/Meta), annual capital expenditures are expected to continue rising to an estimated $US900 billion in 2028 (Chart 2). If you include related investments from the likes of OpenAI, Oracle, SpaceX, Anthropic etc., estimated AI capital expenditures easily exceed $US1 trillion p.a.
Chart 2. Full steam ahead for hyperscaler capex (actuals and forecasts ($USbn))
Source: YCM, Bloomberg, Jul 2026.
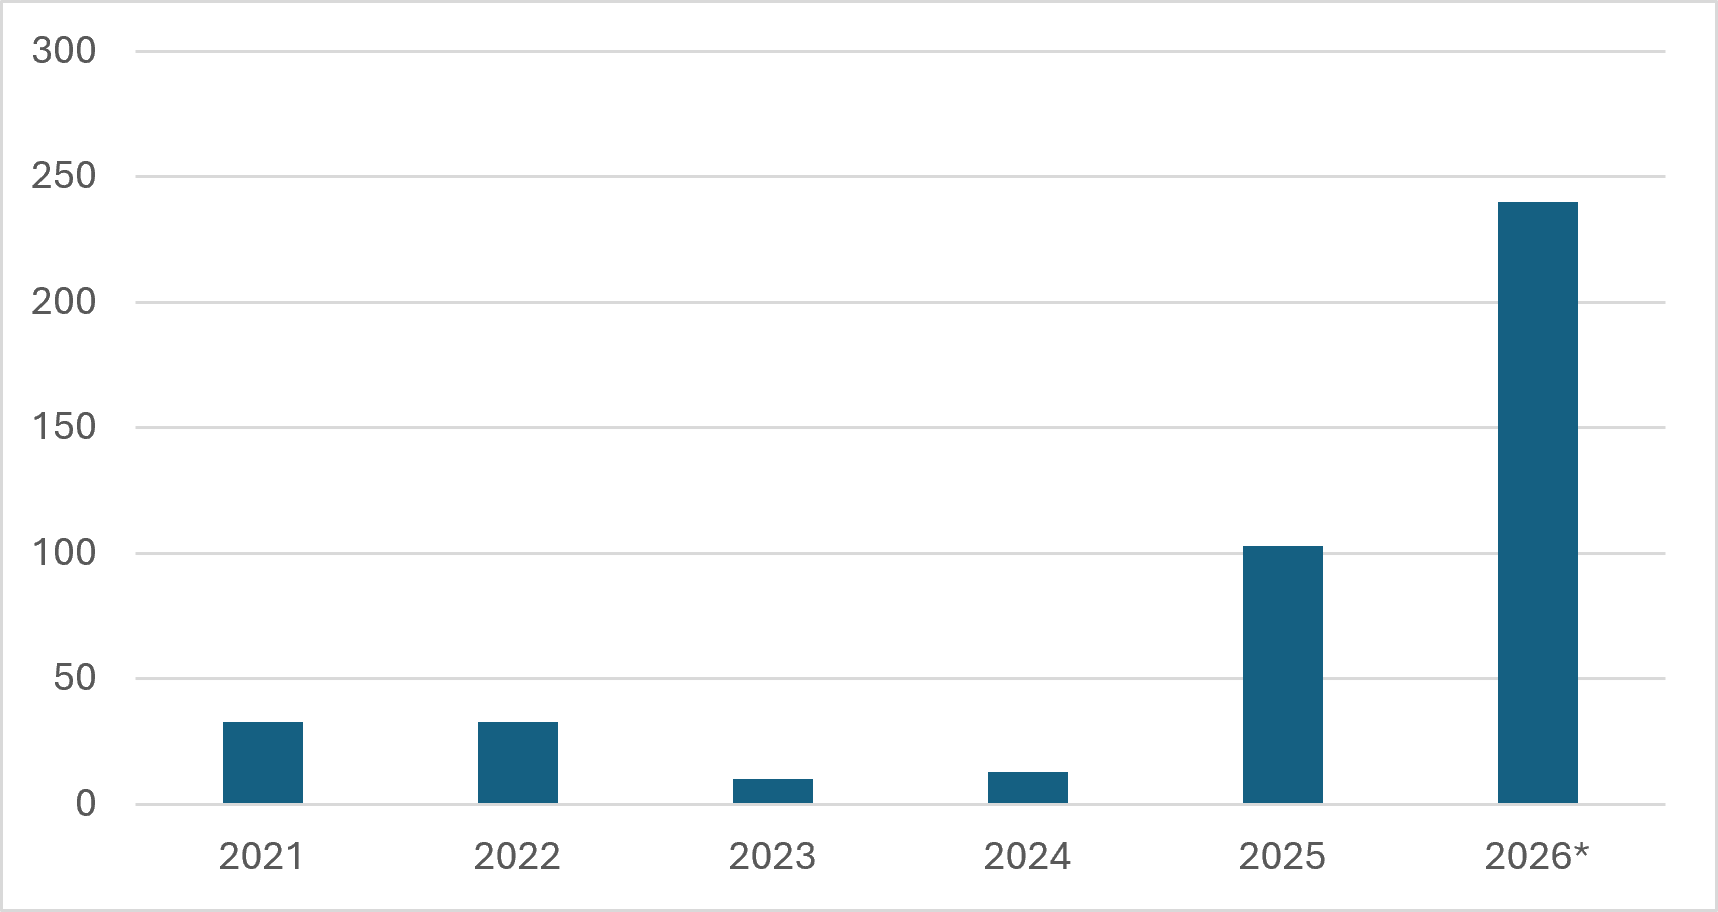
With recurring cashflows totally insufficient, capital expenditures are now being increasingly funded with debt. Up to July 9th of this year, investment grade (IG) bond issuance from Google, Amazon, Meta, Nvidia, Oracle and SpaceX was ~$US240bn, comfortably more than double the total for 2025 and still with ~six months left in the year (Chart 3).
Chart 3. Debt funding now increasingly part of the AI funding plan (AI-related IG Bond Issuance ($USbn))
Source: YCM, Dealogic, 9 Jul 2026.
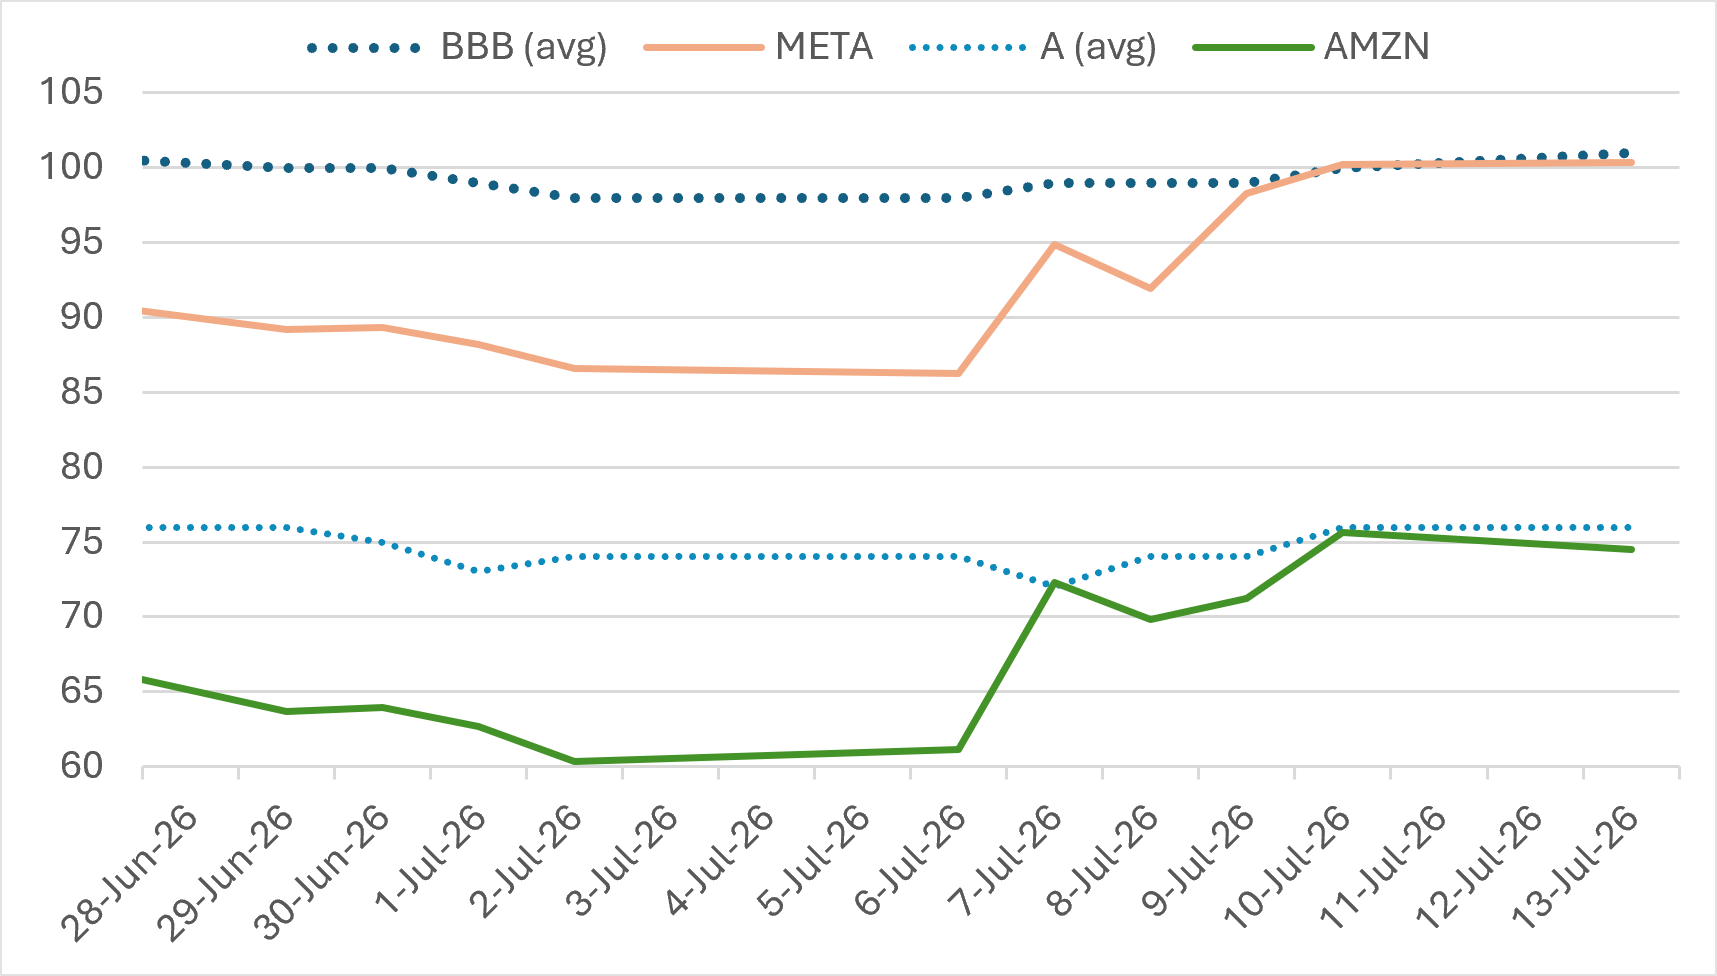
The significant increase in bond issuance, primarily in the US market, is already creating indigestion, leading to hyperscaler spread underperformance. Albeit still officially rated in the double A rating bands, Meta and Amazon are respectively pricing like US triple B and single A rated corporates (Chart 4).
Chart 4. AA rated Hyperscaler 2036 bonds now pricing like single A and triple B credits (2036 $US bonds - credit spreads vs. averages, bps)
Source: YCM, Bloomberg, Jul 2026.
With additional debt funding required and the US IG market already saturated, blockbuster AI issuance is unquestionably coming to a bond market near you. However, the sheer scale of debt required will result in global benchmark pricing across all markets including Australia. Thus, if Meta is pricing as a triple B corporate in the US, the same will apply across all major markets (EUR, $A, GBP and CAD etc.).
To date, AI bond issuance in Australia has been confined to data centre developers NextDC (NXT) and CDC Data Centres (CDC). In the 1H26, both entities issued subordinated bonds/notes while CDC is currently marketing new senior $A bonds. While AI spread widening is not currently impacting $A bond markets, in our view it’s only a matter of time before our market reflects global benchmarking.
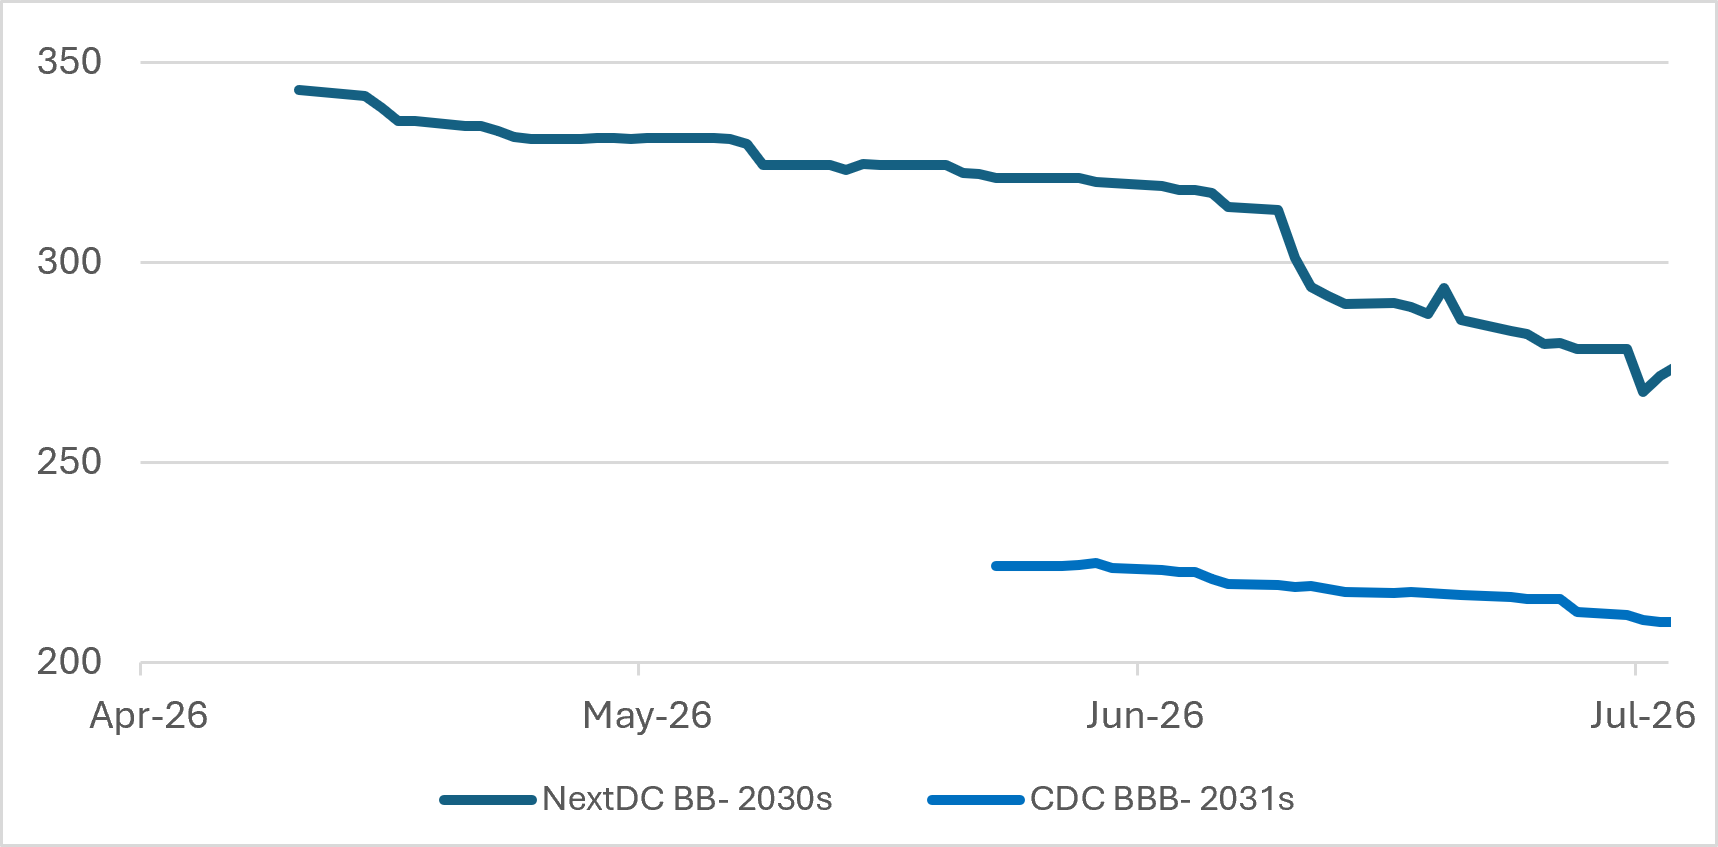
Having not invested in sub-investment grade NXT subordinated notes at issue due to insufficient return for the risk, these securities now look extremely expensive at an even narrower ~275bps credit margin. By contrast, IG rated CDC has not rallied as much, offering more value protection from the AI-related spread widening to come (Chart 5).
Chart 5. Australian data centre bond spreads holding up for now (NXT and CDC subordinated bonds – credit spreads (bps))
Source: YCM, Bloomberg, Jul 2026.
Judging by the latest US bank earnings results, the AI boom is driving revenue growth across equity and debt capital markets. Eager to participate in this growth, domestic banks are champing at the bit to attract more AI issuance into $A markets. Hyperscalers have never issued bonds in Australia, with first-time issuers normally required to conduct a domestic roadshow to execute successfully. We hear there is reluctance to commit the time required for a successful debut deal in Australia.
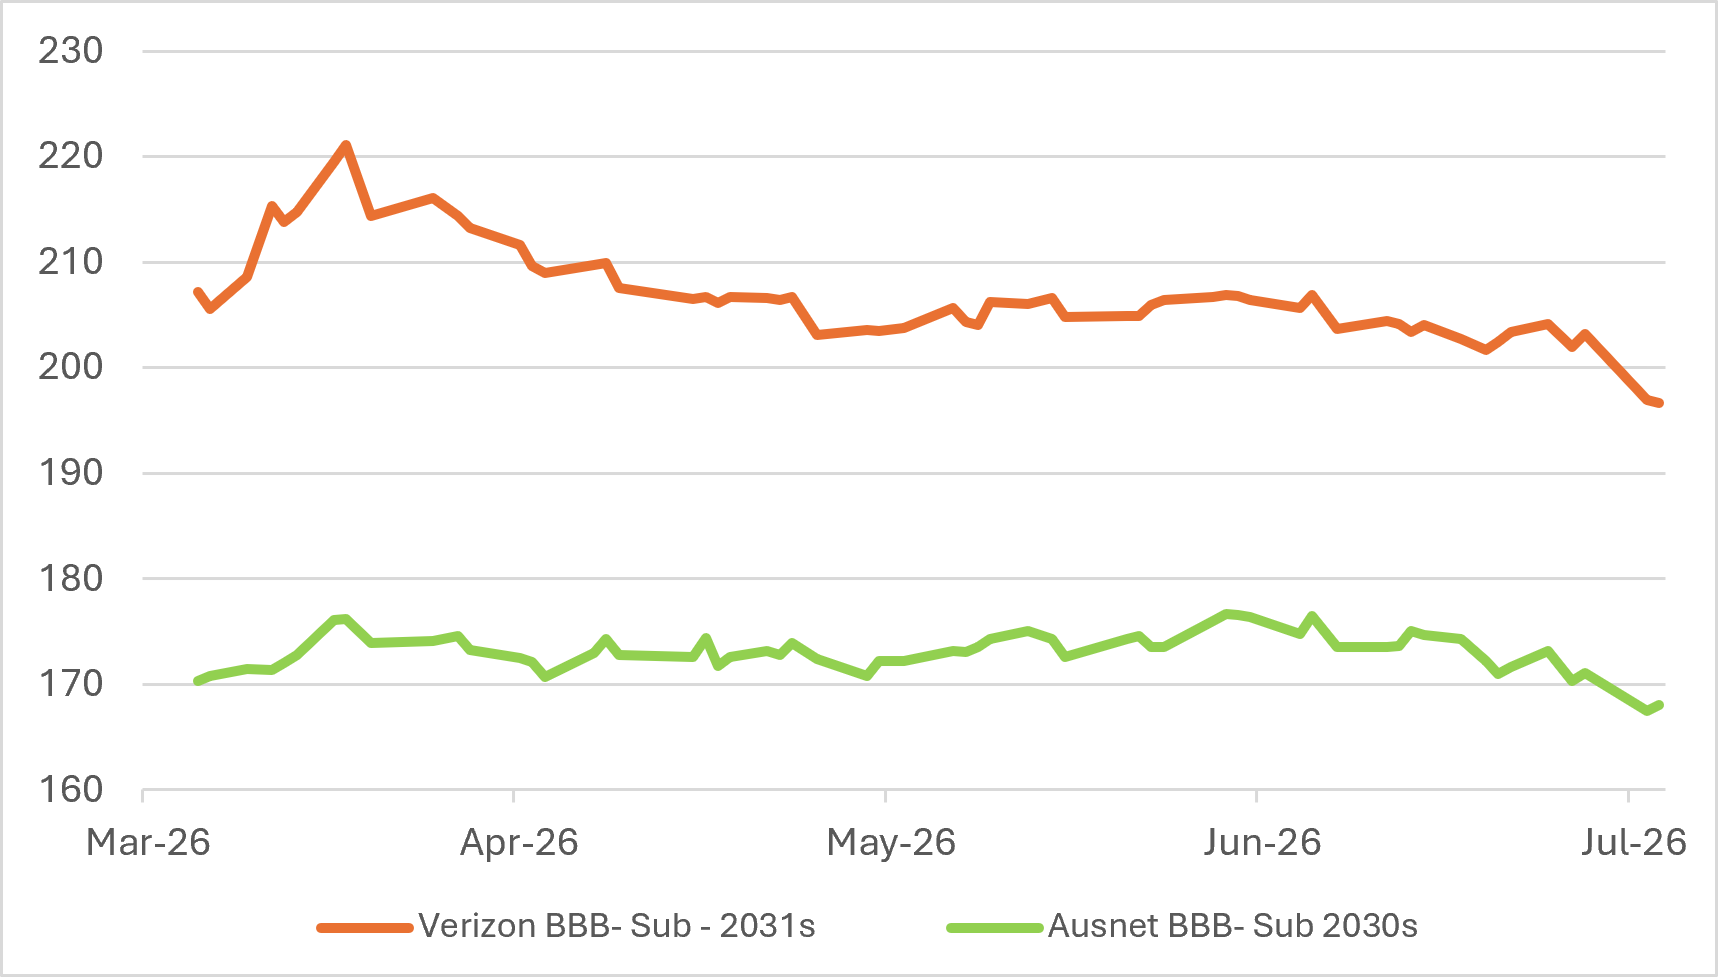
Like Verizon (VZ), who issued $A BBB- rated subordinated bonds in March 2026, there seems to be a preference for same day deal announcement and execution among the hyperscalers. Having not issued in Australia for some time, the VZ method resulted in poor deal execution, wider pricing and weak secondary market performance: the 2031 VZ subordinated bonds were issued ~40bps wider of similar rated Ausnet 2030s and have traded substantially wider, with most domestic investors not participating (Chart 6).
Chart 6: Verizon’s bonds flawed deal execution results in underperformance (Verizon and Ausnet Subordinated Bonds - Credit Spreads (bps))
Source: YCM/Bloomberg – July 2026.
Either the hyperscalers will be happy to pay a significant spread premium for the privilege of accessing the required $A volume in a ~12-hour window or they will alternatively commit to market convention for debut issuers. We expect to find out soon enough.
Given the gargantuan sums involved, it is inevitable that the $A market will see more AI-related issuance with hyperscalers playing a more prominent role. Consistent with global benchmarking, we also expect spread widening to be associated with increased AI issuance. Finally, we remain convinced this period of AI investment will follow a similar path to that of the European telcos of the early 2000s, with average hyperscaler sector credit ratings in coming years migrating lower from double A to triple B. Across our funds, we will be ensuring any investment in AI bonds offers sufficient spread premia to compensate for lower future credit quality.
Overall, expected AI volatility and higher outright yields will create opportunities for active managers to generate additional attractive and defensive income. The actively managed Yarra Enhanced and Higher Income Funds are ideally placed - generating income in the range of 6.5-7.5% p.a. from highly diversified IG quality portfolios.
Phil Strano is Head of Australian Credit Research at Yarra Capital Management, a sponsor of Firstlinks. This article contains general financial information only. It has been prepared without taking into account your personal objectives, financial situation or particular needs.
For more articles and papers from Yarra Capital, please click here.