Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 220

Bond demand is dumb, dumber and dumbest

One of the classic signs that the strong credit cycle is nearing its end is that borrowers that should not be getting financed are not only raising money, but doing so on terms that seem crazy. I have recently written about the silly things happening in global high yield debt, Chinese debt and the global attitude to sovereign debt. Continuing this theme are recent examples of emerging market sovereign debt in Greece, Argentina and Iraq. Each of these should not have been funded, but the desperation for yield saw all three achieve crazy funding levels. Here are the details to show how investors have gone mad.

Argentina

In June, Argentina sold $2.75 billion of US dollar denominated 100-year bonds at a yield of 7.92%. This was a mere 5.18% yield pick-up over 30-year US Treasuries. Argentina has a long history of defaulting on its government debt, including four defaults in the last 35 years. The 2001 default took 15 years of negotiation and litigation to resolve, with most bondholders losing their shirts and a few who bought late and fought hard achieving extraordinary returns.

The current outlook shows that not much has changed for Argentina. Inflation is running at over 20% and the government is aiming to cut the deficit this year to 4.2% of GDP, hoping to stimulate the economy out of recession. Investors are banking on the recent change in government to increase foreign investment and see sound economic management implemented. The need to reduce politically popular subsidies will be a major hurdle to that plan. S&P’s rating of “B” and Moody’s at “B3” reflect the country’s weak credit profile. Taking all of this into account, Argentina is unlikely to get through a decade without defaulting, let alone 100 years.

Greece

In July, Greece sold €3 billion of five-year bonds at 4.63%, a 4.78% yield pick-up relative to five-year German government bonds. Investors have particularly short memories on Greece’s sovereign debt, with the 2012 default seeing bondholders take losses of around 75%. The 2014 issue of five-year bonds traded as low as 56% of face value, a horrible ride for those who bought into it. The constant negotiations for further bailouts always come with the threat that Greece will not make further concessions and this time the Europeans and the IMF might have had enough.

Greece’s position remains precarious as debt to GDP currently stands at 179%. The economy has been stagnant for years as its government continues to resist the structural reforms proposed by the IMF and Europeans. Some are optimistic as Greece recorded a primary surplus (before interest expenses) in 2016. Unlike the buyers of the recent bond issue, S&P (B-) and Moody’s (Caa2), do not see a good prospect of Greece paying back its creditors.

Iraq

In early August, Iraq sold $1 billion of five-year bonds at 6.75%, a 4.93% premium to US Treasuries. Iraq faces three major medium-term issues: the ongoing war, export revenues reliant on oil prices and dependence upon military and financial support from the US government. Each of these is out of its control. The 2016 deficit at 14% of GDP shows Iraq clearly cannot service its debts without a substantial financial turnaround. By buying the bonds, investors have effectively banked the equity case of the war ending and oil prices improving. The credit ratings from S&P (B-) and Moody’s (Caa1) are a better reflection of Iraq’s economic prospects.

Conclusion

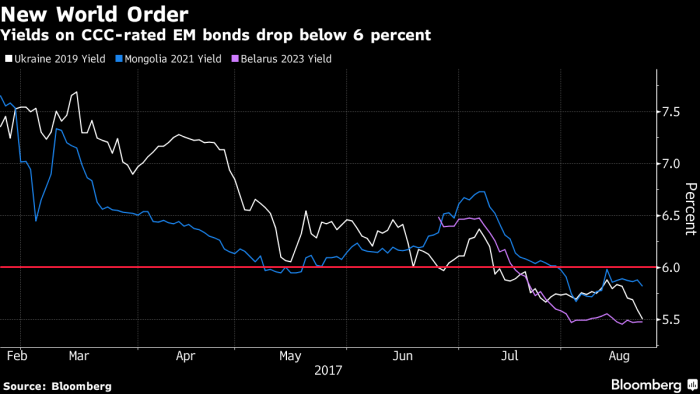
In considering emerging market sovereign debt, investors must consider each country on its own merits. In the examples of Argentina, Greece and Iraq, bond buyers have suspended sceptical analysis. They have banked the equity case, hoping for a substantial change from historical precedents, even though they will not get a share of the upside if the rosy scenario occurs. The examples are not unusual, as shown in the graph below from Bloomberg. Belarus, Mongolia and Ukraine are all CCC-rated but have bonds yielding less than 6%.

Yields on CCC-rated emerging market bonds
sovereign debt

sovereign debt

These examples point to the greater fool theory playing out in many credit markets. We have now reached the point in the credit cycle where further gains seem dependent upon more dumb money arriving and pushing spreads even tighter. Calling the top of any cycle is nearly impossible, but calling out the current higher risk/lower return environment is simply common sense.


Jonathan Rochford is a Portfolio Manager at Narrow Road Capital. This article has been prepared for educational purposes and is not a substitute for tailored financial advice. Narrow Road Capital advises on and invests in a wide range of securities.


  •   21 September 2017
  • 3
  •      
  •   

RELATED ARTICLES

Fear of missing out trumping fear of loss

Hedge funds seizing ships – what next?

Australia’s default: who do you rescue?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.