Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 98

Bubbles and the corruption of risk

I have previously warned that the combination of the demographic avalanche of retiring baby boomers, low interest rates and a disproportionately large amount of their wealth in cash would mean that stocks and property would continue to rise for a while. I call it ‘The Boom We Have to Have.’ But like all booms, this one will also bust.

These conditions, especially low rates forcing a big part of the population into riskier products, corrupt investors’ sense of risk. Rising prices amid a wave of buying reinforces the behaviour of investors and their brokers who believe their thesis is correct.

New listings and credit point to problems

I am not alone in the view that at some point in the next six to eighteen months, there is a real chance that baby boomer retirement plans may sink thanks to their inability to avoid repeating the investment mistakes of their past. Stanley Druckenmiller is an American hedge fund manager, famous for being the lead portfolio manager for George Soros’s Quantum Fund. In 2010, Druckenmiller handed back the billions he had been managing for 30 years through his firm Duquesne Capital. He remains a noted philanthropist, keen golfer and speaker on the global investment and macroeconomic circuit.

Druckenmiller should be heeded. He observed that low rates have skewed peoples’ sense of risk, particularly in two markets – new share listings (IPO’s) and credit. He pointed out that 80% of companies listed in 2014 have “never made a dime”. In 1999, just before the tech crash, that number was 83%.

(As an aside, over the Christmas break, I read You Only Have To Be Right Once: The Unprecedented Rise of the Instant Tech Billionaires. Including Twitter, Facebook, Instagram, the book was a who’s who of the world’s biggest tech companies and the backgrounds to their stunning rises. But I couldn’t help noticing that all the references to billions had little or nothing to do with profits or in some cases even revenues. Some of the businesses discussed, which were sold for billions, not only had no revenue but no revenue model either).

Druckenmiller had another warning on credit markets. Last year, speaking on CNBC, Druckenmiller said, “When I look at credit … corporate credit is growing at a record rate, far faster than it grew in 2007. And S&P pointed out that 70% of debt issued has a B-rating or worse. To put that in perspective, in the ’90s, that number was 31%. Do you remember the hullabaloo in 2007 about covenant-light loans? Companies issued $100 billion of them in 2007, and 38% was B-rated. This year we’re going to $300 billion, up from $260 billion last year and $90 billion a year earlier, and 58% of them were B-rated.”

At the more recent speech, Druckenmiller also observed, “There are some really weird things going on in the credit market … but there are already early signs starting to emerge. And if I had a message out here, I know you’re frustrated about zero rates, I know that it’s so tempting to go ahead and make investments and it looks good for today, but when this thing ends … I think it could end very badly.”

Why is Druckenmiller so worried? It’s simple. If interest rates rise, many investors in corporate debt will want to exit at the wrong time. Australian investors in bank hybrids and corporate bonds (G8 Education is a recent example of a popular corporate bond issuer) should consider the warning too. And if interest rates don’t rise, but the economy weakens significantly, then some industries will be unable to cover their debt costs. Either way, investors will face problems at some stage.

Low rates support asset prices

Low interest rates are here to stay for a while and that will support asset prices. Eventually however the price of those assets (stocks and property) will be pushed way too high (we think a strong bull market is likely for some part of this year) as people panic buy amid a fear of missing out when their income is eroded from low rates on cash. After that, a large number of investors will, sadly, suffer financially again – from buying too late and paying too much.

There is a way to avoid it. You must be invested in high quality businesses with bright prospects and buy them when they are cheap. We can think of only a handful of stocks that meet this criteria currently. When we cannot find such opportunities, the only safe alternative is cash (even though rates are low) and we are 20-30% invested in cash at the moment.

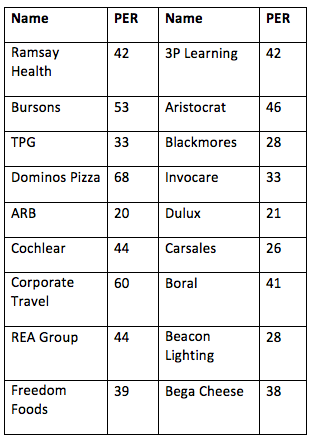
If you are invested in a high-performing fund that is fully invested in stocks like REA Group (P/E ratio 44 times), Dominos Pizza (68 times), or many of the expensive stocks below, consider switching at least some of your retirement nest egg to a larger cash weighting. The cash won’t make your investment 100% immune to a declining market but it will allow additional purchases at cheaper prices, which offers the opportunity to significantly reduce the time to recovery. In Table 1, PER is Price to Earnings ratio.

Table 1. Expensive stocks? You be the judge…
RM Picture1 270215

RM Picture1 270215

Of course if interest rates stay at zero, the party could last a while yet, but as I have warned previously, be sure to be dancing close to the door in case you need to leave. Druckenmiller refers to a “phony asset bubble”, with a bunch of investors ploughing money into assets which will “pop”. Then we’ll see how many people are still enjoying the party.


Roger Montgomery is the founder and Chief Investment Officer of Montgomery Investment Management.


  •   26 February 2015
  • 6
  •      
  •   
6 Comments
Peter
March 02, 2015

Investing is a bit like you and a friend trying to out running a lion. You don't need to be faster than the lion, just your friend. The Oz market has had a stellar run, but just about every indicator is touching the red line. The case for a correction has been viable for years (it just hasn't happened). What I'm seeing now is an irrational exuberance. House prices can go beyond affordability, bank stocks can rise higher than potential returns, mining bust is inconsequential, moribund government doesn't matter.
There's really nothing driving the stock market up these days other than a fervent hope that we want/need it to. Historically, most major crashes were preceded by a period of welcome boom.

Mark
March 02, 2015

Unemployment highest in over 10 years and will get worse, terms of trade to get worse, low inflation, interest rates heading to Nil, budget deficit to continue, lowest income growth, no mining boom this time round, Sydney now 9 times debt to income. It's not guessing, it's analysing data over a period and knowing that this will only end badly, tell me, how does Australia grow over the next ten years?? My advice would be to pay down as much debt as possible, although I still have time.

Gelert of Birrong
March 02, 2015

Don't be too harsh on all boomers. Many started with nothing; and are the first generation to be caring for their parents while still looking after older kids at home, and grandchildren. Far from stealing from anyone, they are sandwiched in a situation where they are providing care for three generations. And, the younger generations will inherit what wealth is left. Boomers are not living the luxury of your straw man example. They are great examples of hard working, caring people. The sort of people that any country depends upon.

Frank O'Connor
March 02, 2015

Mmmm ... we're all pretty much along for the ride at the moment, with no indication that anyone has a plan (or, more importantly the capability) to head the various Bubbles off at the pass.
The Reserve is pretty much locked into lower and lower interest rates to sustain housing and share values and avoid a Crash, the banks are hoping that this protects their mortgages and loan portfolios, corporate Australia seeks remedies (lower wages, less government controls, reduction of costs etc) that suit them temporarily but will bring on the financial blood bath that drowns the Golden Goose, the government continues to promote policies that encourage the Bubble (negative gearing, corporate tax initiatives, letting go the controls, cutting back expenditures, and hence demand, whilst ignoring a host of revenue issues, middle class welfare etc etc), and everyone else is out there pretty looking out for their own short term interests without any comprehension of how fragile the foundations are.
Gotta love this country. :)

Adrian
January 18, 2018

"at some point in the next six to eighteen months, there is a real chance that baby boomer retirement plans may sink thanks to their inability to avoid repeating the investment mistakes of their past"

Feb 2015 plus 18 months = Aug 2016

Sorry if it sounds smart in hindsight, but I question what exactly are the mistakes of the past. Maybe trying to time the market is a bigger mistake for most people instead of sticking to a consistent plan and an asset allocation that suits one's situation and personality.

Brendon
January 18, 2018

"Markets can remain irrational for longer than you can remain solvent"

Large allocation to cash over this period has missed quite a run, but it can't continue forever.

Dancing close to the door remains a valid concept :)


Leave a Comment:

RELATED ARTICLES

This is mean (-reverting that is)

Where to put your money these days

Higher yields are creating opportunities in global bonds

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.