Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 378

Claiming a tax deduction for super contributions

One of the few positive, simplification measures that came with the 2017 major changes to superannuation was the ability for all fund members to claim a tax deduction for contributions made to super. Prior to 1 July 2017, only substantially self-employed individuals were eligible to claim a tax deduction.

Salaried employees may have been (and may still be) eligible to participate in salary-sacrifice arrangements with their employer, which has the same effect as claiming a tax deduction. However, many employers don’t offer salary-sacrifice. Also, some employers only contribute deducted amounts quarterly when superannuation guarantee contributions are made, even though deductions from the member’s salary occurs weekly or fortnightly.

The change has resulted in hundreds of thousands of additional members being eligible to claim a tax deduction and although the rules for claiming have not changed, there are aspects of the rules that are commonly misunderstood.

Notice of intent to claim

Claiming a tax deduction for personal contributions requires a member to submit a valid notice of intent to claim a tax deduction to the trustee of the fund. The notice is often known as a section 290-170 notice after the section of the tax law that covers deductible contributions.

Conditions for claiming a tax deduction for personal contributions include:

  • the individual is still a member of the super fund at the time of lodging the notice
  • the relevant contributions are still retained within the fund (such as before partial/full withdrawal or rollover from the fund)
  • the trustee has not begun to pay a pension based in whole or part of these contributions
  • the member has not supplied a super splitting notice to the fund in respect of the same financial year
  • no part of the contribution/s are covered by an earlier notice
  • the member has received a notice of acknowledgement from the trustee of the superannuation fund.

The notice of intent to claim a tax deduction must be submitted on or before the first of the following dates:

  • the date the client submitted their tax return
  • 30 June of the following financial year after the client made the contributions.

Impact of partial withdrawals

Where a member makes a partial withdrawal during the year, part of the withdrawal is defined as including contributions made before the withdrawal. This means that unless a notice of intent to claim a tax deduction is received prior to a withdrawal, the member will not be able to claim a tax deduction for the whole personal contributions made that year.

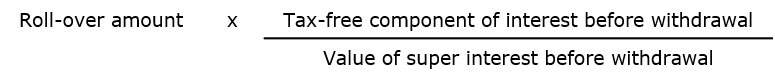
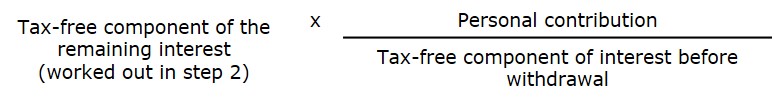
A valid deduction notice will be limited to a proportion of the tax-free component of the superannuation interest that remains after the roll over or withdrawal. The proportion is the value of the relevant contribution divided by the tax-free component of the superannuation interest immediately before the partial withdrawal. The amount that can be claimed is calculated according to the following formula:

Step 1 – Calculate the tax-free amount of the withdrawal
Step 2 – Calculate the tax-free component of the remaining interest
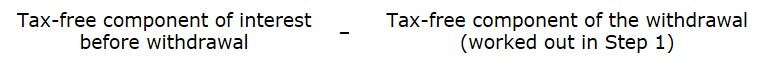
Step 3 – Calculate the remaining amount of the personal contribution
The law allows members to lodge a notice of intent to claim a tax deduction at any time during the year however some funds have specific product rules that only allow notices to be lodged as an annual process. Accordingly, it is best to check with the fund before rolling over.

Regular rollovers to fund insurance premiums are an example of a situation where members are not fully aware of the impact on their ability to claim a tax deduction.

Case study

Brian contributes $2,000 per month to his super fund and intends to claim $24,000 as a tax deduction. On 31 December he rolled over $3,000 to pay for his insurance premiums in an insurance-only super fund. Brian does not provide his super fund with a notice of intent to claim a tax deduction before the rollover.

As at 31 December, Brian’s super balance is $50,000 and the tax-free component in his super fund (so far) is $12,000 (the contributions for which a notice of intent to claim a tax deduction has not been received by the fund). The portion of the $12,000 that remains in the fund is calculated as follows:

Step 1 – Calculate the tax-free amount of the withdrawal

Roll-over amount x (Tax-free component of interest before withdrawal / Value of super interest before withdrawal)

$3,000 x ($12,000 / $50,00) = $720

Step 2 – Calculate the tax-free component of the remaining interest

Tax-free component of interest before withdrawal - Tax-free component of the withdrawal (from Step 1)

$12,000 - $720 = $11,280

Step 3 – Calculate the remaining amount of the personal contribution

Tax-free component of the remaining interest (from step 2) x (Personal contribution / Tax-free component of interest before withdrawal)

$11,280 x ($12,000 / $12,000) = $11,280

Brian makes a further $12,000 of contributions before the next 30 June. Brian then lodges a notice with the intention to claim a deduction for the $24,000 contribution. The notice is not valid as the super only holds $11,280 of the first half of the year’s personal contribution. Brian can only lodge a valid deduction notice for an amount up to $23,280.

If Brian made a further rollover on 30 June to fund insurance premiums the process would be repeated and the amount available to claim reduced further.

Brian could claim the whole $24,000 by lodging a notice of intent to claim a tax deduction before the rollover occurs.

Conclusion

Understanding the rules in relation to the eligibility requirements for claiming a tax deduction for personal contributions will enable members to maximise their tax deductions.


Julie Steed is Senior Technical Services Manager a Australian Executor Trustees. This article is in the nature of general information and does not consider the circumstances of any individual.


  •   7 October 2020
  • 11
  •      
  •   
11 Comments
robert
October 07, 2020

Is the payment of a fund expense such as auditors or accounting fees or advice fees considered a withdrawal in this situation?

Julie Steed
October 07, 2020

Hi Robert,
No, the payment of fund expenses are not considered a withdrawal here, only rollovers.
Regards
Julie

Neil
October 07, 2020

In the course of processing the valid notice of intent to claim a deduction, the fund will deduct 15% contribution tax. If the notice is lodged immediately after making the contribution then only 85% of the contribution is invested. If the notice of intent is lodged just before the tax return is lodged the full amount of the contribution is invested until the notice is processed and tax deducted. In normal times that should give a better result but in the time of Covid, maybe not.

Julie Steed
October 07, 2020

Hi Neil,
You are correct, some funds will deduct an allowance for tax at that point but many (most retail funds) will only calculate and deduct the tax at the end of the year. Likewise, some funds deduct tax on super guarantee and salary sacrifice contributions at entry, rather than when the tax is payable.
This is a great example of how different fund practices result in different outcomes for members. Sadly, these types of differences aren't captured in many comparison tools.
Regards
Julie

Neil
October 07, 2020

Thanks Julie. Yes, my public fund also immediately deducts the contribution tax on the employer and salary sacrifice contributions. That will usually involve a significant disadvantage for the account holder over deduction of the contribution tax at year end. I’ll take up the issue with my fund. If retail funds can deduct tax at year end then I’m surprised some industry and public funds don’t.

Carl
October 07, 2020

Thanks Julie - excellent article.
For clarity, is a contribution made within the year & subsequent to a roll-over / withdraw date, Notifiable / deductable in full amount from a regulatory perspective?
(Appreciate CC limit & fund rules / conditions also then applicable).

Julie Steed
October 07, 2020

Hi Carl,
If a partial rollover is processed before any contributions are made (that a member wishes to claim a tax deduction for) there is no reduction to the amount that can be claimed.
Regards
Julie

Chris
October 08, 2020

Hi Julie,
Thank you for an interesting article.

My employer does, as you describe, 'only contribute deducted amounts quarterly when superannuation guarantee contributions are made, even though deductions from the member’s salary occurs weekly or fortnightly'.

In this case you I be better offer considering making the contributions myself and then claiming a tax deduction for personal contributions ?
Regards
Chris

Julie Steed
October 08, 2020

Hi Chris,
This is something to consider. The good thing about salary sacrifice is that the contributions get made (even if a bit late). Sometimes people have the best intentions of making contributions at the end of the year but then forget. Other people have found that setting up a regular direct debit or Bpay directly with the fund assist.
Regards
Julie

Mark Jenson
October 08, 2020

It should be noted that some funds have a cut off date for the processing of “notice of intention to claim a tax deduction “. In my case the fund would not accept the form if lodged less than 4 business days before the EOFY.
I just scrapped in.

Zoe
October 15, 2020

Hi Julie,
Can I confirm I have understood the terminology correctly. Is rollover the likes of TPD insurances that in my case are deducted monthly from my super a/c?
As a sole trader I have been paying my concessional contribution in one lump sum June 1 & immediately claiming the tax concession. I had considered making more regular payments over the FY but if I do so I need to claim each amount immediately if concessional value to be claimed is not to have insurance deductions. If we reach the $25k concessional cap & allow insurance deductions to occur prior to lodging our intention to claim, does this mean we can pay more than the $25k cap into our super each year to account for insurance fees & then claim the full $25k cap at the time of lodging our tax return?
Many thanks,
Zoe


Leave a Comment:

RELATED ARTICLES

A guide to excess non-concessional super contributions

Valuable super contribution changes are now law

Super changes, the Budget and 2021 versus 2022

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.