Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 474

If I get kicked out of the value investors’ club, so be it

Plenty of people want to know if we still call ourselves value investors, or is there a style change in our funds? It's a question we received after our recent roadshow, when we disclosed that about one-third of our Forager Australian Shares Fund (ASX:FOR) is currently invested in tech stocks.

Value can include strong growth prospects

Value investing has always, to me, meant investing in shares of a company at a significant discount to the underlying value of the business. That has often incorporated businesses with strong growth prospects, as long as those growth prospects aren’t reflected in the share price.

Wind back five years to our 2017 Performance Report, many of the best performers that year were growing businesses and tech companies.
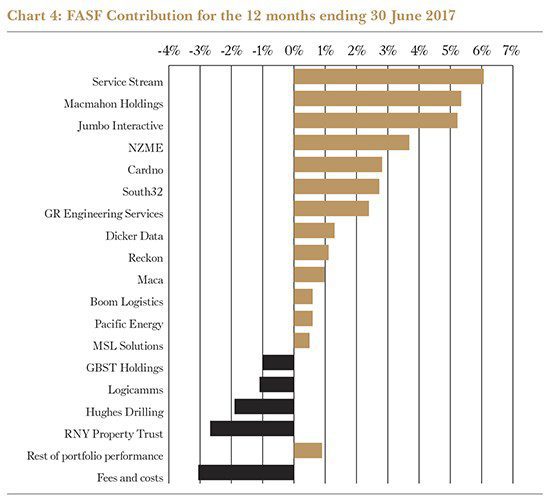
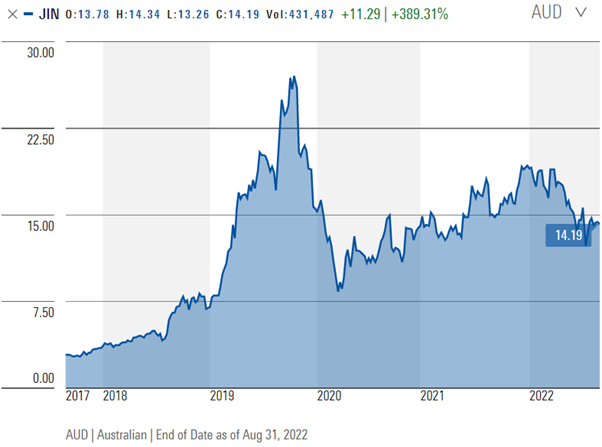
Jumbo Interactive, GBST (since delisted) and Reckon were all tech stocks. Jumbo and GBST were barely profitable at the time we bought them. Dicker Data was a growth stock (albeit one trading on a low earnings multiple at acquisition).

Jumbo Interactive
 

 Dicker Data
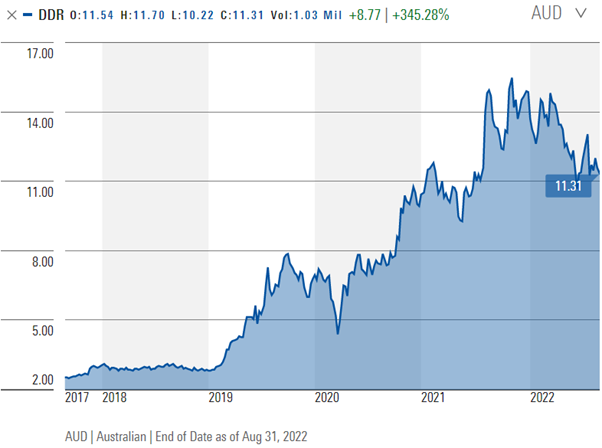
Source: Morningstar.com

Most of our historically-successful investments were businesses that grew, even if they weren’t priced to grow at the time of our first investment.

Most famous value investors are perfectly capable of valuing growing businesses. One of Warren Buffett’s most successful investments, the Coca-Cola Company, was one of the 20th century’s greatest growth stocks. Seth Klarman’s publicly-disclosed holdings currently include Amazon and semi-conductor company Qorvo.

Hanging on to the value moniker

The challenge is that the understanding of what constitutes a value investor has changed with the rise and rise of index funds. By categorising the market as either ‘value’, for stocks with high dividend yields and low price-to-earnings ratios, or ‘growth’ for those with the opposite characteristics, index providers were able to offer factor funds. 

But I’m not yet ready to give up the moniker. Value investors have appreciated growing companies since before the index fund existed, and the distinction between us and the rest is still important.

Quality and growth are not criteria for our portfolios, simply inputs into our valuations. We want to own quality when it is unloved or underappreciated, not quality for quality's sake. We currently have investments in Seven West Media, mining services and Qantas, and neither would meet a ‘quality’ filter. We simply invest on estimates of future cash returns to shareholders. That is equally true of RPMGlobal, where the earnings are going to grow.

More now, because the time is right

There are two good reasons we have ‘drifted’ towards a higher allocation to growing companies over the past few years. 

First, look back at that 2017 list and you will also see Boom Logistics, Hughes Drilling and RNY Property Trust, a cluster of asset-heavy businesses that we invested in at substantial discounts to the ‘value’ of their tangible assets. These did not work out well and were subsequently joined by the likes of Thorn Group and iSelect, similarly ‘cheap’ stocks that never generated the profits we expected. Every business has a price. But the gap between the right price for a shrinking business and a growing one is a chasm. We learned that more than once.

Second, investors should expect us to ‘drift’ a lot. We have a particularly high weighting to tech stocks at the moment but they are all established businesses with predictable and growing revenue streams.

Investors didn’t give a hoot about profits 18 months ago and tech stocks traded on revenue multiples. Today, the share prices have been absolutely hammered and all anyone cares about is profitability.

Change of accounting standards is an opportunity

Yes, some of them are currently reporting losses. But that is largely a function of significant investment in attracting new customers, rather than any reflection on the profitability of the existing customers. Twenty years ago, the accounting standards allowed companies to capitalise customer acquisition costs and spread the expense over the life of the expected revenue stream. That, predictably, led to a proliferation of aggressive and unrealistic assumptions and overstated profitability.

Today’s accounting standards, where all of the customer acquisition costs get expensed upfront, leads to understatement of economic reality.

For the value investor, therein lies the opportunity. These businesses are no more difficult to value than most, and our estimates have not changed meaningfully over the past 18 months. Yet some share prices are 70% lower, taking them from premiums to our valuation estimates to significant discounts. We buy them when they are cheap.

If those share prices rise a lot, and everyone else becomes optimistic, you should expect us to be moving on to the next sector that is out of favour.

If that gets us kicked out of the value investors’ club, then so be it.


Steve Johnson is CIO at Forager Funds, a Sydney-based boutique fund manager. This article provides general information to help you understand our investment approach. It does not consider your personal circumstances and may not be suitable for you.


  •   7 September 2022
  • 4
  •      
  •   
4 Comments
CC
September 07, 2022

Performance is what really matters, not style. 

Claude Walker
September 07, 2022

This article seems like it in part a response to my article asking if Forager Funds has changed investment style: https://arichlife.com.au/has-foragers-australian-fund-changed-investment-style/

The distinction I was making was between loss making tech stocks (now) and profitable, or at least turnaround stocks (or asset plays), previously. The Forager website says the style is “Perhaps best described as a hybrid of the Graham and Buffett styles, we view both asset backing and earnings power as useful valuation tools, depending on the type of business we are investing in.”

I think it is fair enough to ask the question when quite a few of the top holdings are barely profitable, or indeed loss making, these days. That past big 'tech stock' winner (congrats) Jumbo International had been paying dividends since 2008, and Dicker Data about the same.

If we define value investing in the way that you have defined it, then every single fund on the market is a value fund, including ARKK and Frazis Capital Partners. So you can have the mantle moniker forever, even if your style does change.

Nothing wrong with change, anyway; sorry if the question touched a nerve.

Sam
September 09, 2022

It seems like a fair question, what is conspicuous in it's absence is "Here's how I was wrong buying Thorn before or profitless tech now and how I'll avoid theses mistakes in future". Managers must learn from mistakes. 

Claude Walker
May 04, 2023

This article originally seemed to respond to my article asking "Has Forager's Australian Fund Changed Investment Style?" so I thought it worth noting a recent development that pertains to this question.

I note Lonsec has updated their view on Forager's other (International) Fund and "has some concerns around philosophical and style drift which will be acutely monitored in future reviews."

Interesting that mental gymnastics of defining all investing as value investing then claiming that you are still a value investor because you are still an investor does not seemed to have convinced Lonsec.

What is weird to me is that anyone finds it convincing, but I guess that is what makes a market.


Leave a Comment:

RELATED ARTICLES

Is the market’s recession conviction warranted?

Invest in Australian value stocks before it is too late

Global search for short-term losers and long-term winners

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The investing rule that explains the next market crash

What if investment success depends less on picking the right assets and more on understanding the decisions of other investors? A principle borrowed from game theory offers a different perspective on markets.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.