This is an edited transcript of comments from Andrew Swan, Man GLG’s Head of Asia ex-Japan Equities, at a media briefing hosted by Firstlinks’ sponsor GSFM.
What's striking about Asia at the moment is that for most of my career, it has been very synchronous with global growth. And in the last 12 to 24 months, we've seen very asynchronous growth in Asia, to the rest of the world and also within Asia itself. I think a lot of that has to do with the lingering effects of COVID and how that affected the world differently … and the inflation pressure that emerged in the West which didn't emerge in Asia.
Bright outlooks for South and North Asia
[There are] three buckets in Asia at the moment. There are domestic demand economies, which are most of Southeast Asia or South Asia, including India, Indonesia, and the Philippines, and Thailand. The real story here is: growth is good. More domestic demand driven rates are fairly high in these markets because of what the Fed has been up to. And, really looking for a green light from the Fed to cut rates. So, what is already a good environment here can actually get better, and the growth cycle can elongate as rates come down.
The second bucket is more the global demand North Asian economies. And while demand is slowing down, there is this thing called AI that will supercharge the tech cycle, and Asia is a big beneficiary of that, particularly within semiconductors. But even further downstream, that's what's going to be interesting. This year, most of the AI euphoria has been in upstream, in semiconductors and the cloud. And now we're just on the cusp of seeing how that stimulates demand downstream.
So, you're going to see a lot more AI related functions in your phones and your iPads, in your laptops and in your PCs. And when you see this step changing technology, you tend to see a lot of innovation that drives demand after what has been a fairly weak demand environment for consumer electronic products. I think you're on the verge of a new cycle.
The outlook for those economies and companies in the region which are exposed to the tech cycle, I think looks very good.
China’s economic model is dead
Then there's the big bogey in the room being China. What has surprised us is how quickly China has moved into a deflationary environment and even idiosyncratic opportunities within the economy have been swamped by this deflationary force that's emerging.
Now, my view on China - it's at the end of the cycle. It's been led by investment and debt, and it has to change. The problem with change and structural changes - normally there's pain involved. And normally, policymakers will do nothing until they have to. I guess we're getting closer to that point where they're going to have to do something because the pressure on the domestic economy and the equity market is going to force their hand at some point.
What has been surprising is the resilience of the currency in the scheme of what's going on in deflationary environment. I do think the China has accumulated a lot of FX (foreign exchange) reserves offshore in the banking sector, not so much with the PBOC (People's Bank of China). But certainly the state-owned banks have held a lot of FX reserves, and if you look at FX reserves in the PBOC, they haven't really changed despite these deflationary forces. I think that's because these hidden reserves are being used to support the economy, but that only lasts so long. China is in this situation where they really need the currency to depreciate to make the economy more competitive.
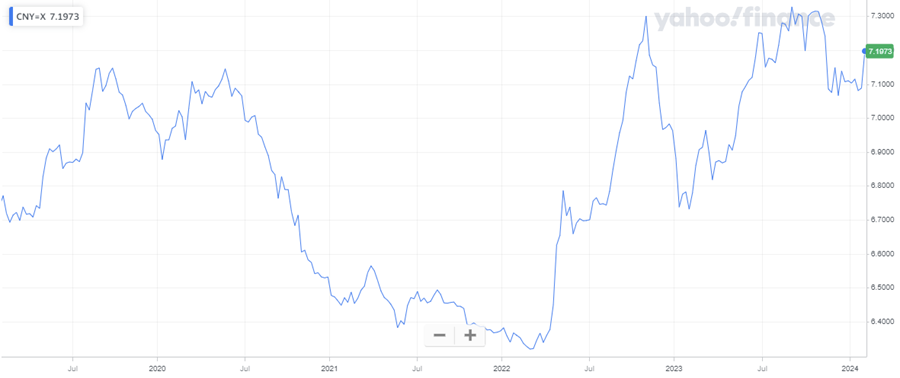
Source: Yahoo Finance
They’re running very high real interest rates, which supports the economy the currency in the short term but puts pressure on the economy over the medium term.
China has two main options
There are two options here for China, which are structural in nature:
- a one-off devaluation of the currency; a large devaluation of the currency. Now, certainly the policymakers are not suggesting anything like that. But the reality is, if you're going to devalue your currency, you do it from a position of strength, not weakness. There is very much school of thought that China may do a one-off devaluation to get ahead of these problems.
- the second option for China around structural reform is the savings rate is extremely high and consumption is very low. How do you break that? I think a lot of this has to do with the social safety net, which is broken. The hukou system needs to change. The comments coming out of Xi Jinping in recent weeks and months have started to include social welfare reform, which needs to be watched very closely. Anything that can give people confidence - that there's something there for a rainy day - will lead them to consume more. And that's really what China needs.
Overall, the market is getting a little bit too bearish about China. There are definitely some challenges, but there is still opportunity. When you get these periods of dramatic sell off, that's when policymakers normally are forced to respond. And we haven't seen it yet but we're getting closer.
The final point is the fiscal deficit in China contracted a lot last year because they [policymakers] felt the economy would recover quite strongly. There's definitely scope on the fiscal front for China to do more this year in the face of weakness.
Andrew Swan is Head of Asia ex-Japan Equities at Man GLG, a fund manager partner of GSFM, a Firstlinks sponsor. The information included in this article is provided for informational purposes only.
For more articles and papers from GSFM and partners, click here.