Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 492

Markets appear too optimistic on central bank pivot

A new year is an opportunity both to reflect and to look forward, but I will not attempt to forecast particular outcomes. The last year was a stark reminder of how foolish predictions can look 12 months later, so I'll cover some more general themes.

What went wrong in 2022?

The main culprit was inflation and more importantly how persistent inflation proved to be after central banks initially believed that it would be transitory. This forced the banks to shift to the most aggressive tightening cycle since the 1980s in an attempt to restore price stability.

The picture was further complicated by the war in Ukraine and ongoing supply chain blockages thanks to China's zero-Covid policy.

In response, the Fed increased the Fed Funds rate by 4.25% over the year and was still warning that it had more to do as recently as its last meeting in December, with officials looking to raise rates further this year to between 5% and 5.5%.

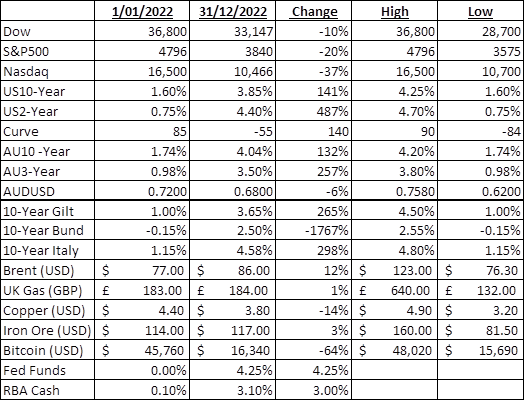
To highlight the impact this all had on markets, below is a table showing the markets I tend to watch the closest and the gains or losses that they experienced from the start of 2022 to the end of the year.

These are my numbers so might be a little different from the ‘official’ record, but they are still consistent with the underlying trend.
The outlook for this year

What does the next 12 months have the potential to look like?

The burning question at this stage is will the US economy enter into a recession and how will the Fed respond.

In a recent Wall Street Journal survey, two-thirds of economists at the 23 major financial institutions that directly deal with the Fed predicted a US recession this year with an increase in the unemployment rate to above 5% from its current historical low of 3.7%.

What became clear towards the end of last year was that the market was starting to bet that the Fed was being too negative in its outlook and that it was close to the end of its tightening cycle. It may be in a position to invoke the much anticipated ‘pivot’ by mid-year with the Fed cutting rates towards the end of 2023, which is in contrast with the Fed’s mantra of 'higher for longer'. The very tight jobs market in the US has been a major obstacle in the Fed’s fight against inflation.

The reality, and it is a similar story locally, is that consumers are still happy to keep spending despite the rapid rate increases and until there is a change to this behaviour it is going to stymie central bank’s ability to win the fight.

Record Christmas spending further underlines the challenge and is adding to inflationary pressures, compounded by governments that continue to undermine central banks by adding fiscal stimulus in the form of subsidies as well as talking up wages.

As has been a theme of mine for a while now, consumer behaviour is not changed by warnings alone. This could well be a generational phenomenon with many never having lived through the brunt of a recession and the shock this can have on asset prices and rising unemployment. They know only a prosperous period of economic growth which ironically has been perpetuated by central bank policy that is undermining their battle now.

As such, if the dramatic rate increase from last year does start to bite hard in the first half of this year, then we are close to the top of this cycle. However, if that level of pain is insufficient to alter behaviour, then rates must go higher.

Given Australia's exposure to the risk of ‘mortgage stress’ and the much-talked about cliff we are approaching as massive number of fixed mortgages switch to higher floating rates, maybe we are closer to the top than other economies.

However, this has been known for a while and mortgage holders should already have started to adjust their spending to reflect this. But maybe not.

Central banks warnings continue

In summary, for the year ahead, central banks and the market are in somewhat of a disagreement as to how high and for how long interest rates will remain elevated. Central banks continue to warn that they are 'not for turning' until they are confident that price stability has been restored. The outlook is further clouded by the war in Ukraine as well as the Chinese doing a 180-degree flip and letting Covid rip and this will have an impact on global growth.

Therefore, I am not confident we are close to a bottom in US equities although bonds should have a better year as markets sweat on the Fed pivot.


Tim Larkworthy is a Director - Fixed Income Sales at Fixed Income Solutions. The views expressed herein are the personal views of the author and in no way reflect the views of the BGC Group. Individuals should make investment decisions based on a comprehensive understanding of their own financial position and in consultation with their own financial advisors. No liability whatsoever shall accrue to the author or the BGC Group as a result of individuals or entities making investment decisions based wholly or partly on this material.


  •   18 January 2023
  • 2
  •      
  •   

RELATED ARTICLES

AI economic scenarios: revolutionary growth, or recessionary bubble?

Time to announce the X-factor for 2024

Podcast: US recession risks and a simple wealth-creating strategy

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.