Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 158

Regulator demands robos understand clients

Quick and simple digital advice makes investing easy, but do the long-term consequences outweigh the short-term benefits? A new report by US market regulator, the Financial Industry Regulatory Authority (FINRA), draws attention to this question by sharing the digital investment advice practices employed across the securities industry. It's a reminder of the obligations that come with robo advice and the standards FINRA expects to underpin a financial advice service.

FINRA CEO Richard Katchum questions the adequacy of robo risk tolerance practices when he contrasts them with personal advice delivered by a human advisor:

"The same requirements are in place — the same expectations that you understand your customer, both from the standpoint of what their risk appetites are, and also that you have asked enough questions to really understand their financial situation and that they can accept risk and the risk of loss."

Furthermore, advisors need to be able to explain both to clients and the regulator how their tools and products work. There is no defence in the argument that ‘I'm just following instructions from head office.’ Black-box solutions are not acceptable.

Undergoing a complete investor profile

Many robo advisors do not develop an appropriate investor profile of clients. One of the most fundamental aspects of delivering suitable advice is to ascertain the level of risk that a client is willing to take. This is referenced as ‘risk willingness’ in the FINRA report and is commonly referred to as risk tolerance. The regulator questions whether it's possible to accurately measure the amount of risk that an investor is willing to take by asking a small number of risk tolerance questions – in some cases just one.

There are no lower standards expected for robo advice compared to human advice. FINRA’s ultimate concern is investor protection, and the importance of accurately assessing risk tolerance cannot be ignored. When investors take more risk than they are comfortable with, they are more likely to bail-out of the market when the going gets tough and then wait too long to get back in. This pattern of buy high and sell low makes it difficult for investors to achieve their financial goals. Furthermore, over-exposed investors suffer adverse behavioural reactions to financial loss such as anxiety, loss of sleep, and relationship problems.

It is common industry practice to treat investment time horizon as a sub-factor of risk tolerance when, in fact, time horizon is an aspect of risk required (the level of risk needed to achieve your goals). Simply put, this requirement is a catalyst for change. Most risk tests used in the market place would be non-compliant according to these principles.

FINRA also makes a distinction between risk tolerance and investors’ capacity for loss, making customer profiling critical because it drives recommendations to customers. The message is clearly aimed at the executives at the top of the enterprise:

“Two other areas of digital investment advice - customer risk tolerance assessment and portfolio analysis - reinforces the need for broker-dealers to establish and implement effective governance and supervision of their digital investment advice tool. Good governance involves understanding if the approach to assessing customer risk tolerance is consistent with the firm’s approach. Firms must apply good practices across all distribution channels, not just robo advice.”

Analysis of seven robo recommendations

FINRA details seven robo advisors' portfolio recommendations for a young worker. Let's call him Michael. Of particular concern is the wide range of 60% to 90% in growth asset recommendations and how they match to his risk tolerance. If growth exposures are greater than what is consistent with risk tolerance, then the likelihood increases that the investor will be disturbed by a market correction. If not satisfied by the advice, clients may sell down growth assets at the wrong time, and in the worst cases, seek legal redress. Dissatisfied clients are a blight to all businesses, more so in financial services in the last few years.

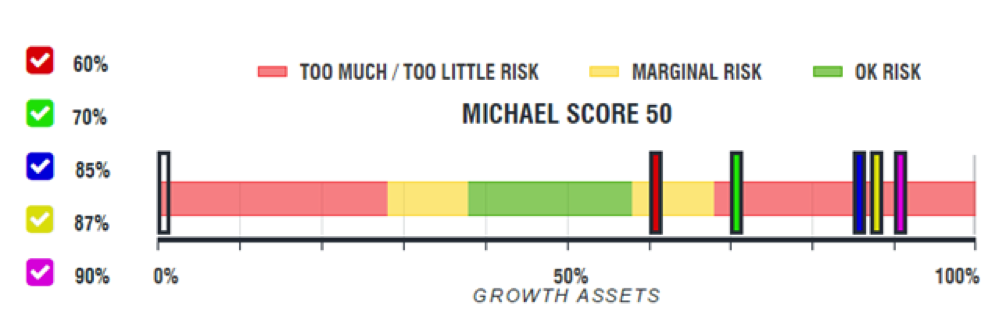
Let's assume that Michael has a FinaMetrica risk tolerance score of 50 (out of 100) and is placed in Risk Group 4. Based on a score of 50, Michael would be comfortable with between 39% to 58% growth asset exposure. Most people in Michael’s Risk Group would typically be discomforted when the value of their entire investment fell by 20%.

If we look at the seven portfolios illustrated in the FINRA report from the standpoint of who would be comfortable based on risk tolerance alone, the riskiest portfolio with a 90% exposure to growth assets matches the risk tolerance score of just the top 5% of the population. This rarefied group generally includes hedge fund managers, bankers, entrepreneurs and high risk tolerant individuals.

When we map the seven recommendations (shown by the vertical bars below) on to Michael comfort zones, none of the portfolios is consistent with Michael’s risk tolerance and all but one are in the 'Too Much Risk' red zone.
To test sensitivity, we look at four broadly diversified portfolios with 60%, 70%, 80% and 90% growth assets. These portfolios were back-tested to 1972 using indices rebalanced once a year. Even the 60% equity-exposed portfolio exceeded the 20% drawdown that investors whose risk score is 50 typically tell us they are comfortable with.
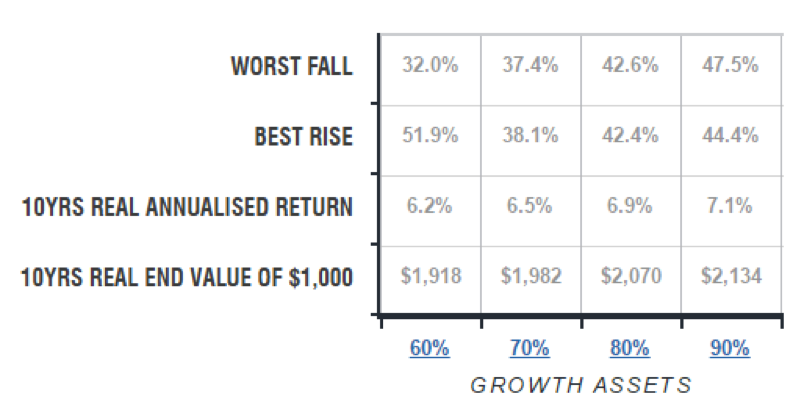
We are regularly reminded that the past is not a precursor of the future in terms of investment performance, so we don’t need to be reminded that unhappy investors are a scourge on our industry's/profession's successful and profitable future. If we don't manage the matching of investments to investors' needs effectively, we can be assured that regulators will continue to do it for us. Risk tolerance is not hard to assess accurately, it just needs a little science and a dash of common sense.


Paul Resnik is Co-Founder and Director of Finametrica, a risk profiling system that guides ‘best-fit’ investment decisions.

The Australian regulator, ASIC, recently completed its consultation feedback for its own policies on robo advice.


  •   2 June 2016
  • 2
  •      
  •   
2 Comments
Ashley
June 02, 2016

Well argued, Paul. It assumes the FINRA case study had a Finametrica score of 50. I wonder what other profiles would have done?

I have a different view on 'risk tolerance. The article perpetuates the flaw that ‘risk tolerance’ is all about ability to stomach temporary falls in portfolio value on the way to the end result (balance at retirement or income stream in retirement). Instead, it should be about the ability to stomach a lower end result - ie permanently lower retirement cash-flow/lifestyle.

The table of numbers at the end also assumes single point outcomes being assured, with the temporary drawdowns (‘worst fall’) being just the occasionally painful path to the assured single point end result. But in the real world it is the end result (retirement balance and retirement cash-flow) that is very rubbery and not assured.

It's a different point of view on what ‘risk’ means.

Ramani
June 02, 2016

Instead of thinking human and robo advisers as totally compartmentalised, let us think of one as less robo and the other as more human. After all, human advisers do not start from first principles but use a range of established tools and templates, which tend to make the analysis routine and automatic - almost robotic. And to the extent robo conclusions are derived from generalised templates that have withstood experience and critical scrutiny, they replicate human interaction and advice.

On the positive side, unless programmed so, robos would not on their own push their own interests. Humans are notoriously prone in this regard as every major planning disaster has shown.

The very human conflicted advice, the shared inability to predict the future and often remember the past and product complexity are what trip investors most. Either alternative must grapple with it.

Ironic that the US regulator FINRA would like robo advisers to be more like humans. Apart from the dreary record of US regulators (which triggers the circumvention genius of lawyers, accountants and advisers), they must beware of getting their wish: robos may descend to the lowest common denominator of conflicted advisers, who excel in building a secure retirement ( just for themselves), if they do not spend their twilight years in prison - all taken care of!


Leave a Comment:

RELATED ARTICLES

The latest costs and strategies in financial advice

Five charts show predicaments facing financial advice

What is robo-advice?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.