Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 410

Rising real yields likely to undermine equity values

In the United States, the economy has recouped nearly all the ground lost during the pandemic, and corporate earnings aren’t far behind. As I wrote in Firstlinks in April, 'A year like few others but what's next?', risk assets have discounted this V-shape recovery but as economic and earnings data evolves from forecast into fact, markets are looking ahead to see what’s next.

I believe what’s next will be a day of reckoning as investors grapple with higher yields. Here’s why.

Every investment opportunity is ultimately weighed against competing possibilities for use of funds. The decision to allocate capital happens only if the investment will clear its hurdle rate. While the height of every investment hurdle is determined by its idiosyncratic risk, real, inflation-adjusted interest rates are the first input into that calculus.

Anchors aweigh

During the 2020 recession, central bankers were determined not to allow lockdowns to morph into a credit crisis. In order to buoy animal spirits, policymakers drove real US Treasury yields deeply into negative territory, as illustrated in Exhibit 1 below.
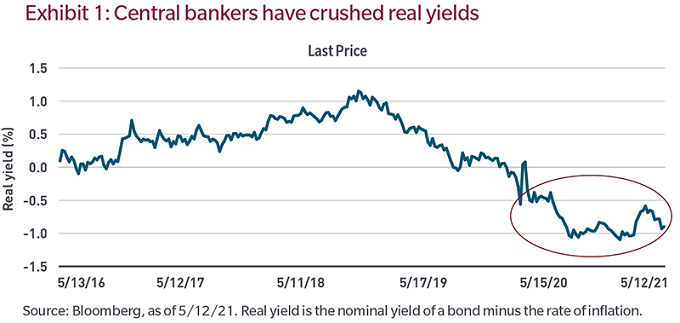
In the years leading up to the pandemic, the real yield on the 10-year US Treasury Note lived in a meagre range below 1%, but at least it was positive and provided investors with some sort of measuring stick.

However, financial theory holds that asset prices can’t go negative. Since capitalism requires a hurdle rate, business school courses don’t teach students how to value a company or a project with negative nominal or real interest rates.

Without an anchor, it’s apparent why risk assets have risen as they have. Exhibit 2 overlays the advances made by the S&P 500 and MSCI World indices from their pandemic lows against the path of U.S. 10-year Treasury real yields into negative territory.
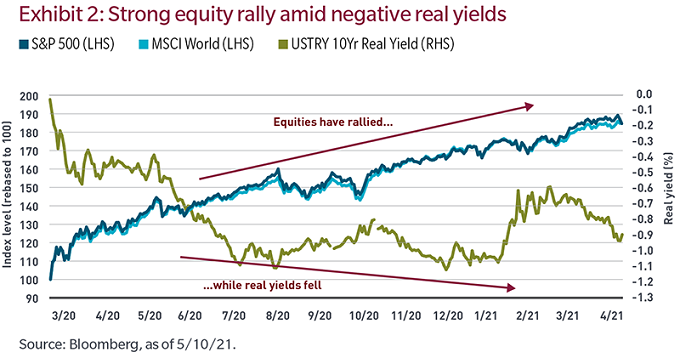
(The Standard & Poor’s 500 Stock Index measures the broad US stock market. The MSCI World Index measures stock markets in the developed world).

While there’s much sell-side research contending that risk assets can absorb inflation and higher rates, there’s an observable inverse correlation in the chart above that I think is causal and not coincidental. Since rates are the first hurdle in the valuation of any asset, higher rates, whether real or nominal, lower the value of that asset.

Negative real yields are unsustainable

As economies continue to reopen and excess savings are spent, inflationary pressures will continue to mount. We’re seeing it in goods such as lumber, semiconductors and automobiles; in services such as airfares, rental cars and vacation rentals; and in hard assets such as commodities and real estate.

Ultimately, we believe these pressures will prove transitory as the secular disinflationary forces of the past decade-plus — elevated debt levels, aging demographics and continued digitalisation, to name three — reassert themselves.

However, we’re confident that negative real rates are unsustainable and will eventually normalise. What we’re less confident about is the timing or the rate at which real yields will rise.

Regime shifts are always clear in hindsight but rarely at the point of inflection, yet markets have a way of sniffing them out. And when they do, we suspect that the relationship displayed in Exhibit 2 will reverse as rising real yields undermine equity valuations. As we go from forecast to fact, we believe market performance and leadership will look materially different than they have in the past several quarters.


Robert M. Almeida is a Global Investment Strategist and Portfolio Manager at MFS Investment Management. This article is for general informational purposes only and should not be considered investment advice or a recommendation to invest in any security or to adopt any investment strategy. Comments, opinions and analysis are rendered as of the date given and may change without notice due to market conditions and other factors. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343), a sponsor of Firstlinks.

For more articles and papers from MFS, please click here.

Unless otherwise indicated, logos and product and service names are trademarks of MFS® and its affiliates and may be registered in certain countries.


  •   2 June 2021
  • 2
  •      
  •   

RELATED ARTICLES

Is there any point in holding cash?

The bank is still a terrible place to put your money

Dividends strong as some things change, some stay the same

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.