Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 430

Slowing global trade not the threat investors fear

Contributing authors: Jonathan Lemco, Asawari Sathe, Adam J. Schickling, Maximilian Wieland, and Beatrice Yeo, from the Vanguard Investment Strategy Group’s Global Economics Team.

The last 12-plus months have emphasised that the COVID-19 pandemic would accelerate trends already in place. One of these trends is the shortening, and in some cases the reshoring, of supply chains, as business leaders question whether their supply chains have been stretched too far and become too complex.

Such a trend raises a natural question: Is globalisation dead?

New Vanguard research, The deglobalisation myth(s), concludes that, no, globalisation isn’t dead. Instead, global trade growth is likely to slow, as it’s been doing since the GFC. This slowing in global trade growth, what we term ‘slowbalisation’, is unlikely to turn into a contraction in global trade. What’s more, the implications for investors are only modest.

A slowbalization scenario is the most likely outcome
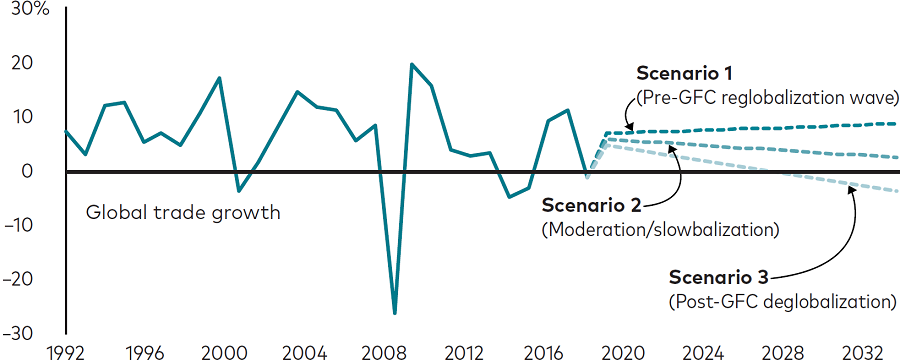
Sources: Vanguard calculations, using data from the World Bank, the Organisation for Economic Co-operation and Development, and the KOF Swiss Economic Institute.

The allure of global trade is understandable

Companies that produce goods or provide services want the largest possible markets for their outputs. But a structural expansion in supply chains, which boosted gross trade in the 1990s and early 2000s, started to slow even before the GFC. A turn toward protectionism - government policies that favour domestic industries - over the last decade in the face of rising inequality in developed economies is likely to similarly tap the brakes on global trade.

We note that other aspects of globalisation, including international capital flows, knowledge sharing, and geopolitics, carry potentially significant economic, societal, and environmental consequences. Our latest research focuses on just one aspect of globalisation that addresses a specific concern of investors: the trade of goods and services.

The concern is that slowing global trade growth may reduce corporate earnings and profit growth and, by extension, weigh on equity prices. After all, a globalisation wave that began in the 1990s coincided with a six-fold increase in S&P500 Index earnings per share and more than a doubling of profit margins, contributing to almost 90% of the index’s price return over most of three decades.1

Risks to investors may not be as great as they seem

But we contest the view that globalisation has been the central factor in the expansion of these return drivers. Our research demonstrates an inconclusive or weak relationship between earnings growth and changes in trade dependency. And it shows that industries with the greatest increase in profit margins since 1990 - finance and insurance, and office and computer machinery are examples - have experienced only modest changes in trade dependency.

Trade tensions that precipitated sharp bouts of market volatility just a few years ago underscore the importance that investors ascribe to global commerce with few impediments. No doubt, geopolitical risks are ever present and worthy of attention. But our new research quantifies risks related specifically to a future of slowing global trade growth, and we believe that these risks to investors aren’t as large as they’re sometimes portrayed.

Rather, we emphasise conclusions shared by our new research and our December 2020 research A Tale of Two Decades for U.S. and Non-U.S. Equity: that corporate earnings growth hasn’t been a major contributor to U.S. equity outperformance in the past and that we shouldn’t expect it to have a meaningful impact on future outperformance or underperformance.

Valuations, or the price investors pay for earnings, represent the most important signal for future asset returns.


1 The average annual S&P 500 Index price return from 1990 to 2018 was 7.4%. Three factors make up this return: valuation expansion/contraction (dollar paid per dollar of earnings), earnings growth from revenue growth, and earnings growth from ratio of earnings to revenue (profit margins). Contributions from these factors were 0.8%, 3.7%, and 2.9%, respectively. 


Vanguard is a sponsor of Firstlinks. This article is for general information and does not consider the circumstances of any individual. For more articles and papers from Vanguard, please click here.


  •   20 October 2021
  • 1
  •      
  •   

RELATED ARTICLES

The folly of the Iran war

Europe: A new growth trajectory powered by reform and investment

REITs: a haven in a Trumpian world?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.