Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 78

SMSF borrowing and residential property

I made a personal submission to the Financial System Inquiry, based on several articles written for Cuffelinks, on the subject linked here: Should SMSFs be allowed to borrow?

My conclusion was:

"Leverage increases risk, and when this is widespread across an asset class, financial crises can be exaggerated by forced sellers. The best example is margin lending, where banks have the right to force investors to sell assets to maintain margin ratios. In troubled times, assets look for buyers but everybody is trying to preserve liquidity.

Given so much leverage in our system outside of superannuation, do we need to add more potential risk and volatility into the system generally, and superannuation in particular? Our retirement savings are supposed to reduce the future drain on pension payments, and an investor who loses money from a poor leveraged investment may become a long-term drain on public resources.

Property differs from shares as it is usually a single indivisible asset, which cannot readily be sold brick by brick. The sole purpose of superannuation, and the reason it is given favourable tax treatment, is to fund a retirement, and to do this, it must generate income. Leveraged investments usually carry an interest cost, and unless the revenue exceeds this cost, there is a net cash outflow. What happens when interest rates rise, or the property has a long vacancy period, or a major repair is required? What if the SMSF trustee loses their job and is not making other contributions to super? The SMSF trustee may be forced to sell the apartment at the worst time in the property cycle.

This paper has demonstrated:

  • the dramatic downside of leveraged returns in a falling market
  • the low net yields generated by many residential properties when all costs are considered
  • the spruiking techniques some agents use to target SMSFs
  • the role that superannuation plays in funding a retirement.

Many highly leveraged SMSFs would lose all their own equity if there is a decent residential property price correction. Anyone who doubts the potential problems should attend a property seminar aimed at SMSFs and listen to the techniques used."

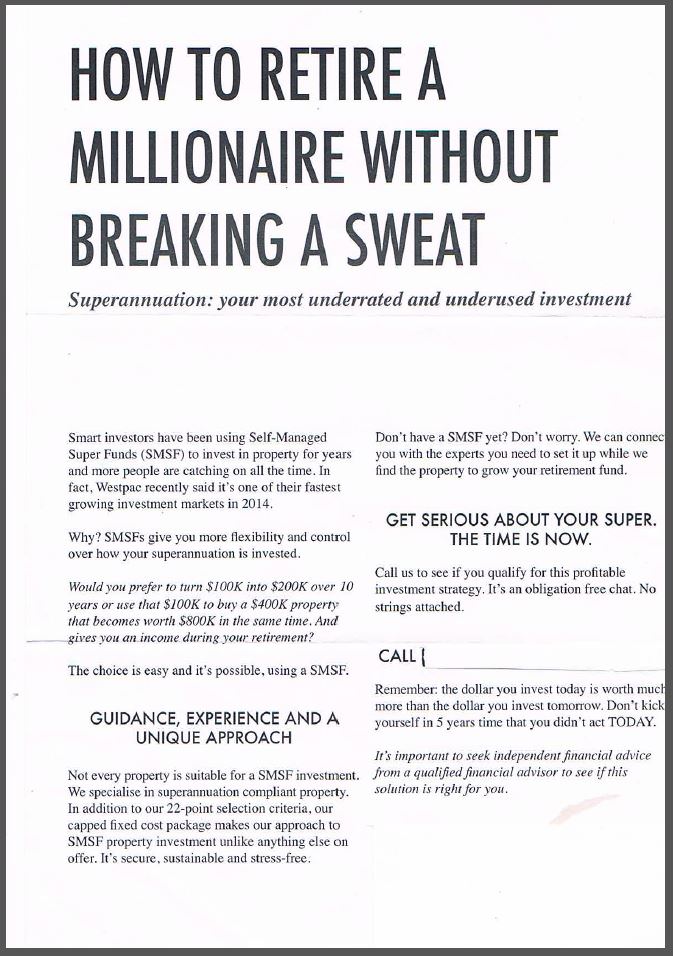
And as if to emphasise the point that SMSFs will be targeted for property, this leaflet arrived unrequested in a direct mail drop to everyone in my suburb on 'How to retire a millionaire without breaking a sweat' (sic - it should be 'breaking into a sweat'). Thank goodness the Reserve Bank Governor, Glenn Stevens, issued a warning this week that house prices can fall as well as rise.
 

  •   4 September 2014
  • 7
  •      
  •   
7 Comments
Mark
September 05, 2014

I know of no other major country in the world other than Australia that allows retirements to borrow money to invest with the risk that retirement savings could be wiped out as a result.

It is playing Russian Roulette with one's retirement years by doing so.

Warren Bird
September 05, 2014

I've said it on another thread, but have to say it again. The issue is not leverage, it's risk management. Every share is a leveraged asset and I can't see how you can rule out the fund borrowing to buy an unleveraged asset if you are prepared to let it invest in something that borrows within its own structure.

The reason most funds shouldn't be 'allowed' to borrow to buy a property is that it typically results in a highly concentrated portfolio - the geared property and little else, most likely. It's that concentration in an illiquid asset that makes it a risky strategy, not the borrowing.

Introduce suitable rules about concentration of risk and the question of borrowing for a property will become academic - and the real issue will be getting addressed.

Ben Smythe
September 08, 2014

I must admit that I have sat on the fence with this issue for a while - on the pro side, leverage is a legitimate wealth accumulation consideration and on the negative side in the wrong hands it can be a disaster.

The Government's reluctance to restrict the proliferation of overnight "SMSF property" experts has now drawn me to the side of banning SMSF borrowing going forward. While the numbers are still relatively small, it is too concerning watching these property spruikers double as personal superannuation advisers. Their "structures" are set up predominately to advantage themselves, and if the SMSF members make money then that is a bonus.

The damage that will be done/is being down to SMSFs as a legitimate retirement savings vehicle also needs to be taken in to consideration as the whole SMSF industry will be "tarred with the same brush" as more SMSF members lose their savings.

Guy
September 10, 2014

I agree - no debt allowed in SMSF's whatsoever.

There should also be a maximum annual limit on withdrawals so the fund is not used to repay mortgages etc outside super..

Ian Kredulis
September 12, 2014

How have LRBA assets within SMSFs hit $8.7bn (ATO estimate as at 30 June 2014)? Here's my experience. A few weeks ago I took a call not long after getting home from work. The voice (a mature sounding gentleman) barely allowed me to say 'Hello' before launching into a question: how would I like to pay up much less tax?

Hmm. Having a pretty good idea where this was going I played along. Did this have anything to do with property investing? Possibly said the cold caller. SMSFs? Maybe. He seemed very keen to establish my age & income, and that of my wife (pre-qualifying perhaps?). After some basic chat about how much tax we pay (way too much according to the caller) he asked for contact details & informed that a colleague would call soon to arrange a free 'consultation' to discuss wealth opportunities.

In short order I took a call from a female who identified herself as representing a "diversified" financial services entity committed to helping hard-working Australian families like ours get ahead. The vehicle of choice for their wealth strategy? Residential property. Held within a SMSF. Did we have one? Did we know of the myriad of tax advantages available by using an SMSF?

The caller's remit was clearly to dangle enough shiny baubles in front of me to get an appointment with a 'Consultant'. Was this Consultant a Financial Planner I asked. No, but he could assist with "coordinating" all aspects of the plan (which I assumed meant setting up an SMSF & arranging the LRBA facility).

I set up an appointment for a week hence, put the phone down and within 10 minutes on Google had established this cold calling company as being a mortgage broker. It was a corporate credit representative of another entity holding an Australian Credit License. Not licensed to provide financial product advice under an AFSL its website nonetheless suggested that it could facilitate the provision of various service providers including realty managers, conveyancers, accountants, financial planners and lawyers.

Having done my own due diligence I called back to cancel the appointment. Many others however would have been paid a home visit by their 'Consultant'. Many of these people might now have a brand new SMSF awaiting the purchase of a property under the LRBA rules. For some, the desire to avoid 'paying too much tax' may come at a much higher price.

Martin Mulcare
September 14, 2014

There is no doubt that too many inappropriate people are taking inappropriate advice to establish sub-optimal SMSFs. There is also no doubt that it will end in tears for many people. When ex-rugby league players are promoting SMSFs on Sydney radio we should all be alarmed!

Ian Kredulis
September 15, 2014

Agreed Martin. There are two forces at play here. On the 'provider' side, there is too much easy revenue available to not flog LRBA property via SMSFs. It really is money for jam. There are a whole range of entities with snouts firmly placed in the LRBA-via-SMSF trough.

On the demand side, there is only one word needed to convert a fence-sitter into a hot prospect: "Tax". Most Australians might not understand complex investment-speak but they get tax; "the less I pay the better off I am". And that's all LRBA property spruikers need to keep the sales pipeline full.


Leave a Comment:

RELATED ARTICLES

Property excitement, a Saturday auction and an SMSF

SMSF borrowing for land development is not fertile ground

Residential investment property fails simple valuation test

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.