Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 476

The wealth-destroying impact of inflation

The recent return of inflation has spurred a sudden surge in interest in the implications for investors. In reality, inflation has always been a destroyer of the spending power of money, and therefore of critical importance for investors, even in the so-called ‘low inflation’ years.

Don't underestimate the impact of inflation

The chart below shows the impact of inflation on $100,000 in assets or income over time in Australia, from different starting points. For example, $100,000 of assets or income in 1980 was a lot of money at that time (the median Sydney house price was just $69,000 in 1980) but $100,000 in 1980 dollars would have been whittled down to just $19,000 in today’s dollars if you didn’t protect it against inflation.

Another way of looking at it is if you had $100,000 in cash in 1980 and locked it in a safe then opened the safe today, you still have that same $100,000 but it would only buy $19,000 worth of today’s goods and services. (Or if you invested in term deposits in 1980 and you lived off the interest). Inflation over the years has eaten away 81% of its purchasing power.

The 1980 ‘real’ (i.e., after inflation) value line is the pink line starting from 1980 near the middle of the chart. We can see that the real purchasing power of $100,000 in 1980 decayed very quickly in the high inflation 1980s, but then the rate of value decay eased off (a less steep downward value decay curve) in recent decades. The section at the bottom of the chart shows the annual CPI inflation rate in Australia since 1990. Inflation was very high in the 1970s, then declined in the 1980s, and has been relatively ‘low’ in the 2000s and 2010s decades.
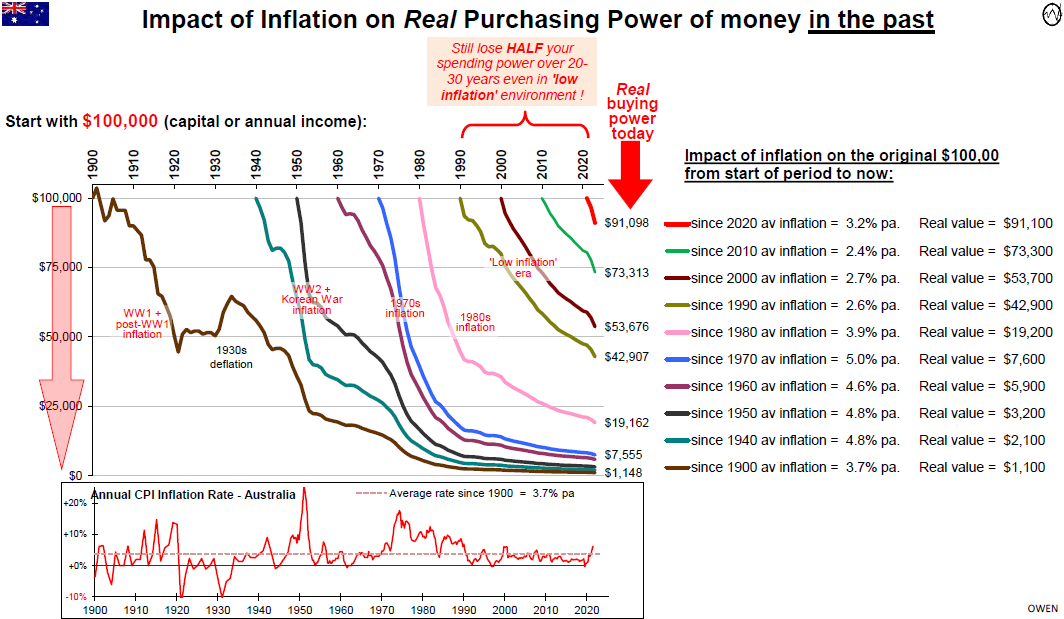
The problem is that, even in these so-called ‘low inflation’ years, inflation still had a serious detrimental impact on wealth and incomes. For example:

  • $100,000 starting in 1990 has been eaten away to a purchasing power of just $43,000 today.
  • $100,000 starting in 2000 has been eaten away to a purchasing power of just $54,000 today.
  • Even in the ultra-low inflation post-GFC years, $100,000 in 2010 has been eaten away to a purchasing power of just $73,000 today.
  • In the past two years alone, $100,000 at the start of 2020 has already lost 9% of its purchasing power to $91,000 today (the steep red value decay curve to the right of the chart).

The wealth-destroying effects of inflation never went away. Remember how central bankers dreamed about reviving inflation in the post-GFC years, and especially in 2020-21. We are all paying for that now!

Planning for future inflation

The next chart shows the impact of inflation on the purchasing power of money over time, at different rates of inflation. Obviously the higher the rate of inflation, the greater the destruction of the real purchasing power of money.
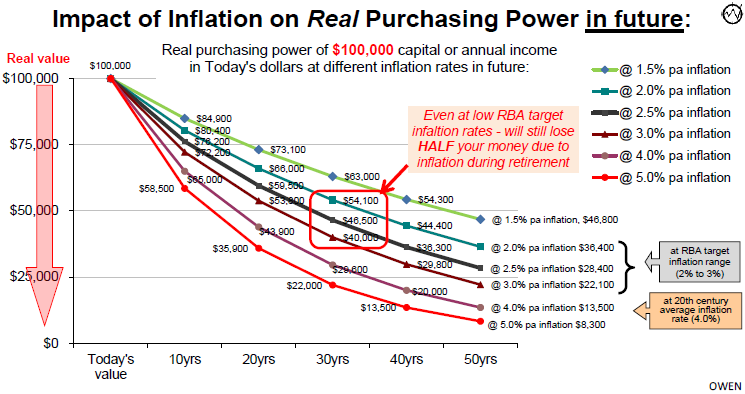
Even if inflation can be contained within the RBA’s target range of 2-3% per year, money still loses half of its purchasing power over 30 years (highlighted in the red box) if we don’t invest in assets that at least keep pace with inflation. Even if inflation were contained at a very low 1.5% per annum, you will still lose 37% of purchasing power over 30 years.

The second key lesson from this chart is that the longer we need the money to last, the more of it is eaten away by inflation, and therefore the more important it is to invest in ‘growth’ assets that offer some inflation protection.

In previous generations, time in retirement was relatively short. Most people had working lives of 40 years or more (from their late teens to retirement in their 60s). Retirement was usually only for half a dozen years or so, if that. Inflation, and even high inflation, did not have much time to work its destructive damage on their savings, and most people lived off the age pension, which was indexed to wage inflation.

Now, a large proportion of the population live well into their 90s, or even past 100, and life expectancy is increasing further with advances in medicine and nutrition. Retirement funds need to last several decades, and so the capital values and incomes need to be invested in growth assets to keep pace with inflation for several decades.

The need for growth assets over time

There are many types of assets used in long-term investment portfolios, but they fall into two main groups – ‘growth’ and ‘defensive’ assets.

The main types of growth assets are equity (ownership) interests in businesses (e.g., in the form of shares in listed or unlisted companies), and real estate (residential, commercial offices, retail shops, etc.). Companies (especially of diversified mix) can often offer good inflation hedges, with rising revenues, profits, dividends and capital values. In the case of property, well located and managed properties (especially a diversified mix) can also see their rents and capital values rise with inflation, depending on their location, supply and demand for tenants, etc. The main downside with ‘growth’ assets is that the income (dividends, rent), and also their capital values, can suffer big falls in business/credit cycles, especially in broad economic recessions.

On the other hand, defensive assets are mainly debt funds lent to governments (in the form of treasury bonds, notes and bills), debt funds lent to businesses (corporate bonds, notes), debt funds lent to banks (bank deposits, bills, notes and hybrids), and debt funds lent to property owners and developers (mortgages, debentures).

In essence, with ‘defensive assets’ you are a lender, but with ‘growth assets’ you are a part-owner.

The defensive (debt) assets are usually favourites with retirees because they offer advantages of regular, relatively reliable income, and usually relatively stable capital values. The downside of their relatively stable capital values and income is that capital values (and future income) do not provide any protection against inflation. They suffer the inflation decay illustrated in the above charts. People investing for periods of more than a few years (which includes almost all retirees) still need high quality, diversified ‘growth’ assets in their portfolios.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is for general information purposes only and does not consider the circumstances of any individual.


  •   21 September 2022
  • 13
  •      
  •   
13 Comments
Dudley
September 21, 2022

"same $100,000 but it would only buy $19,000 worth of today’s goods and services": However, had the $100,000 been invested at best retail interest rates On 1979/Dec/31 until 2022/Aug/31: Untaxed it would have grown to $2,132,362.74; an increase of 21.3 times. Taxed 30% it would have grown to $853,960.25; an increase of 8.52 times. During which, CPI increased from 24.9 to 126.1; an increase of 5 times.

JW
September 21, 2022

Hi Graham - Love this article. Very sobering. And so agree about reading the same material over and over again!
Enjoy your day of mourning.

Lloyd
September 21, 2022

Dudley, you have assumed re-investment of the interest. A retiree will spend the interest, not that there would be enough in the last decade of low returns, so there would be no growth.

Dudley
September 21, 2022

An Age Penion eligible retiree would dump all but $419,000 in the Principal Place of Residence and draw the Pensioner and Beneficiary Living Cost Index (PBLCI) indexed Age Pension worth several million depending on the inflation rate and recipients longevity. And homes have total return of roughly 6% to 9% / y compounding since 1979 - about 10 to 32 times increase - and no tax.

A super accumulator would pay 15% tax still grow relative to CPI.

Jack
September 21, 2022

Hi Dudley, what is your estimate (at current interest rates and inflation) of the value of a full age pension if someone had to buy it from a commercial provider?

Dudley
September 21, 2022

"value of a full age pension if someone had to buy it from a commercial provider":

Commercial involves returns plus profit commensurate with risk - so instead lets look at what a 0% taxed super retirement account could do.

For 28 years retirement buy Commonwealth Treasury Indexed Bonds CPI+1.00% maturing 21-02-50 paid quarterly. Price is ~$89, redemption value $111.30, redemption value is CPI indexed, coupon is 1% per year of indexed redemption value.

Yield to maturity 1.94% / y. Running yield (cash in hand) is 1.25% / y.

To match Age Pension cash payments of 26 * 1547.60 = $40,237.60 / y, capital required:
= 40,237.60 / 1.25%
= $3,219,008.00


David
September 22, 2022

When Bob Hawke introduced the CGT, the initial law was that it applied to gains after inflation. Eventually that was deemed to be too complicated (or too generous according to some), so they made it "simple" by giving a concession of half would be non taxable and did away with indexation. Many people think this is too generous, but if you purchased an asset in 1990 (after CGT kicked in), for $43k, to use the above figures, and sold it for $100k in 2022, thereby just keeping pace with inflation, you would still be liable for tax on the capital gain of half $57K , or $28.5k. How is that fair? Much the same as the Reserve Bank penalising savers and giving benefits to borrowers for years. Inflation is a tax that doesn't have to be approved or voted on. That's why gold was demonetised.

CW
September 22, 2022

Dudley, I think to work out the value of aged pension , you need to run the capital down to zero on year 28, with annual inflation adjustment?

Dudley
September 22, 2022

"run the capital down to zero on year 28":

From the Commonwealth's perspective that is the equivalent of not having the means to pay Age Pension to anyone after 28 years hence.

From the Age Pensioner's perspective that is the equivalent of having no capital to yield income after 28 years hence.

Whereas, if the capital is CPI indexed and not spent, the capital to yield income exists after 28 years and can pay the equivalent of the Age Pension to the surviving or a different Age Pensioner.

David Toohey
September 26, 2022

"From the Commonwealth's perspective that is the equivalent of not having the means to pay Age Pension to anyone after 28 years hence."

No, CW is right - in practice.

Some Age Pensions cease before 28 years, and some continue after 28 years, but the valuation assumption is that the mortality experience of the pool of retirees converges to the average of the assumed mortality of the population.

The Actuaries 101 lesson shows you how to calculate the NPV of the annuity:
discounting by the real interest rate (in this case the assumed earnings rate less the assumed inflation rate, which is actually Average Weekly Earnings),
and discounting by the annual death rate, which increases as you go along, because the probability of surviving to your next birthday decreases as you get older.

In practice, as CW notes, you can think of it as a fixed term annuity that ceases on the date of expected death, but it's not technically correct.

Dudley
September 26, 2022

"Some Age Pensions cease before 28 years, and some continue after 28 years, but the valuation assumption is that the mortality experience of the pool of retirees converges to the average of the assumed mortality of the population.":

"NPV of the annuity":
Real (inflation adjusted) value to be invested in a fund at time 0 y:
= PV(0%, 28, 26 * 1547.6, 0)
= -$1,126,652.80

At time 28 y, all capital is spent.
For subsequent Age Pensioners no capital and no yield to pay Age Pension. Ditto survivor.

With capital indexed bond, at time 28 y, capital of same value as time 0 y exists. Yield alone continues to pay Age Pension equivalent. The amount of capital calculated being the amount of the Age Pension equivalent divided by the yield rate / y.

David
September 22, 2022

Inflation and taxation are closely linked. Taxation is a direct method of funding government and inflation is indirect. When direct taxation reaches its limits and growth slows because of the reduction in private savings for investment, then governments resort to deliberate inflation. Its in the Reserve Bank charter. Currency debasement is the first step and now that precious metals are no longer used for money, currency can sink to its intrinsic value, ie nothing. Government borrowing mounts in financing the ever growing demands of voters, and inflation silently reduces the value of the debt over time. It is never paid back, just refinanced. The USA has gone further down this path than Australia, and is a role model. A similar currency debasement saw the end of the Roman empire.

Lyn
September 25, 2022

Interesting article. On practical level, pondered no matter when or what words used at the time re finances be it inflation, stagflation, growth/defensive assets, low/higher interest rates etc., I can't help notice weighing
up expenditure decisions now the same as 50yrs ago -- make do and mend when saving for home and 50yrs later will I spend $200 on new sheets or "turn sides to middle" of existing for extended use? I didn't expect to turn sides to middle in retirement until I studied above very sobering charts, think Keep calm & carry on needs to be applied (to me) after reading the charts.


Leave a Comment:

RELATED ARTICLES

The most important investment decision you’ll ever make

Inflation is the biggest destroyer of wealth

Is FOMO overruling investment basics?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.