Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 104

Why investors buy bonds at negative yields

Numerous European countries now have short, medium and even long term government bonds issued in local currencies (including Euros) offering investors negative yields, such as Germany, Switzerland, France, Denmark, Netherlands, Sweden, and even Ireland and Portugal! Why would anyone invest when they receive less back on maturity than the original investment? It’s not for the interest payments – most offer interest coupons of only a fraction of a per cent.

The chart shows yields on 10 year government bonds rising during the 2010-12 ‘PIIGS’ crisis and then declining as Europe slowed into deflation prompting the start of Eurozone ‘quantitative easing’. The PIIGS countries of Spain, Italy and Portugal have experienced dramatic reductions in their borrowing costs. Bond yields fell again in March 2015 in most markets, with the main exceptions being Greece where yields rose as it lurches toward its third bailout or possible Euro exit, and Japan, where yields also rose a little with its money printing efforts and exit from recession.
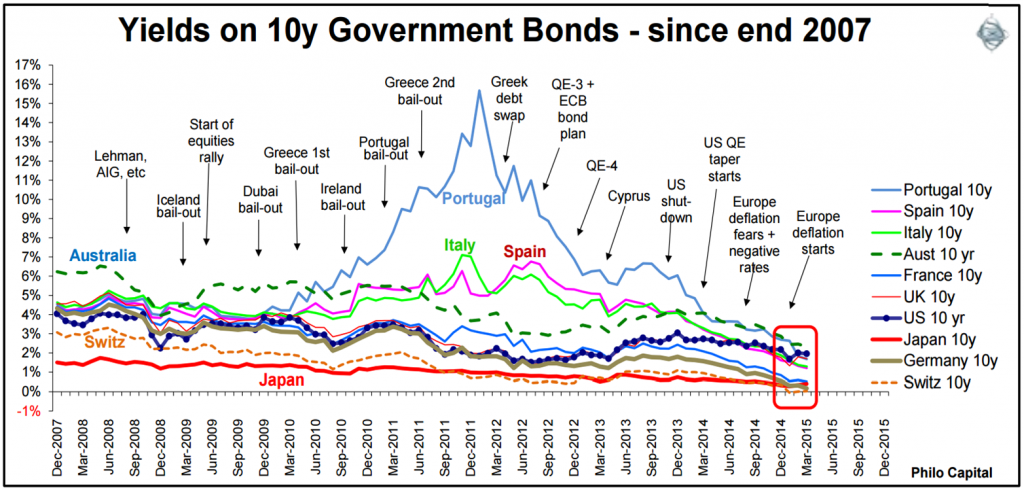
European investors are either predicting decades of price deflation ahead, so a buyer could make a positive real return (after negative inflation), as Europe entered deflation late last year. Or they are simply terrified of putting their money anywhere else. They prefer buying loss-making bonds instead of just hiding their money ‘under the bed’ or in a safe at home or in a deposit box at their local bank branch, where they would at least get their money back intact. They seem to prefer the certainty of losing money invested in government debt rather than the remote risk of theft if their homes, banks or countries are invaded and plundered. Switzerland makes sense as a safe haven for Europeans, but Germany? Germans tried to conquer Europe by military force three times in the past 150 years!

With yields so low, investors are accepting longer and longer terms in the search for yield, fuelling a boom in multi-decade sovereign and corporate debt. On 10 March 2015 the UK government issued 53 year bonds at an incredibly low 2.62% yield as the UK enters deflation.

It is correct that most government bonds in the world (including Australia) are trading at a premium to par so investors who buy them now are guaranteed to make a capital loss. And that's if the government pays which it probably will, although Australia has defaulted in the past. And that's before inflation. If inflation rises from zero or negative at the moment back to rising a couple of percent, those long term bonds could drop by 20-30% in value.

There is a way out of losing money, of course. When a PIIGS country exits the Euro, its own currency is likely to plummet. If there is a ‘Grexit’, the Greek Drachma will probably drop 30-50%, so Greek investors in Euros will make handsome returns, even if they initially invest at negative yields. The low yields are a bet against the Euro holding together.

That's if the Germans give them their Euros back at maturity. In the meantime, European bonds and shares are generating outstanding returns in the short term under ‘QE Europe’ as yields fall, the Euro falls and share prices surge.


Ashley Owen is Joint CEO of Philo Capital Advisers and a director and adviser to the Third Link Growth Fund. This article is educational only. It is not personal financial advice and does not consider the circumstances of any individual.


  •   10 April 2015
  • 2
  •      
  •   

RELATED ARTICLES

Are bond yields lower forever or is the Big Bang coming?

Briefly, on the role of government bonds

A journey through the life of a fixed rate bond

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.