Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 253

Five reasons why emerging markets lead tech

Emerging markets are at the forefront of global technology growth. Many emerging market tech companies are the most innovative and fastest growing in the world, driven by young, increasingly affluent and tech-savvy populations. The MSCI Emerging Market Index now has the largest technology weighting of any global index, with its share rising from 13% at the end of 2010 to 28% by the end of January 2018.

Here are five key reasons why emerging markets leads the tech revolution:

1. Huge appetite for tech

The sheer size of populations in emerging markets is itself an opportunity. While internet-user growth has been blistering, there’s still plenty of room for expansion. China’s 730 million online population is larger than that of the European Union and US combined but represents only half of the country.

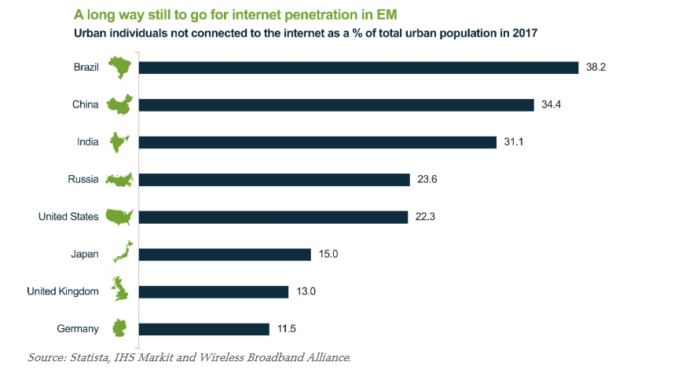
A significant percentage of the ‘unconnected’ in China and other emerging markets like India, Brazil and Russia are urban dwellers (see chart below), which means they can be added relatively fast and cheaply. The youthful demographic profiles of many emerging markets are a real tailwind for technology, given faster adoption and creativity that characterises younger generations.
2. Power of the mobile phone

A large proportion of the population in emerging markets is accessing the internet via smartphones, and this has spurred phenomenal innovation. China’s Tencent, for example, has built a whole content-driven social-networking ecosystem through mobile internet. This includes e-finance, e-commerce, ad-platforms, online-to-offline services, travel and mobile gaming – effectively making it a Facebook, PayPal, WhatsApp, and Amazon all rolled into one. US companies may have spearheaded personal computer internet services, but emerging market tech firms are leading the mobile internet revolution.

3. Taking the lead in FinTech

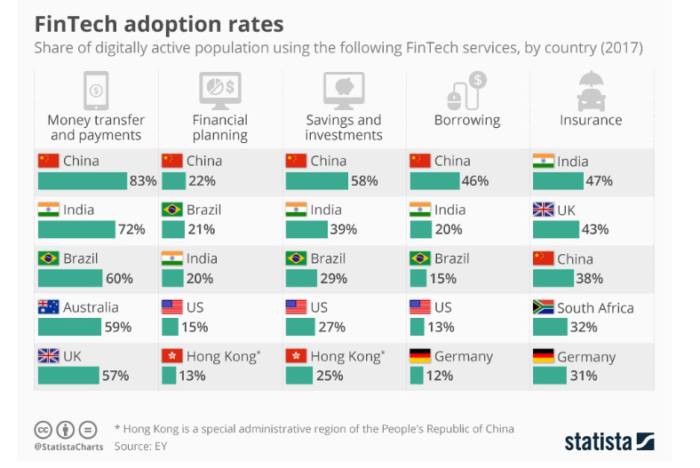
FinTech – the fusion of finance and technology – is a prime example of an area where emerging markets are outpacing their developed counterparts by some margin. This is assisted in no small measure by the mobile revolution, but also broader efforts to improve financial inclusion. Whether it be money transfer & payments, savings & investments, insurance or borrowing, emerging markets exhibit more enthusiastic use of FinTech than elsewhere.

Emerging market financial institutions have also been quick to embrace technology, making them world leaders in the use of electronic distribution channels. The bank with the largest Twitter following in the world is not of developed-world provenance, but India’s Yes Bank.
4. Governments are on board

Emerging market governments are keen to use technology to increase efficiencies and reduce cost. What’s more, demographic pressures have forced governments to focus on their young and increasingly affluent populations. This rise in income and social mobility is most starkly illustrated in Asia, where the Brookings Institute estimates that over two billion people will join the middle class by 2030.

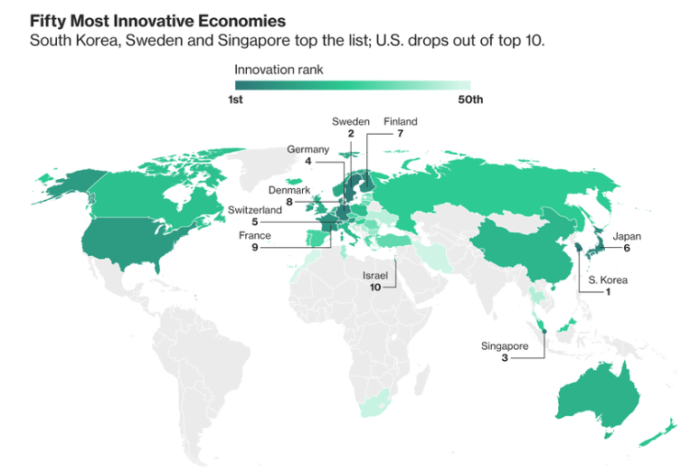
A focus on education and innovation has also helped some emerging markets steal a march on developed market competitors. In Bloomberg’s latest index of the world’s most innovative countries, South Korea again led the field, topping the international charts in Research & Development intensity, value-added manufacturing and patent activity, and with top-five rankings in high-tech density, higher education, and researcher concentration.
Source: Bloomberg, International Labour Organisation, International Monetary Fund, World Bank, Organisation for Economic Co-operation and Development, World International Property Organisation, Jan 2018.

5. Emerging market tech titans

Emerging markets today boast world-class technology firms in both the hardware and software space. Chinese names like e-commerce giants Alibaba and Tencent have built huge footprints domestically (note that in China, US tech giants like Facebook, Amazon, and Google are peripheral players in their respective areas of social media, e-commerce, and search engines).

Both Alibaba and Tencent are now extending their coverage across Asia. Armed with Asia-centric games, social networking, and e-commerce platforms, we believe they will give the formerly dominant US names very tough competition. Meanwhile, other emerging market tech firms, like colossus chip-maker Taiwan Semiconductor, are central players in global supply chains – providing components for major brands like Apple.

Emerging markets – the new destination for tech exposure

Rather than catching up, emerging markets are now taking the lead in a whole raft of different areas of technology. With plenty of untapped growth left, and the highest-quality firms widening their competitive moats, we believe this area presents some of the most attractive long-term opportunities for investors.


Kim Catechis is Head of Emerging Markets at Martin Currie, a Legg Mason affiliate. Legg Mason is a sponsor of Cuffelinks.


  •   10 May 2018
  • 3
  •      
  •   

RELATED ARTICLES

The markets to gain most from US rate cuts

Is India the world's best growth story?

10 trends reshaping the future of emerging markets

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.