Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 474

If I get kicked out of the value investors’ club, so be it

Plenty of people want to know if we still call ourselves value investors, or is there a style change in our funds? It's a question we received after our recent roadshow, when we disclosed that about one-third of our Forager Australian Shares Fund (ASX:FOR) is currently invested in tech stocks.

Value can include strong growth prospects

Value investing has always, to me, meant investing in shares of a company at a significant discount to the underlying value of the business. That has often incorporated businesses with strong growth prospects, as long as those growth prospects aren’t reflected in the share price.

Wind back five years to our 2017 Performance Report, many of the best performers that year were growing businesses and tech companies.
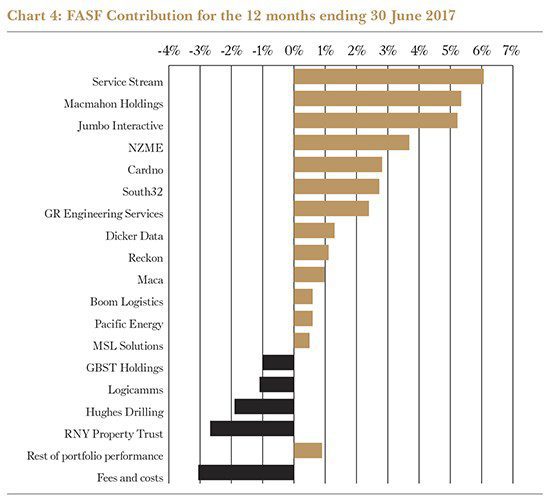
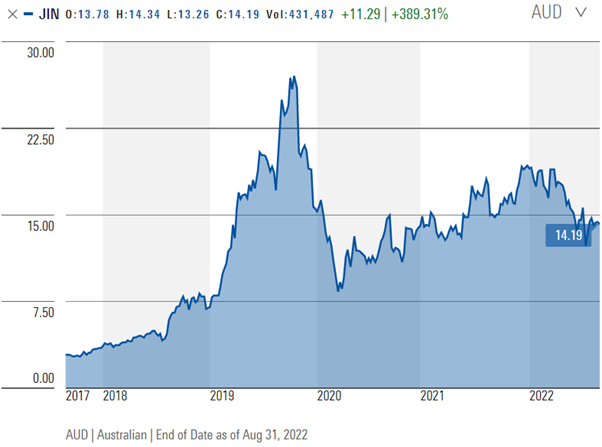
Jumbo Interactive, GBST (since delisted) and Reckon were all tech stocks. Jumbo and GBST were barely profitable at the time we bought them. Dicker Data was a growth stock (albeit one trading on a low earnings multiple at acquisition).

Jumbo Interactive
 

 Dicker Data
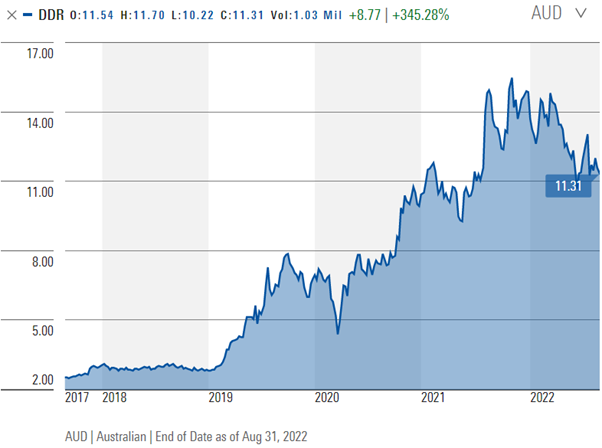
Source: Morningstar.com

Most of our historically-successful investments were businesses that grew, even if they weren’t priced to grow at the time of our first investment.

Most famous value investors are perfectly capable of valuing growing businesses. One of Warren Buffett’s most successful investments, the Coca-Cola Company, was one of the 20th century’s greatest growth stocks. Seth Klarman’s publicly-disclosed holdings currently include Amazon and semi-conductor company Qorvo.

Hanging on to the value moniker

The challenge is that the understanding of what constitutes a value investor has changed with the rise and rise of index funds. By categorising the market as either ‘value’, for stocks with high dividend yields and low price-to-earnings ratios, or ‘growth’ for those with the opposite characteristics, index providers were able to offer factor funds. 

But I’m not yet ready to give up the moniker. Value investors have appreciated growing companies since before the index fund existed, and the distinction between us and the rest is still important.

Quality and growth are not criteria for our portfolios, simply inputs into our valuations. We want to own quality when it is unloved or underappreciated, not quality for quality's sake. We currently have investments in Seven West Media, mining services and Qantas, and neither would meet a ‘quality’ filter. We simply invest on estimates of future cash returns to shareholders. That is equally true of RPMGlobal, where the earnings are going to grow.

More now, because the time is right

There are two good reasons we have ‘drifted’ towards a higher allocation to growing companies over the past few years. 

First, look back at that 2017 list and you will also see Boom Logistics, Hughes Drilling and RNY Property Trust, a cluster of asset-heavy businesses that we invested in at substantial discounts to the ‘value’ of their tangible assets. These did not work out well and were subsequently joined by the likes of Thorn Group and iSelect, similarly ‘cheap’ stocks that never generated the profits we expected. Every business has a price. But the gap between the right price for a shrinking business and a growing one is a chasm. We learned that more than once.

Second, investors should expect us to ‘drift’ a lot. We have a particularly high weighting to tech stocks at the moment but they are all established businesses with predictable and growing revenue streams.

Investors didn’t give a hoot about profits 18 months ago and tech stocks traded on revenue multiples. Today, the share prices have been absolutely hammered and all anyone cares about is profitability.

Change of accounting standards is an opportunity

Yes, some of them are currently reporting losses. But that is largely a function of significant investment in attracting new customers, rather than any reflection on the profitability of the existing customers. Twenty years ago, the accounting standards allowed companies to capitalise customer acquisition costs and spread the expense over the life of the expected revenue stream. That, predictably, led to a proliferation of aggressive and unrealistic assumptions and overstated profitability.

Today’s accounting standards, where all of the customer acquisition costs get expensed upfront, leads to understatement of economic reality.

For the value investor, therein lies the opportunity. These businesses are no more difficult to value than most, and our estimates have not changed meaningfully over the past 18 months. Yet some share prices are 70% lower, taking them from premiums to our valuation estimates to significant discounts. We buy them when they are cheap.

If those share prices rise a lot, and everyone else becomes optimistic, you should expect us to be moving on to the next sector that is out of favour.

If that gets us kicked out of the value investors’ club, then so be it.


Steve Johnson is CIO at Forager Funds, a Sydney-based boutique fund manager. This article provides general information to help you understand our investment approach. It does not consider your personal circumstances and may not be suitable for you.


  •   7 September 2022
  • 4
  •      
  •   
4 Comments
CC
September 07, 2022

Performance is what really matters, not style. 

Claude Walker
September 07, 2022

This article seems like it in part a response to my article asking if Forager Funds has changed investment style: https://arichlife.com.au/has-foragers-australian-fund-changed-investment-style/

The distinction I was making was between loss making tech stocks (now) and profitable, or at least turnaround stocks (or asset plays), previously. The Forager website says the style is “Perhaps best described as a hybrid of the Graham and Buffett styles, we view both asset backing and earnings power as useful valuation tools, depending on the type of business we are investing in.”

I think it is fair enough to ask the question when quite a few of the top holdings are barely profitable, or indeed loss making, these days. That past big 'tech stock' winner (congrats) Jumbo International had been paying dividends since 2008, and Dicker Data about the same.

If we define value investing in the way that you have defined it, then every single fund on the market is a value fund, including ARKK and Frazis Capital Partners. So you can have the mantle moniker forever, even if your style does change.

Nothing wrong with change, anyway; sorry if the question touched a nerve.

Sam
September 09, 2022

It seems like a fair question, what is conspicuous in it's absence is "Here's how I was wrong buying Thorn before or profitless tech now and how I'll avoid theses mistakes in future". Managers must learn from mistakes. 

Claude Walker
May 04, 2023

This article originally seemed to respond to my article asking "Has Forager's Australian Fund Changed Investment Style?" so I thought it worth noting a recent development that pertains to this question.

I note Lonsec has updated their view on Forager's other (International) Fund and "has some concerns around philosophical and style drift which will be acutely monitored in future reviews."

Interesting that mental gymnastics of defining all investing as value investing then claiming that you are still a value investor because you are still an investor does not seemed to have convinced Lonsec.

What is weird to me is that anyone finds it convincing, but I guess that is what makes a market.


Leave a Comment:

RELATED ARTICLES

Is the market’s recession conviction warranted?

Invest in Australian value stocks before it is too late

Global search for short-term losers and long-term winners

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.