Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 379

High growth and low rates incompatible with current share prices

Share prices around the world have divided sharply since the advent of COVID-19, with some on-line businesses rocketing in value while more traditional businesses are struggling to regain earlier lustre. Are the on-line darlings massively over-priced or are some of those currently in the doldrums significantly under-valued?

The impact of low rates on share values

Adding to the debate are arguments that the elevated valuations are justified because the cost of capital is at historically low levels. In share valuing terminology, as discount rates are lower, 'terminal value' multiples should be much higher. 

The following is a brief explanation of a standard discounted cash flow model and why the assumptions used can generate massive variability in share value outcomes.

The underlying principle is that the current price of a share is the sum of all future net profits of the business, divided by the number of shares on issue, discounted by the estimated cost of capital of that business. Valuation models are constructed on forecasts of the estimated profits of the business for the next 5-10 years, followed by an estimate of the so-called terminal value of the business (ie summing the balance of sustainable growth in profits to eternity discounted back to that date). Usually, this terminal value represents at least 60% of the estimated value of the business and is much higher for high growth start-ups.

Estimating what discount rate should apply starts with the assumption that the current long term government bond yield is the so-called risk-free rate and margins are added for:

  • the estimated relative riskiness of the industry in which the company is operating
  • the expected volatility of company performance through economic cycles (beta), and
  • the likely debt gearing the company will aim to operate with

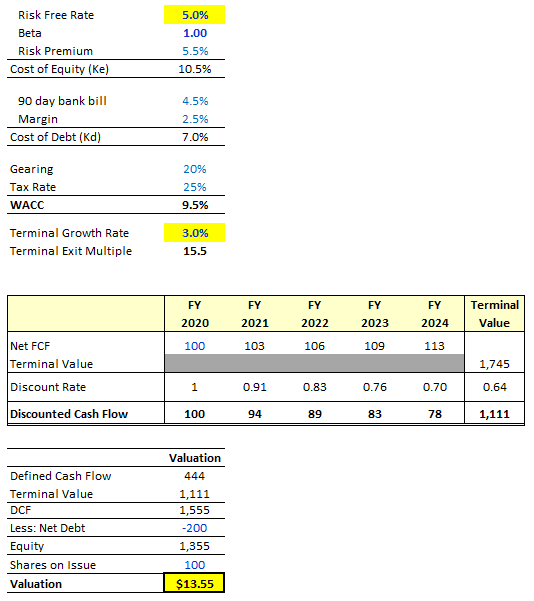
In the tables below, we have used a risk premium of 5.5%, a beta of 1 and 20% as a 'standard' industrial company gearing ratio, producing a weighted average cost of capital of 9.5%.

High growth rates and low interest rates are incompatible

It is our contention that many current valuations are assuming that real economic growth rates will resume back to what they were when interest rates were significantly higher. The fact that interest rates are close to zero right along the bond curve indicates that neither the market or central banks believe this to be the case. As such, these lower growth rates also need to be reflected in valuations to ensure a sensible outcome.

Working through the mechanics of a simple DCF we can see how these distortions play out.

We start with an 'old' set of assumptions whereby the risk-free rate is set at 5% and the terminal growth in net profits rate at 3% pa. This leads to a terminal value multiple of 15.5x and a notional valuation of $13.55 for our theoretical company.
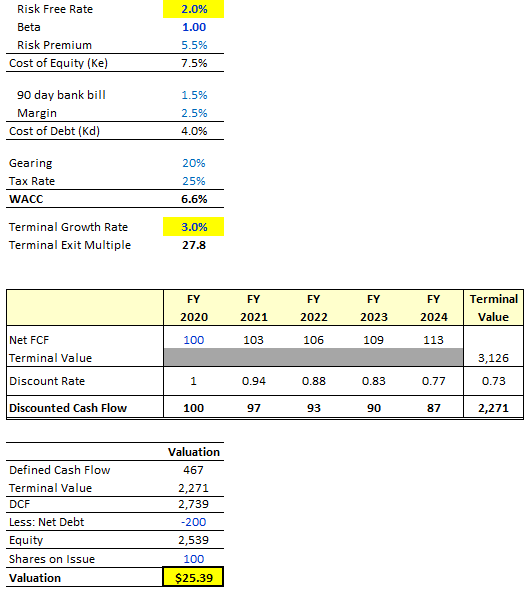
What happens when we collapse the discount rate and keep all else equal?

Taking the risk-free rate down to 2% leads to the terminal value multiple increasing to 27.8x and the valuation for our theoretical company rising 87% to $25.39. Financial alchemy at its finest!
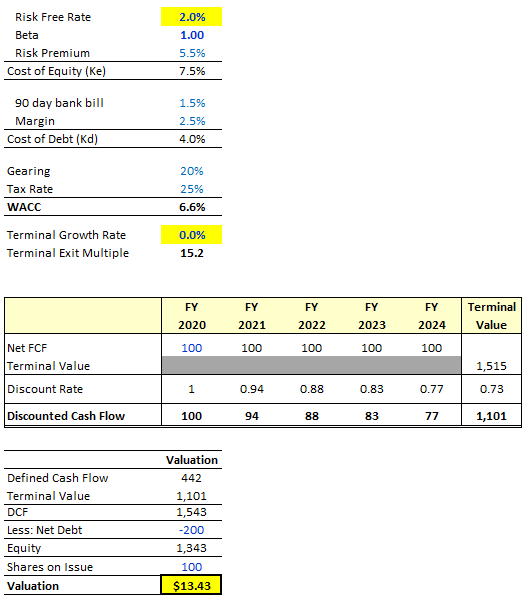
But now let’s reflect the lower growth rate implied by the lower risk-free rate. Central banks around the world aren’t setting short-term funding costs at 0% and below because the outlook is rosy. Taking the growth rate down to reflect an environment that justifies a lower risk-free rate lands us approximately back where we started in valuation terms.
Need a meaningful link between rates and growth

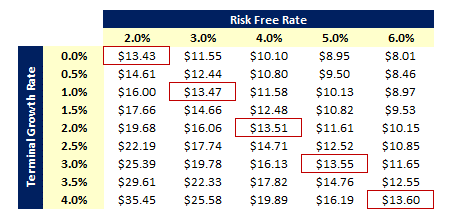
These workings highlight how critical not only the setting of the risk-free rate and the terminal growth assumption are in deriving the DCF, but in ensuring that there is a sensible linkage between them.

For our theoretical company, the table below demonstrates how a valuation can be completely overpowered by these two key assumptions; assumptions that tend to get far less attention than the detailed work that goes into deriving the cash flows of the business.
Even in secular growth companies, a recognition of the lower growth outcomes associated with a lower discount rate is essential. Apple will still sell lots of phones, Amazon lots of products and Google lots of advertising but not as much as they would have in a world that justified a higher risk-free rate.

And it is in high growth companies that the impact becomes even more pronounced. Given the lack of profits in the short term for some high growth companies (think Tesla, Netflix or even our own Afterpay) a lower discount rate provides greater weight to the distant future cash flows while also pushing an even greater proportion of the valuation into the terminal value. In these high growth companies, upwards of 90% of the valuation can sit within this terminal value.

Valuations must focus on more than cash flows

There have been many instances throughout my investment career where cash flows have broadly aligned with sell-side assumptions but the resultant company valuations have differed wildly. The explanation invariably comes down to the set of assumptions and linkages (or lack therefore) between the risk-free rate and the terminal growth rate.

My first question when comparing company valuations moved from “what are your assumed through cycle cash flows” to “what discount rate and terminal growth rate are you using” because that was where the bulk of the valuation dispersion was hidden. But in finance, as in life, if things appear too good to be true they invariably are.

The magical value creation through lowering discount rates while assuming growth is untouched is one such example that falls into this category.


Trent Masters is the Founder and CIO of Global Evolution Capital, a global absolute return fund shaped around key industrial evolutions. This article is general information and does not consider the circumstances of any investor.


  •   14 October 2020
  • 4
  •      
  •   
4 Comments
Gary M
October 14, 2020

Agree, Trent, and thanks for the worked examples. The market ignores the implications or record unemployment, bankruptcies by the thousand as soon as the director responsibilities are restored, and a debt burden that will never be repaid. Yet it's off to the races.

Trent Masters
October 15, 2020

Thanks Gary. There are a number of distortions in markets at the moment. As you identified the outcome looks fraught and that necessitates rates near zero from Central Banks globally. But it seems while the lower rates are taken through valuations by applying the lower discount rate, the lower growth rates that they indicate are neglected. Need some consistency.

Justin
October 15, 2020

Ultra low interest rates are not just distorting underlying financial and real estate asset values, they are distorting the apparently widening gap between the wealthy and the poor(ie whether this is real or just a financial mirage which will fade when the bubble bursts).
If fiscal policy is the only weapon left in the arsenal( assuming we don’t retreat behind tariff barriers and a raft of artificially contrived labour protection initiatives )there will be massive pressure to raise marginal rates of income tax, re-introduce death taxes etc . While politically attractive to the left, ever-growing government spending doesn’t create sustainable jobs via wealth creation which only the private sector can do. So Keynes’s Liquidity Trap in the current environment remains a long-term, extremely vexatious Growth Trap.

Michael O
October 16, 2020

Thanks Gary. The basis for the analysis appears to be supported by experience in Japan, and more recently Europe, with very low rates for sustained periods not providing reasonable growth. What are your thoughts on this?


Leave a Comment:

RELATED ARTICLES

The million-dollar banana and the power of story

Global search for short-term losers and long-term winners

The companies well placed to weather an economic storm

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.