(Part 1 of ‘Investing against the herd’ focussed on resisting the emotional responses which are natural instincts for most investors, and can be reviewed here. In part 2, we check whether consumer sentiment is indeed at its maximum after a period of strong share market performance - and just before the fall).
The longest running regular survey of consumer sentiment in Australia is the Westpac Melbourne Institute Consumer Sentiment series, which began in September 1974. The timing of its introduction was no accident. September 1974 was right at the bottom of the 1973-4 crash, which was longer and deeper than the 2008-9 GFC crash. (The Sydney All Ordinaries index fell 61% in the five years from its January 1970 peak to the bottom in September 1974. By way of contrast, in the recent GFC stock market crash the Australian All Ordinaries Index fell by 55% from its top in November 2007 to the bottom in March 2009, a period of ‘only’ 16 months, compared to an agonising 57 months in the 1970-1974 double-dip crash).
In the Westpac series, thousands of individuals across Australia are surveyed each month on several different aspects of how they are feeling about the economy and their finances. In addition to the overall ‘Consumer Sentiment Index’ there are also a number of other indexes including:
- ‘family finances over the last 12 months’
- ‘family finances over the next 12 months’
- ‘economic conditions over the next 12 months’
- ‘time to buy a major household item’.
The results are published in the middle of each month and are available at: http://melbourneinstitute.com/miaesr/publications/indicators/csi.html
The following chart shows the All Ordinaries Index at the top (blue line) and the monthly ‘consumer sentiment’ index (red line) and the monthly ‘economic conditions over the next 12 months’ index (bluey green line) at the bottom.
We can observe several things from this chart.
A first observation is that the consumer sentiment index seems to reflect share price performance in the recent past. In most (but not all) cases, sentiment is relatively high when share prices have been rising, and sentiment is relatively low when share prices have been falling, especially in recessions. For example:
- Consumer sentiment appears to be relatively low when share price have been falling in recessions - in the 1973-4 crash, the 1981-2 recession, the 1990-1 recession, the 2008-9 sub-prime crash and the 2011 sovereign wealth crisis.
- Consumer sentiment appears to be relatively high when share prices have been rising strongly - after the 1983 rebound from the 1981-2 recession, after the 1993 rebound from the 1990-1 recession, during 1999-2000 at the height of the dot com boom, after the 2003-5 rebound from the 2001-2 tech wreck, and in 2006-7 in the late stages of the 2000s boom.
Of course there are many factors that affect consumer sentiment besides share prices, including unemployment, inflation, the dollar, politics, petrol prices, and so on. But the link between the recent direction of share prices and the consumer sentiment scores is clear.
Statistically there is a moderate positive relationship between the consumer sentiment index and recent past share price direction (the strongest relationship is to share prices over the most recent 6-12 months). This makes sense - people tend to feel wealthier and more positive about their financial position when share prices have been rising for several months, and they tend to feel less positive when share prices have been falling.
A second observation is that consumers are most bullish at or near the top of booms, right before the booms bust, and also that they are most bearish at or near the bottom of busts, right before the market rebounds. For example:
- Sentiment was very bearish when the survey was first done in September 1974, which was right before the market rebound strongly, starting in the very next month
- Sentiment was bearish in 1977 and 1978 - right before the 1979-80 boom
- Sentiment was bearish in the 1981-2 recession - right before the market rebounded strongly in 1983 (1983 was the best calendar year ever for the Australian stock market - up 60% - but both the consumer sentiment index and the “economic conditions over next 12 months” index were near their most bearish scores ever at the end of 1982, right at the start of the tremendous 1983 rebound)
- Sentiment was bearish in early 1986 - right before market doubled in 1986-7
- Sentiment was bearish in the 1990-1 recession - right before market rebound in 1993
- Sentiment was bearish in 1998 - right before 1999-2000 dot com boom
- Sentiment was bearish in early 2009 - right before market rebounded strongly from the depths of the GFC.
- Sentiment was bearish after the sovereign debt crisis in late 2011 - right before market rebounded in 2012-13
Conversely:
- Sentiment was bullish at the end of the 1983 rebound - right before the 1984 fall
- Sentiment was bullish at the end of the 1993 rebound - right before 1994 fall
- Sentiment was bullish at top of the dot com boom in 2000-1 - right before tech wreck fall in 2002
- Sentiment was bullish in late 2007- right before the 2008 crash in the GFC
- Sentiment was bullish in late 2009 after the GFC rebound - right before market stopped rising and the market fell in the 2011 sovereign debt crisis
A third observation is that the green line for ‘economic conditions for the next 12 months’ (which measures how people are feeling about prospects for the next year) follows the same general path as the red line for the ‘consumer sentiment’ index (which measures feelings about current and recent past conditions), except it is more exaggerated.
If they are feeling relatively good about the current conditions (which is generally when the market has been doing well in the recent past), then they believe the future holds more of the same, only better - i.e. a recent past rising market is likely to keep going up in the same direction (up) as it has been recently.
On the other hand if they are feeling relatively negative about the current conditions (which is generally when share prices have been falling in the recent past), then they tend to believe the future holds more of the same, only worse - i.e. a recent past falling market is likely to keep going up in the same direction (down) as it has been recently.
Statistically there is a very high positive correlation (0.92, which is very close to a perfect positive correlation of 1.0) between the monthly consumer sentiment index (which reflects recent past returns), and the ‘economic conditions over the next 12 months index’ for the same month.
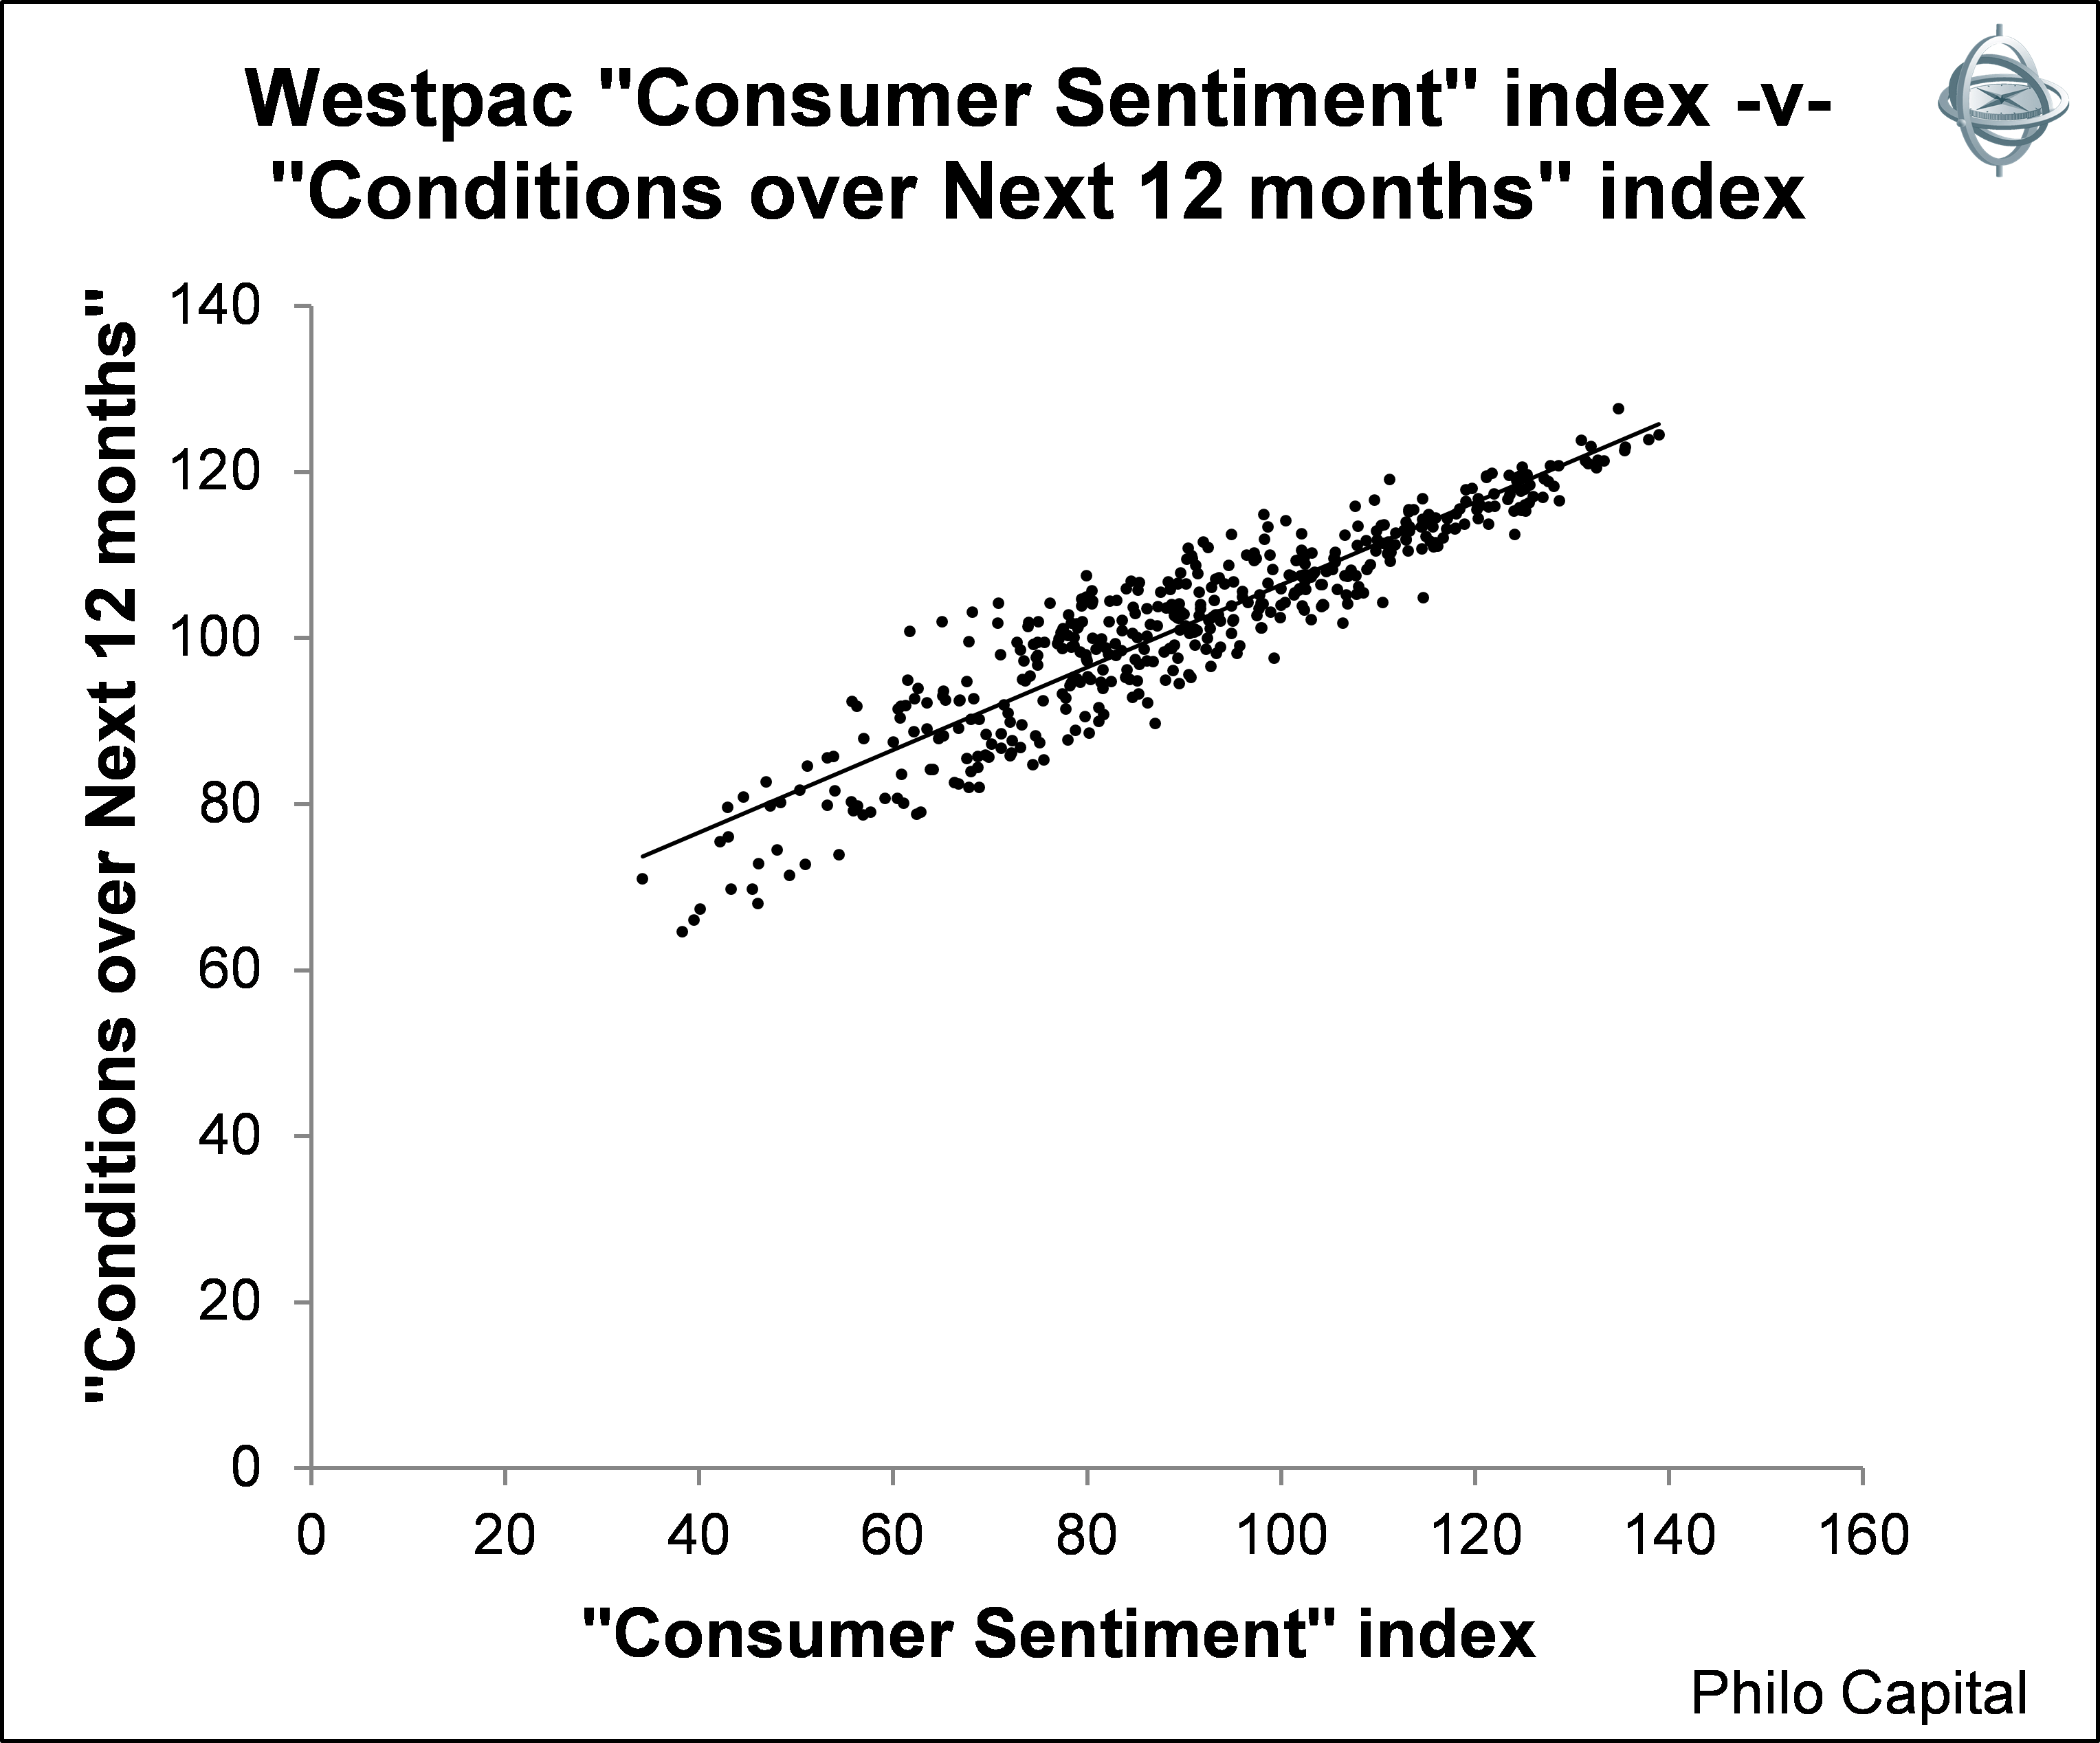
We can see that the relationship between how people feel about the present and recent past (consumer sentiment index) and how they feel about the future (economic conditions over the next 12 months) is essentially a straight line.
People tend to believe that in the future markets will keep going in the same direction they have been in the recent past - both on the way up and on the way down. This confirms the straight line extrapolations of recent past returns that we proposed in our stylized description of investor behavior in Part 1 of this series.
Next week in Part 3, we test the theory that if we went against the herd by selling some of our shares when sentiment is bullish, and buying more shares when sentiment is bearish, then we ought to be able to avoid some of the buy-high, sell-low mistakes and be better off in the long run. You may be surprised to find out just how much money you could be losing or making by following the herd.
Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is general information that does not consider the circumstances of any individual.