Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 155

Do investment principles stand test of time?

Time travel is a skill that would dramatically transform the world of the investor. Sadly, despite all the technological advances of the past two decades, the ability to go back or forward in time remains the realm of science fiction novels, not a killer app on an investor’s smartphone. While time travel may still be the domain of TV and film producers, the passage of time is a real-world test for investment ideas even if - as we are constantly reminded - history is not a great predictor of future returns.

What has changed over 20 years?

Twenty years ago, Australia was a country of 18 million people with a median age of 37 and the median weekly household income was $637 while the cash rate was set at 7.5%. The fledgling superannuation system had accumulated assets of $262 billion some four years after the super guarantee contribution had been introduced.

In 1996 a new, more modest undertaking was getting started - it was the year Vanguard established its Australian business which was its first outside the US. It seems an appropriate time to look back and see how the underlying investment principles that Vanguard has used in guidance to clients has stood up to the test of two decades.

The market has changed markedly. Of the top 10 companies by market capitalisation on the Australian share market in 1996, half have either dropped out of the top 10 or are no longer on the ASX.

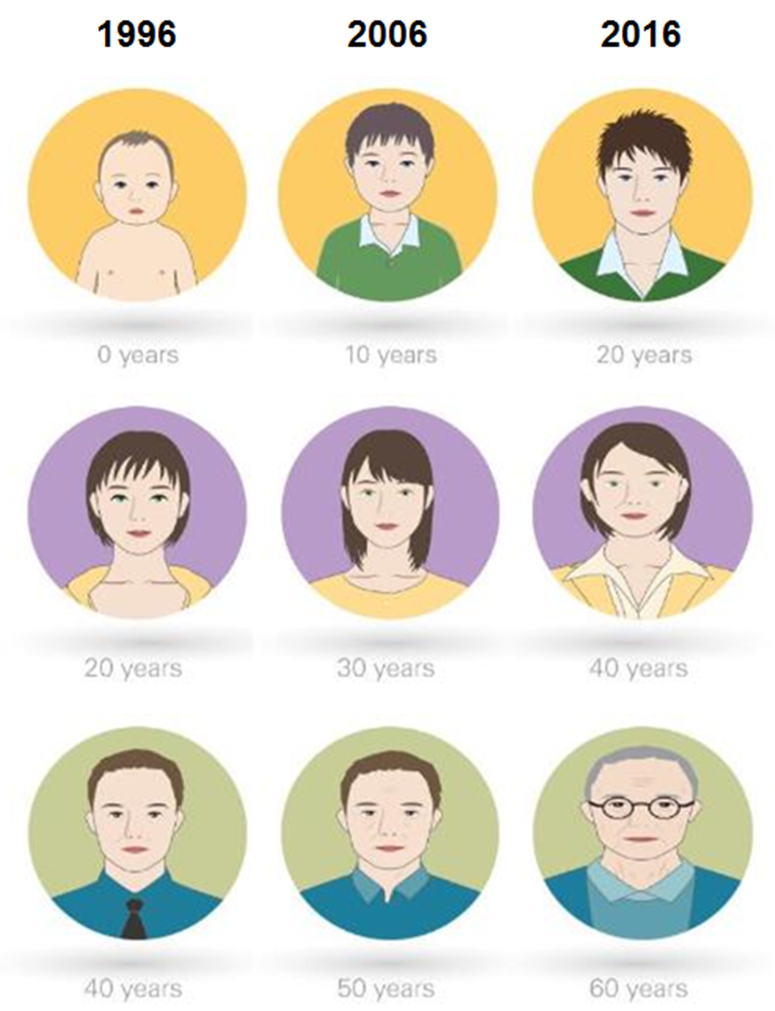
With help from actuarial firm Rice Warner, we decided to look at the past 20 years through the time capsule of three different investors in 1996 – a 40-year-old, a 20-year-old and a newborn baby – and test how our investment principles have stood up to 20 years of significant geo-political shocks, stunning market rises and dramatic declines that included a global financial crisis.
All our investment strategies are underpinned by four core principles:

  • Goals: Create clear and appropriate investment goals
  • Balance: Develop a suitable asset allocation using broadly diversified funds
  • Cost: Use low-cost, transparent investment options
  • Discipline: Keep perspective and long-term discipline

Outcomes for our three investors over two decades

One of the first lessons is that investors have been rewarded for taking extra risk.

An investor who invested $10,000 at the start of 1996 in cash would have seen the nominal value grow to $26,800. Someone who had invested in the Australian sharemarket index would have seen the portfolio value grow to $51,400. The US sharemarket index was just slightly behind at $48,100 while Australian bonds grew to $37,600.

For our three investors, Rice Warner was asked to model the superannuation outcomes. Remember back in 1996, super was really just getting started, so our 40-year-old did not get the benefit of a full career under the super guarantee nor the higher rate we have today.

The growth in the super system has clearly been one of the major developments in the Australian financial landscape in the past 20 years with it now being the second largest financial asset in average Australian households and the system growing into a savings pool of more than $2 trillion.

Our 40-year-old in 1996 is now turning 60 in 2016 and with retirement firmly in sight, Rice Warner project their super balance at retirement (assuming compulsory Superannuation Guarantee only contributions, average wages and a 7.5% gross return on investments) to be $217,000 in today’s dollars. That is projected to last until they are 74-years-old.

For the person turning 20 in 1996, and effectively just starting out in their working life, who is now 40 in 2016, the projected retirement balance is $395,000 when they reach retirement age. This money is expected to last until they are 83-years-old.

For the baby in our investor trio who is now 20, the projected super account balance accumulated during their working life is $456,000 – more than double what the 40-year-old is likely to get. It should last until they are 87.
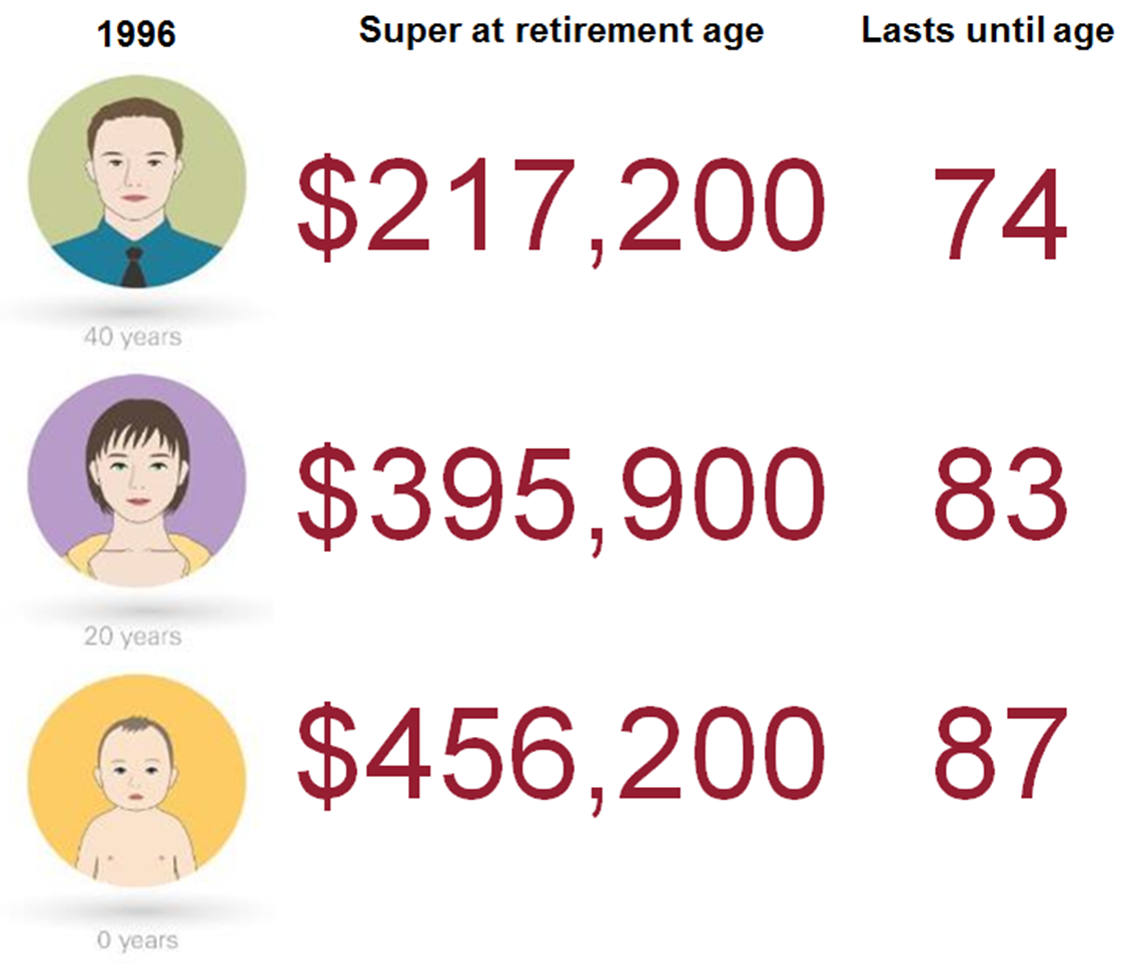

Source: Rice Warner. Assumes default super with no additional concessional contributions.

Based on the ASFA comfortable retirement standard, the baby of 1996 could reasonably expect her super to last 13 years longer than their older baby boomer counterpart.

Higher contribution rates and a long-time period to allow compounding to work is driving these outcomes but it is interesting to reflect that even after more than 20 years, our super system is not yet at maturity. The challenge remains for those in the older age bracket to be able to contribute enough to fund their retirement lifestyle.


Robin Bowerman is Principal, Market Strategy and Communications at Vanguard Australia. This article is general information and does not consider the circumstances of any individual.


  •   12 May 2016
  • 1
  •      
  •   

RELATED ARTICLES

Garry Weaven on 5 areas of super investment

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.