Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 138

Long-term investing: the destination is better than the journey

The old adage ‘time in the market, not timing the market’ is frequently used in articles like this one, with good reason – it often holds true. One of the key elements of successful investing is patience, as a long-term mindset is required to achieve investment goals. Returns in the short-term can be unpredictable and volatile, so investing with a short-term focus produces difficulties and can be counterproductive. It is easy to be fixated on the daily market movements and become distracted from long-term investment goals. It is often better to take a step back and allow investments to grow steadily over time.

Returns over different time horizons

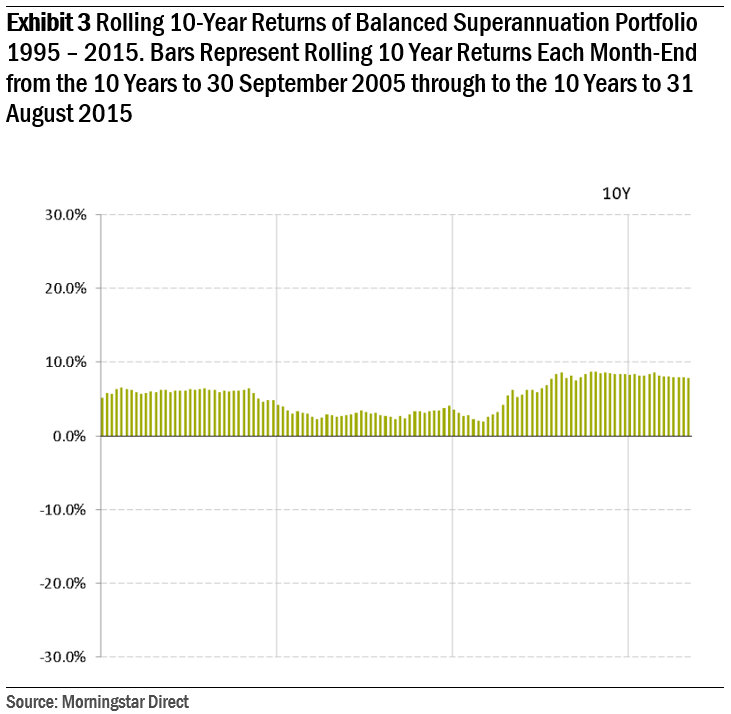
To highlight the merits of having a long-term perspective, we assessed the historical returns after fees and tax of a ‘balanced’ superannuation strategy over three distinct time intervals: rolling one-month, rolling one-year, and rolling 10-years.

Exhibit 1 shows the rolling one-month returns or the portfolio's individual month-to-month performance. The green bars above the x-axis represent positive performance and a gain in the portfolio's value. A red bar below the x-axis represents negative performance and a loss in the portfolio's value.
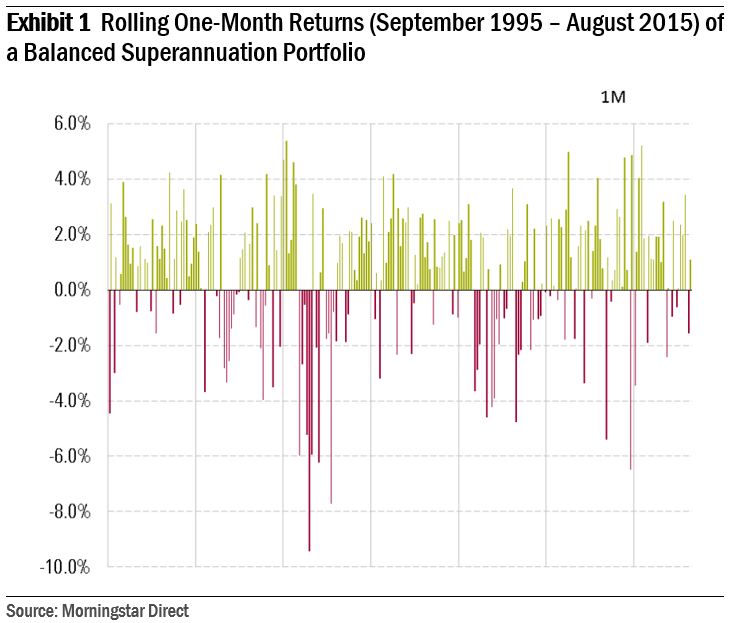
There are no clear patterns or sequence to the returns. In the short-term, even a well-diversified portfolio exhibits volatile and unstable returns.

Exhibit 2 illustrates the rolling one-year returns, so each bar includes 12 months of performance.
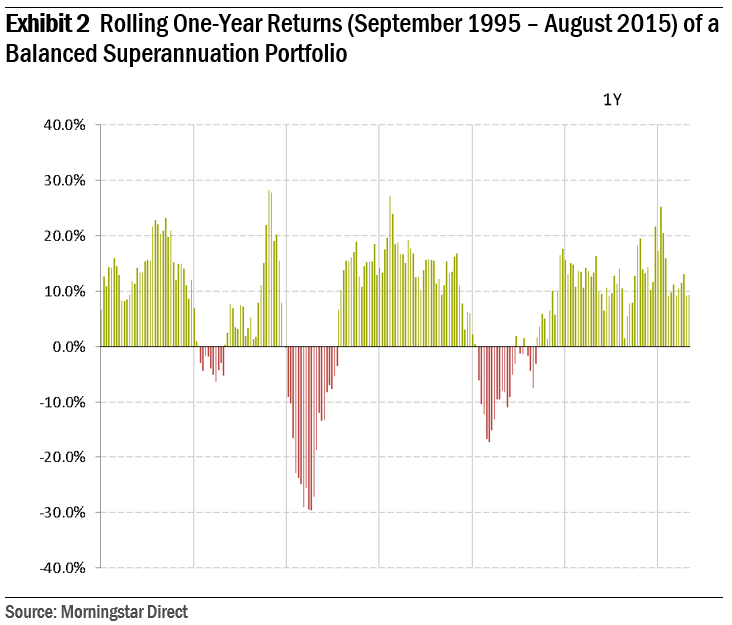
Here we observe smoother and more persistent positive returns over time, with less frequent periods of negative performance.

Exhibit 3 depicts the balanced portfolio's returns over rolling 10-year periods and each bar accounts for 10 years of performance. The benefits of long-term investing become apparent, with two important takeaways:

  • In this period, there are no periods of negative returns, which means that no matter what 10-year period an individual was invested over, the portfolio delivered positive performance. This is because the well-diversified balanced strategy recovered from any losses or periods of underperformance within each 10-year window.
  • The returns are significantly smoother and considerably less volatile compared to shorter time horizons. Investors can see past the haze of short-term market movements and focus on achieving long-term investment goals.
Peter Gee is Research Products Manager with Morningstar Australasia. Information provided is for general information only, and individuals should seek personal advice before making investment decisions. The objectives of any individual have not been considered in this article.


  •   11 December 2015
  • 8
  •      
  •   
8 Comments
Gary M
December 10, 2015

“Patience” is fine if you are happy you have bought great businesses at great prices and are not worried that maybe you haven’t; and if you have great confidence that your existing investments will definitely achieve your goals when you need to them to; and if you know for sure that you won’t panic when your passive portfolio falls 50% or more. For everybody else (99% of investors) there is little reason to be patient.

Jerome Lander
December 10, 2015

Unfortunately, this is a simplistic view of markets based on looking in the rear view mirror, and with no elucidation of what the drivers of the returns have been, and how these might have changed and be different in future.
I would hate for anyone to rely upon this sort of analysis to invest their money, as depending upon the starting point they could easily have a very disappointing result.
Would you consider the following a good investment result:
Return: 5% per annum (over 10 years)
Risk: Biggest draw down 30-40%
Most people wouldn't, and nor should they! Alas, this is the sort of result they could achieve if they started today, and didn't lose their nerve in the meantime...

Jon B
December 10, 2015

The trouble is institutionalised laziness and the insistence that tracking error is more important than negative returns. Constructing actively managed, diversified portfolios from managers that hate to lose investors money makes a monstrous difference to investor performance. All the above article proves is that there are "lies, damned lies, and statistics".

David
December 10, 2015

Why on earth would any investor be in commodity stocks, just as one example, over the last 3 years?

Brian S
December 10, 2015

There is nothing new here and for those in the superannuation accumulation phase it should be reassuring. For those of us in the pension phase with drawdowns of 5% per annum or more a "balanced" portfolio may be too agressive but there is little published material showing how our investments would perform over various time spans and with different asset allocations.

Peter Vann
December 11, 2015

Hi Brian S

1) Another way to address your desire for more research is in

http://ccfs.net.au/cvs/content/Impact_of_Investment_Risk_onRetirement_Income.pdf

In this white paper the authors** derive sustainable retirement income estimates as a function of the aggressiveness of their asset allocation for three specific cases. These calculations account for investment (and inflation) volatility (for the technical it uses a stochastic analysis not the simple but misleading deterministic analysis) .

Whilst these are only 3 specific cases, the nature of the conclusion seen on page one applies for many general cases.

2) Sure, Peter Gee's analysis is based on history, whereas in reality we all need to undertake forward looking analysis. But forward looking analysis uses history as a guide, plus current market conditions and expectations (not in the statistical sense) of future return generating parameters. Hence Peter's work provides useful insights for that forward looking process.

Peter Vann

Peter

** Chris Condon and myself.

Terry McMaster
December 12, 2015

This article shows that there can be an inverse relationship between the number of words, very low, and both the quality and quantity of information, very high.

The graphics tell the tale beautifully.

In summary, investing in shares and property is a long term exercise and if you are not prepared or able to take a long term view, ie at least ten years, then you should not invest in shares or property.

Nothing more needs to be said.

Phil Bamback
January 04, 2016

Well said Terry... even though nothing more needs to be said I felt this was needed :)


Leave a Comment:

RELATED ARTICLES

The investing rule that explains the next market crash

The new capital gains tax trap for your portfolio

One risk after another

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.