Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 462

Is the market’s recession conviction warranted?

A common refrain is that the market is forward looking. I’ve never seen it quite this forward looking. Investors are absolutely convinced that Australia is going to have a recession. And that it’s going to be a humdinger.

Look no further than Seven West Media (ASX:SWM) for your poster child. Back on 10 February 2022, its share price hit $0.80. As at 14 June, the owner of Channel 7 and The West Australian is trading at $0.38 a share, down more than 50% in four months.
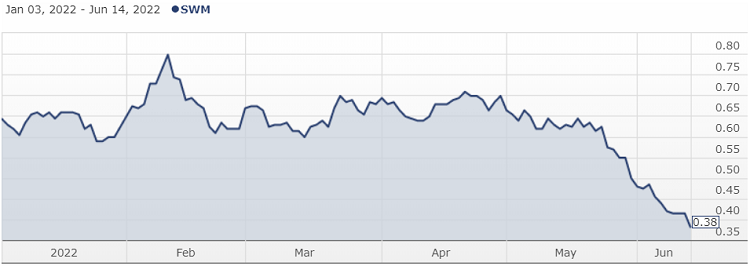

Source: Morningstar

In the interim, it announced an excellent half-year result and, just a month ago, upgraded its expectations for the full year thanks to “strength of advertising markets”. It now expects to generate earnings before interest, tax, depreciation and amortisation (EBITDA) of between $335 million and $340 million. That will translate to approximately $180 million of profit after tax for shareholders.

After the share price fall, Seven West’s market value is just $740 million, or roughly four times its likely profit for the year.

An advertising recession?

An explanation for such a lowly valuation is not difficult to find. The stock has been downgraded by two well-regarded brokers over the past month, with Morgan Stanley laying out the bear case best:

“Advertising is cyclical, and the economic outlook is softening … we believe it is entirely possible that a 6–12-month period of negative TV advertising growth lies ahead, with the magnitude of the declines more likely to be in the range of -10% to -20%.”

Due to its high fixed costs, Seven West’s earnings could halve on a 10% decline in revenue.

Is it going to be that bad?

There are three important factors in answering that question.

First, are we about to have a recession? Wide swathes of the market are trading at heavily discounted prices on the assumption that it’s coming soon. The ASX Small Industrials Index - a good barometer of the most economically sensitive companies - is now trading below where it was in 2018.

It can’t be ruled out. Interest rate rises are clearly going to bite. The Government’s stimulus needs to be unwound. But mining and agriculture are important contributors to the Australian economy and conditions have never been better. Other important sectors - tourism and hospitality in particular - are only just beginning their recoveries. There are going to be dramatic shifts in spending patterns, but it’s not clear to me that the aggregate translates to a certain decline.

Second, assuming we do enter a technical recession, will it impact advertising budgets the same way previous recessions did?

A jumbled-up economy

When Covid lockdowns first hit back in 2020, Forager’s recession playbook was immediately dusted off. Sell everything with high debt burdens. Avoid stocks exposed to discretionary spending - that’s the first thing people will cut when faced with the risk of losing their job.

The playbook was useless. Hardly anyone lost their job. Many of those who did, ended up getting paid more by the government than they received when employed. Discretionary consumer stocks like Temple and Webster and Nick Scali made more profits than ever before.

If there is another recession coming, it’s going to be another weird one. Some sectors are clearly still humming. In two important sectors for the TV advertising industry - automobiles and tourism - the recovery is only just getting started. Spending levels in those sectors are nowhere near their pre-Covid levels of spending. Harvey Norman will be selling less, but does that mean the total pie needs to shrink?

Third is the assumption that an advertising downturn hits Seven West proportionately. This, I will admit, is likely. As Morgan Stanley points out, this is still a television company. As eyeballs shift online and to streaming services, traditional television is losing market share in the battle for advertising dollars. You won’t win analyst of the year for predicting that trend will continue.

But I am having a long-priced wager that the nadir is behind us.

The value in connected television

There is a chance (it is just a chance) that internet-connected TVs change the game for traditional television companies. Traditional media companies’ own streaming services are mitigating the loss of eyeballs. That is widely understood. But few are thinking about the value of the eyeballs that remain.

A colleague of mine was watching TV via the 10Play app recently when an advertisement popped up for a new Bunnings at Pymble in Sydney’s north. He lives just around the corner, and it is highly likely that the ad was only served to people in that area.

Traditional TV’s one big downfall was that it only worked for brands with mass appeal. You had to show the same ad to every single person watching. That’s why cars, beer and supermarkets dominate the ad breaks. They still wasted a lot of money on people who don’t drive, drink or buy groceries.

The big benefit with connected TVs is that they can serve different ads to different people. Unlike the days of linear television, Channel 7 knows where its streaming viewers live and what programs they like watching. They know their email addresses and, with that, can buy plenty more information about them. Each 30-second advertising slot can then be carved up into different segments and sold to the most relevant advertisers.

We are still in the early stages of this technology’s evolution but it is growing fast and, in my opinion, is going to be an incredibly powerful advertising medium. There might be less eyeballs in aggregate, but each could be worth many multiples of its traditional value.

While all of that is specific to Seven West, the expected recession’s impact on its share price is not. Retailers like Accent and Adairs are trading at 5-8 times earnings. Small lenders like Plenti and Wisr have suffered share price falls of 45%-70% this calendar year.

I wouldn’t bet my life on a recession not happening. But I’m happy to own a few cheap options based on a scenario that isn’t as bad as everyone currently thinks.


Steve Johnson is CIO at Forager Funds, a Sydney-based boutique fund manager. This article provides general information to help you understand our investment approach. It does not consider your personal circumstances and may not be suitable for you.


  •   15 June 2022
  • 3
  •      
  •   
3 Comments
Jack
June 15, 2022

Anyone seeing the job numbers today - employment rose by 60,600 versus market expectations for a 25,000 rise, participation rose to a record high and the quality of jobs growth was very strong with a surge in full time jobs such that hours worked rose strongly again - will think a recession is a long way off. So why is the stockmarket so weak?

Greg
June 18, 2022

Could not agree more with your sentiment. No other bad news around for the press to hang their hats on. Surely job losses and housing failures have to mark the start of a recession. No signs of either.

Andrew Smith
June 15, 2022

Maybe a demographic explanation i.e. decline in oldies with baby boomers who follow using different media, not rusted onto legacy media, even if it has supposedly broadened its appeal?

Many younger and more diverse generations do not even go near legacy media anymore except for one off events, so where are the future income streams?

One would add that the legacy media groups fell into a trap of their own making by wanting, being catered to by govt. and being allowed to consolidate across FTA TV, print and radio nationally for survival; but an oligopoly that has been overtaken by technology and changing demographics?

Meanwhile in working age cohort of 15-64 the 'demographic sweet spot' was passed pre Covid due to ageing baby boomers' 'bubble' in, or transition to, retirement.

On the stock market the headline index is an indicator but for many investors individual stocks are still healthy, earning income and paying dividends, and may offer good long term value for (new) investors entering a softer market, carefully and with a long term horizon (vs. property).


Leave a Comment:

RELATED ARTICLES

The companies well placed to weather an economic storm

If I get kicked out of the value investors’ club, so be it

Australian equities: a tale of two markets

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.