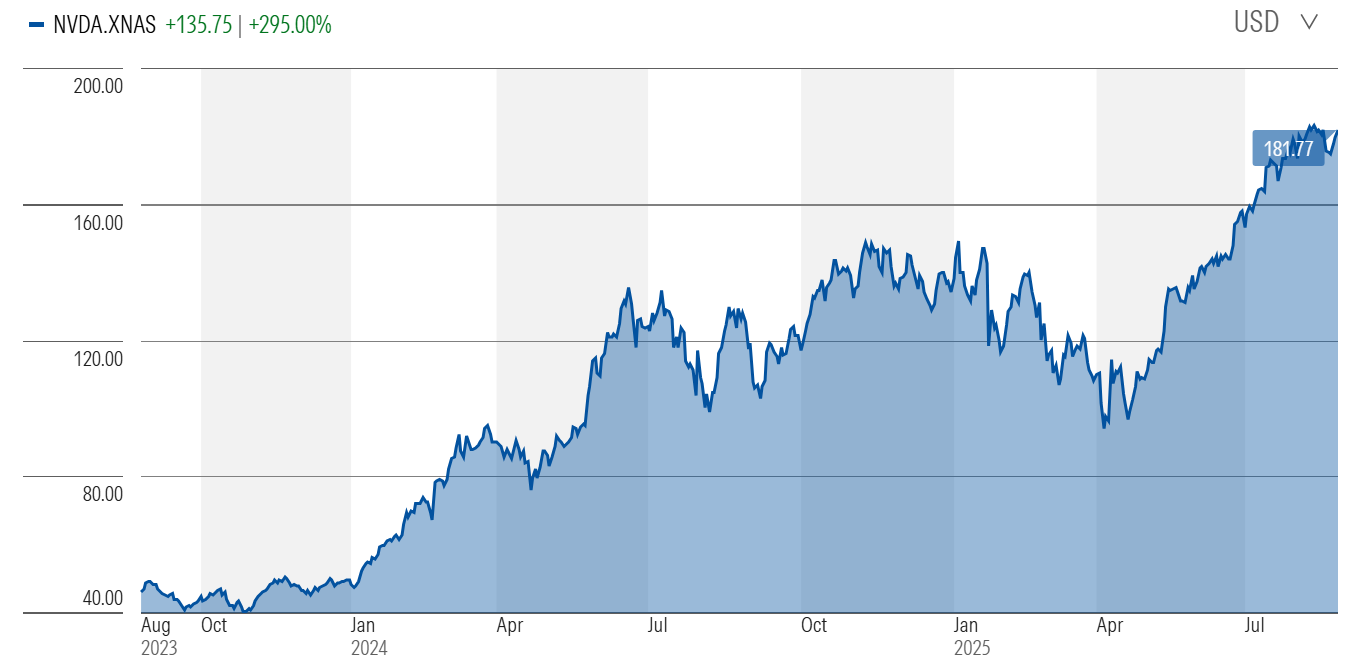
Jensen Huang, CEO and co-founder of Nvidia, has begun offloading a chunk of his personal stake in the company. He recently he sold 100,000 shares worth almost US$15 million. That’s only the start. According to SEC filings, Huang’s trading plan allows him to sell up to 6 million shares over the next 12 months, roughly US$865 million at today’s prices.
This matters more than most realise. Many Australian investors are exposed to Nvidia through ETFs with heavy weightings in the stock. Huang’s selldown may seem small (less than 1% of his total holdings) but the signal is hard to ignore. Nvidia has nearly doubled in the past three years, riding the AI wave to a US$4 trillion valuation. It remains a dominant force in tech. But when the person with the clearest insight into the company’s future starts cashing out, it’s worth asking why.
Source: Morningstar
Investors, whether holding Nvidia through ETFs or directly, shouldn’t ignore the signal. But this isn't just about Nvidia. Many local companies still have founder involvement: Corporate Travel Management, Pro Medicus, ARB, Reece, Pinnacle Investment Management, Jumbo Interactive, WiseTech, Xero, Flight Centre and Mineral Resources. Insider behaviour in these businesses deserves close attention.
The Founder Effect
Founder-led companies often command premium valuations for good reason. Founders tend to operate with greater long-term vision, faster decision-making, and stronger alignment with shareholders. Jensen Huang embodies that ethos. The company is a 30-year success story. His leadership, strategic clarity, and early bet on GPU computing created one of the most valuable companies in history. But investors shouldn’t view founders as permanent fixtures, and their incentives evolve over time. Huang is now in his 60s. This sale doesn’t signal an exit, but it does mark a shift. The myth of founders being “all in” forever starts to break once they begin monetising their ownership at scale. Optics matter. Especially when their stock price is priced for perfection.
The significance of insider sales
In the short term, executives have an innate sense of whether their stock is overpriced. While they may not know where the broader market is heading, they have real-time visibility into internal forecasts, competitive dynamics, cost pressures, and upcoming risks. When they sell, especially in meaningful portions, it usually means the stock is either fairly valued or overvalued. We’ve seen this before. We’ve seen similar founder sell-down patterns followed by lacklustre stock performance. At Corporate Travel Management, founder Jamie Pherous sold $39 million worth of shares in 2021; the stock has since traded sideways despite a broader travel rebound. Appen’s founder Chris Vonwiller and CEO sold down $58 million and $2.9 million respectively in 2020, just before the company’s share price collapsed by over 80% amid structural headwinds. And at Dicker Data, founder David Dicker offloaded $200 million in 2024, which was a precursor to him stepping down fully a year later. The share price has fallen 30% since then.
One to keep watching today is Palantir, whose CEO and Co-founder Alex Karp has sold over US$1.9 billion worth of stock (c. 20% of his holdings) over the past year while promoting the company’s AI ambitions. Even if the sell down is pre-arranged as part of a 10b5-1 trading plan (which allows for pre-arranged stock sales), insiders decide when those plans are initiated and structured; they often coincide with peak sentiment and stretched valuations. The pattern is well documented. Lakonishok and Lee (2001) found that insider selling, particularly in aggregate and during periods of elevated valuations, often precedes negative abnormal returns. Cicero, Wintoki, and Zutter (2020) extended this by showing that clustered executive sales are predictive of weaker future stock performance, especially in high-momentum names.
The contrast: When founders are buying
While Huang is selling into strength, other CEOs are increasing their exposure. JPMorgan’s Jamie Dimon made headlines by personally purchasing US$25 million in stock during a market dip in 2016 – shares are up 5x since then. In Europe, Moncler CEO Remo Ruffini reinforced his control of the luxury fashion house by partnering with LVMH, and has recently been purchasing shares on market – watch this space. Founder and executive buying is powerful not just because of the dollars involved, but because it is voluntary, rare, and often contrarian. It tells us when those closest to the business believe the market is mispricing its future. Importantly, these transactions often occur without fanfare and outside typical investor presentations. They’re a positive signal about motivation and incentives.
A practical lens
From an investment perspective, insider buying is far more actionable than selling. While there are many legitimate reasons for executives to sell stock - estate planning, diversification, liquidity - buying typically signals one thing: conviction. As investors, these signals deserve weight. Insider buying during uncertain periods can highlight mispriced opportunities, while insider selling near euphoric valuations invites a recheck of assumptions. The key is to observe who is putting capital at risk, when the sentiment is not universally bullish, and without any external obligation to do so. Strong founders create value. But watching how and when they extract value can be just as revealing. Are they buying during drawdowns? Are they participating in rights issues? Selling during rallies? Are they changing roles? These are often better signals of short-term direction than earnings guidance or investor day presentations.
Founder selling isn’t inherently bearish. Jensen Huang still owns billions in Nvidia stock and remains actively engaged. But large-scale insider selling during euphoric valuations is a signal worth considering. In a market increasingly influenced by narrative and momentum, paying attention to actions matters. Intent talks big, but action gets there first. When founders begin quietly taking risk off the table, it’s not always a call to exit. But it’s often a good time for investors to pause.
Lawrence Lam is the author of The Founder Effect (Wiley) and Managing Director of Lumenary Investment Management. He writes on leadership, markets, and the traits that define exceptional management. More at lawrencelam.org and lumenaryinvest.com. The material in this article is general information only and does not consider any individual’s investment objectives. Companies mentioned have been used for illustrative purposes only and do not represent any buy or sell recommendations.