Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 114

Risk aversion is costing women in retirement

Longevity risk is well known. Australians are getting older and living longer. Recent data released by the Australian Bureau of Statistics confirms that Australia is the latest member of the so-called ‘Longevity 4’ club of countries where the average life expectancy for both men and women is 80 years and over. The other countries are Switzerland, Japan and Iceland and they face similar challenges to Australia – how to cater for longevity risk?

This is a good problem to have with the average life expectancy for an Australian male now 80 years and 84 years for an Australian woman. However, this also brings with it the question of how to provide for an adequate retirement.

Making better investment decisions

One way to help fight longevity risk is to make smart investment choices during working life and prior to retirement. This is vital to ensure the accumulation of sufficient funds in and outside of superannuation. However it also comes down to income, savings and behavioural biases. Our latest research into Australian investors’ equity preferences in collaboration with the University of Western Australia Business School paints a picture of falling equity preferences amongst Australians, which is crucial for accumulating sufficient funds for retirement.

The research examined investors’ overall moves in and out of equity-based managed funds and switches between asset classes. While there are some increases in SMSF balances amongst younger investors and a move to investment property and global equities, the research indicates that investors aged between 35 and 49 years of age have a low preference for equities. They are at risk of not meeting retirement objectives unless changes are made. It also highlights a large difference between men and women’s overall equity preference which commenced during the GFC and has been maintained since.

Gender bias in taking equity risk

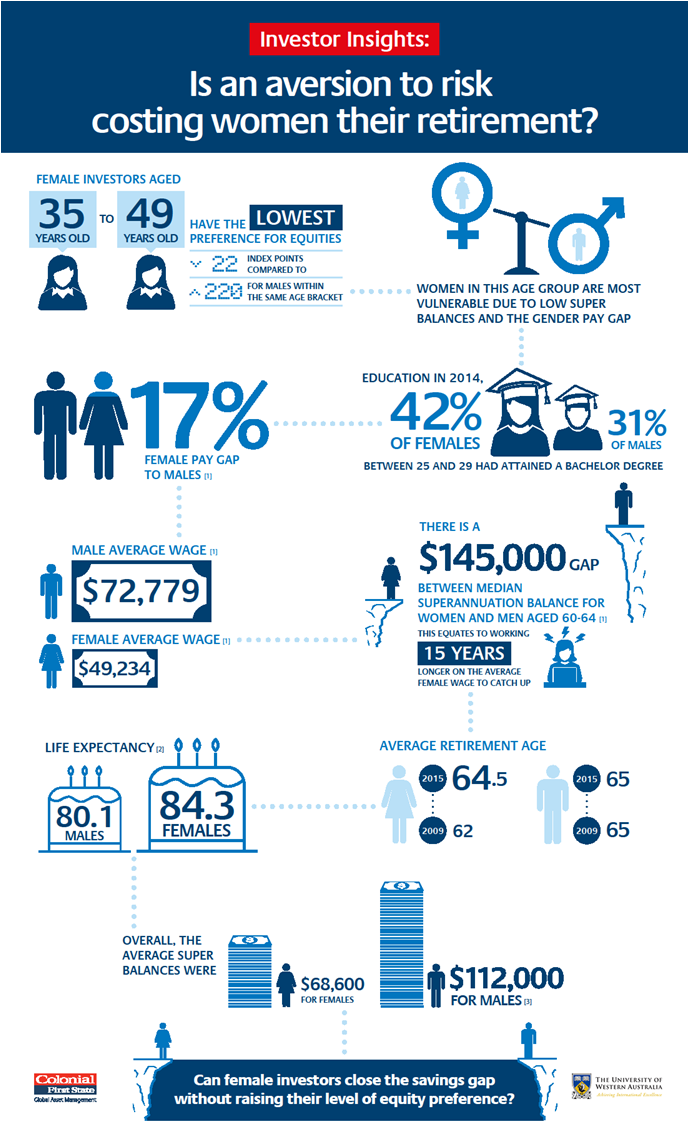
Given this lower bias to investing in growth assets, women in particular are more at risk of not meeting their retirement objectives and managing longevity risk than men. Looking at a range of facts, it is easy to see why women are more likely to outlive their retirement savings:

  • Women earn less, with the average wage for males $72,779 compared with $49,834 for women.
  • Women often have broken work patterns usually for family reasons
  • Women retire with an average super balance of $68,600 compared to $112,000 for Australian males
  • Women live far longer, on average, than men.

Combining these factors creates the perfect storm for female Australians and their ability to save and secure a good standard of living in retirement, despite younger women having higher education qualifications.
Gen-Y women catching up

According to the CFSGAM Investor Insights research, Australian Gen-X women (35-49 years old) remain most at risk of not meeting their retirement objectives. It appears that women’s attitude to equities has been negatively affected by the GFC and hasn’t recovered since despite the improved returns, low deposit rates and improved labour market conditions.

Not all is lost. Younger Australian females are showing similar risk appetites to Gen-Y males, which is a unique parallel in our research. Over the last couple of years their equity preference has risen, in line with Gen-X males.

Overall, older women do appear to be less confident in their ability to manage money, less comfortable with their financial situation and more conservative in their approaches to managing money. One approach doesn’t fit all, but as an industry, there is still a lot of work to be done to help women improve their financial literacy and confidence to invest in growth assets to meet their retirement needs and cater for their longer life expectancy.


Belinda Allen is a Senior Analyst, Economic and Market Research at Colonial First State Global Asset Management (CFSGAM).


  •   19 June 2015
  • 8
  •      
  •   
8 Comments
Bruce Gregor
June 18, 2015

Belinda

Well made points re generations in the workforce and need for equities. But return uplift can only go so far. The flaw in our superannuation system is that it does not begin with the end in mind. If it did, we would have compensation through the tax system for higher invested contribution for women because they live longer and on average only gain 25% of their working life at full time employment. Also spare a thought for first wave baby boomer women who retired after 2006 thinking they would have part age pension and now face having their retirement income cut from 2017 by up to 20%. Hard to make up form this with a shift to equities right now. If there was a genuine rethink of the end purpose of superannuation, we might give some attention to these issues rather than the flawed notion of "tax expenditures''.

Bruce

David
June 18, 2015

The necessity to achieve equal superannuation balances is open to challenge. This research does not distinguish between married / partnered women and single women. The outcome for married / partnered women needs to be considered in the context of their household structure. Even if they separate they have some claim to their partner's super

Phil Kneale
June 18, 2015

The flaw with all gender-related analysis of superannuation is the false assumption that no-one shares their superannuation with their spouse. I think the false assumption persists because it makes the analysis easier and it also allows the gender victimhood narrative to flourish (which often seems to be the purpose of such exercises). According to every such analysis I have seen, my wife is destined for destitution because of her paltry superannuation balance. However, that's not the case because the reality is that all of our financial assets are shared. I may be a bit old-fashioned but surely we aren't the only family that still works that way.

Sam Naidu
June 19, 2015

What about introducing "family concessional cap" where husband can contribute super on behalf of the wife and the contribution taxed at 15%!

Andrew Wakeling
June 19, 2015

It isn't a question of women being married or not. The issue is whether women have children in a joint venture and take the major load in managing home and family. Hopefully adults partnering for procreation will be encouraged to develop clearer and more formal contracts between them which will include provision for retirement. The standard words of the marriage service may sound good but they are no longer adequate.

Maurice Goodings
June 20, 2015

My observation from living in a retirement village is that most superannuation finishes up in the hands of women. Even up to that point, superannuation is an asset shared between husband and wife.

Liam
June 21, 2015

I nearly always recommend that the working partner use super splitting to move 50% or more of their contributions to partner raising the children. This way the carer's super does not fall behind and this helps in some way to avoid a common problem with divorces where the carer looks to keep the home while the partner walks away with the liquidity.

Women in general may be less confident with equities but when they seek advice they are excellent at taking recommendations, implementing suitable portfolios and sticking to a plan, often exceeding savings targets. So maybe more education from earlier on would go some way to address this issue.

Rosalie Degabriele
June 22, 2015

Clearly it is not sufficient for women to rely on their spouse's super - the situation requires a broad review of a number of aspects across tax and superannuation which would work to give women equality in pay rates and in the super system and make allowances for broken service. Some women may be more conservative but this is usually related to child bearing and their lower pay rates.
Given that one half of graduates are now women we cannot assume that they do not understand risk and return rather the conservatism factor is more related to social factors which men are not necessarily bound by.

I am for a look at the entirety of superannuation for women which looks at all the contributing factors and creates a fair distribution of wealth.


Leave a Comment:

RELATED ARTICLES

Retirement spending is not one-size-fits-all

Is FOMO overruling investment basics?

Addressing the gender super gap

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.