Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 156

SMSF assets will not need segregating

The Turnbull Government’s first Budget has aimed its sights squarely at the superannuation accounts of wealthier Australians, but SMSFs may be well-placed to take advantage of the proposed changes. Retirees have the ability to plan and manage their tax settings in a single vehicle.

How much income does it provide?

Changes proposed to take effect from 1 July 2017 limit the amount that can be held in the tax-free pension phase to $1.6 million. Analysis of Accurium’s database of SMSF trustees preparing for retirement suggests this will impact around a fifth of trustees over 65.

This begs the question of what level of spending in retirement is sustainable for someone with $1.6 million in savings. Around a quarter of SMSF trustees using our services have indicated a desired annual budget in retirement of over $100,000.

Our research shows that superannuation savings of $1.6 million would be sufficient to give a 65-year-old male 55% confidence of spending $100,000 p.a. without outliving his savings. This assumes an asset allocation in line with the average SMSF and average Australian life expectancies. Due to their longer life expectancy, for 65-year-old females, the confidence level drops to 47%. These calculations allow for tax and age pension entitlements.

Many retirees will think a one in two chance of outliving their savings and falling back on the age pension is too great a risk. Retirees looking for greater confidence, say reducing that risk to only a one in 20 chance, would need an annual spending level of only $65,000.
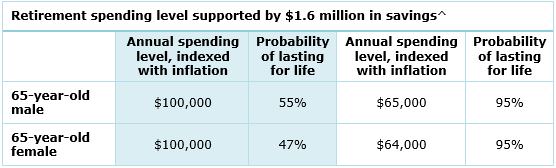
^ Using methodology in Accurium’s SMSF Retirement Insights Volume 3 – Bridging the prosperity gap.

Transfer cap is not a limit on superannuation or saving

On a practical note, the $1.6 million cap on the amount that can be used to commence a pension does not restrict the amount retirees can hold in superannuation. It is just a limit on assets that will preserve a tax-free status. The excess can continue to be held in an accumulation account with earnings taxed at a concessional rate of 15%. For most people this remains an effective and relatively simple tax-efficient structure.

Some commentators have raised concerns about the complexities such as capital gains tax impacts of complying with the cap, particularly for those already in pension phase. However, this is where the flexibility of an SMSF means there is no need to sell or transfer particular assets in order to comply with the new limit. A member of an SMSF can have both accumulation and pension accounts supported by the same unsegregated pool of assets.

SMSF trustees moving into pension phase will need to commence a pension with an amount within the cap, leaving the rest in accumulation. There is no need to identify which of the SMSF’s assets are supporting the pension. For those already in pension phase, excess amounts can be rolled back to accumulation without the assets needing to be sold or allocated specifically, provided they are accounted for appropriately. In order to continue to receive tax-fee earnings, the SMSF will need an actuarial certificate providing the split of the SMSF’s income between tax-free and taxed at 15%.

This will provide flexibility in terms of withdrawals. Retirees who have balances in excess of the cap may want to keep additional withdrawals from the pension account to a minimum. They can continue to draw on their accumulation assets in the form of lump sums if additional cashflow (above the minimum) is needed.

While the introduction of this cap will potentially limit the tax concessions, a retiree with $2 million in superannuation is likely to pay around $3,000 a year more in tax, although they will still be able to use the franking credits from the whole portfolio.

The added complexity of the proposed changes will make retirement planning more difficult, although SMSF flexibility should continue to make them a popular option. Advisers and accountants will have many opportunities to help their clients, and asset ‘location’ may become almost as important as asset allocation for many SMSF trustees and advisers alike.


Doug McBirnie and is a Senior Actuary at Accurium. This is general information only and is not intended to be financial product advice. It is based on Accurium’s understanding of the 2016-17 Federal Budget Report and current taxation laws. No warranty is given on the information provided and Accurium is not liable for any loss arising from the use of this information.


  •   19 May 2016
  • 9
  •      
  •   
9 Comments
Ashley Owen
May 19, 2016

Assumes ‘savings’ for retirement (ie the proposed cap of $1.6m) is SMSF assets and nothing else. Most of the wealth in Australia is and always has been outside SMSFs and outside super in general.

Also, I assume the confidence/probability bands apply to the investment returns and not to the longevity as well – ie when it says 55% probability of $100k withdrawals (indexed I presume) from a $1.6m fund will outlast a 65 year old – this assumes he only lives to his median life expectancy. It probably only refers to the variations in possible investment returns. But there is also a 50% chance of outliving his median life expectancy, So if you add that additional 50% likelihood of failure you get a low probability the fund will outlive his actual life.

Doug McBirnie
May 20, 2016

Hi Ashley

You raise a very good point about how longevity risk is allowed for in retirement projections. Most models we have seen in the market assume a fixed lifespan with no allowance for the (very high) probability that the retiree will live longer (or shorter) than this.

Accurium's models retirees' lifespans stochastically to allow for this risk. That is, the confidence levels quoted include the probabilities that retirees will live to a whole range of ages.

The link to our recent research paper explains the modelling in more detail if you are interested.

Regards

Doug

Peter
May 19, 2016

For married couples with a joint SMSF the $1.6m cap becomes $3.2m assuming that it is possible to transfer between the 2 accounts if 1 is greater than the other. If this is the case then what is the problem? At 5% return an annual tax free income of $160,000 should surely be enough for anyone in the pension mode.

John
May 19, 2016

Peter, for a couple you can also add another $800,000 invested outside super at 5% returning $20,000pa each, and so within the tax-free threshold.

In effect, it's $4m per couple giving $200,000pa tax free - more than enough to get by on.

SMSF Trustee
May 19, 2016

But what if one of the married couple is up to $1 million but has used up the non-concessional limit of $500k already? You can't just transfer another $600k because that person is in the same SMSF as his/her spouse. The limits are individual based, not fund based.

Alan
May 19, 2016

As SMSF Tee says this is the problem most women with broken work have not been able to accumulate deducted + earnings of the $1.1m which together with the $500k would give you the $1.6M .

Ramani
May 19, 2016

Doug deserves thanks for clearing up the many self-inflicted confusions about super after the $1.6 million tax-exempt pensions cap. Hybrid funds with both accumulation and pension phases for members have been around, with segregated or unsegregated assets, the latter requiring annual actuarial certification. This would not change under the budget.

A legal way to achieve 100% tax exemption in hybrid funds (subject to complying with the fund rules as well as the flagged $1.6 million and life-time $0.5 million NCC caps) is to commute pensions and recommence on the day a contribution is received. Alternatively, multiple income streams may be run with each contribution. In either case, accumulation balances would be zero throughout the year everything being on pensions account, and 100% of earnings would be exempt. No actuarial certificate required.

Phred
May 22, 2016

This seems to be in conflict with the comments of Kelly O'Dwyer who stated that the $1.6 would not be capped after the pension has started .

also why is an actuarial certificate needed for what is a simple apportionment calculation

Ramani
May 23, 2016

Phil, The rationale for actuarial certification derives from the complexity of asset, liability, income, expenses, provisions actual and probabilistic which may change throughout and impact each other. The aim is to sort out, by proxy if you like assets supporting pension liabilities on a weighted average basis.
If you query this, you might as well question why independent accountants must sign off accounts annually at a substantial cost. This monopoly could be outsourced to actuaries, CFAs or MBAs.
Won't happen.


Leave a Comment:

RELATED ARTICLES

Meg on the Federal Budget: what's changed with super?

The impact of our marriage breakdown on our SMSF

Franking credits lament: was it worth it?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.