Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 616

The retail property niche offering income and growth

The retail property landscape has faced a number of challenges over the past five years, from e-commerce to pandemic lockdowns, squeezed household wallets, and weak consumer sentiment. But one centre type has stood tall through it all – Neighbourhoods. These convenience-oriented centres are the cornerstones of local communities and offer a compelling investment proposition underpinned by several advantageous characteristics.

Income security

Neighbourhood shopping centres are supermarket-based and heavily weighted to blue chip tenants such as Woolworths, Coles and Aldi. These brands are strong, providing exceptional credit quality and security of income. Their leases are also long, typically 20 years with multiple options to extend, further reducing the variability of income received.

Demand stability

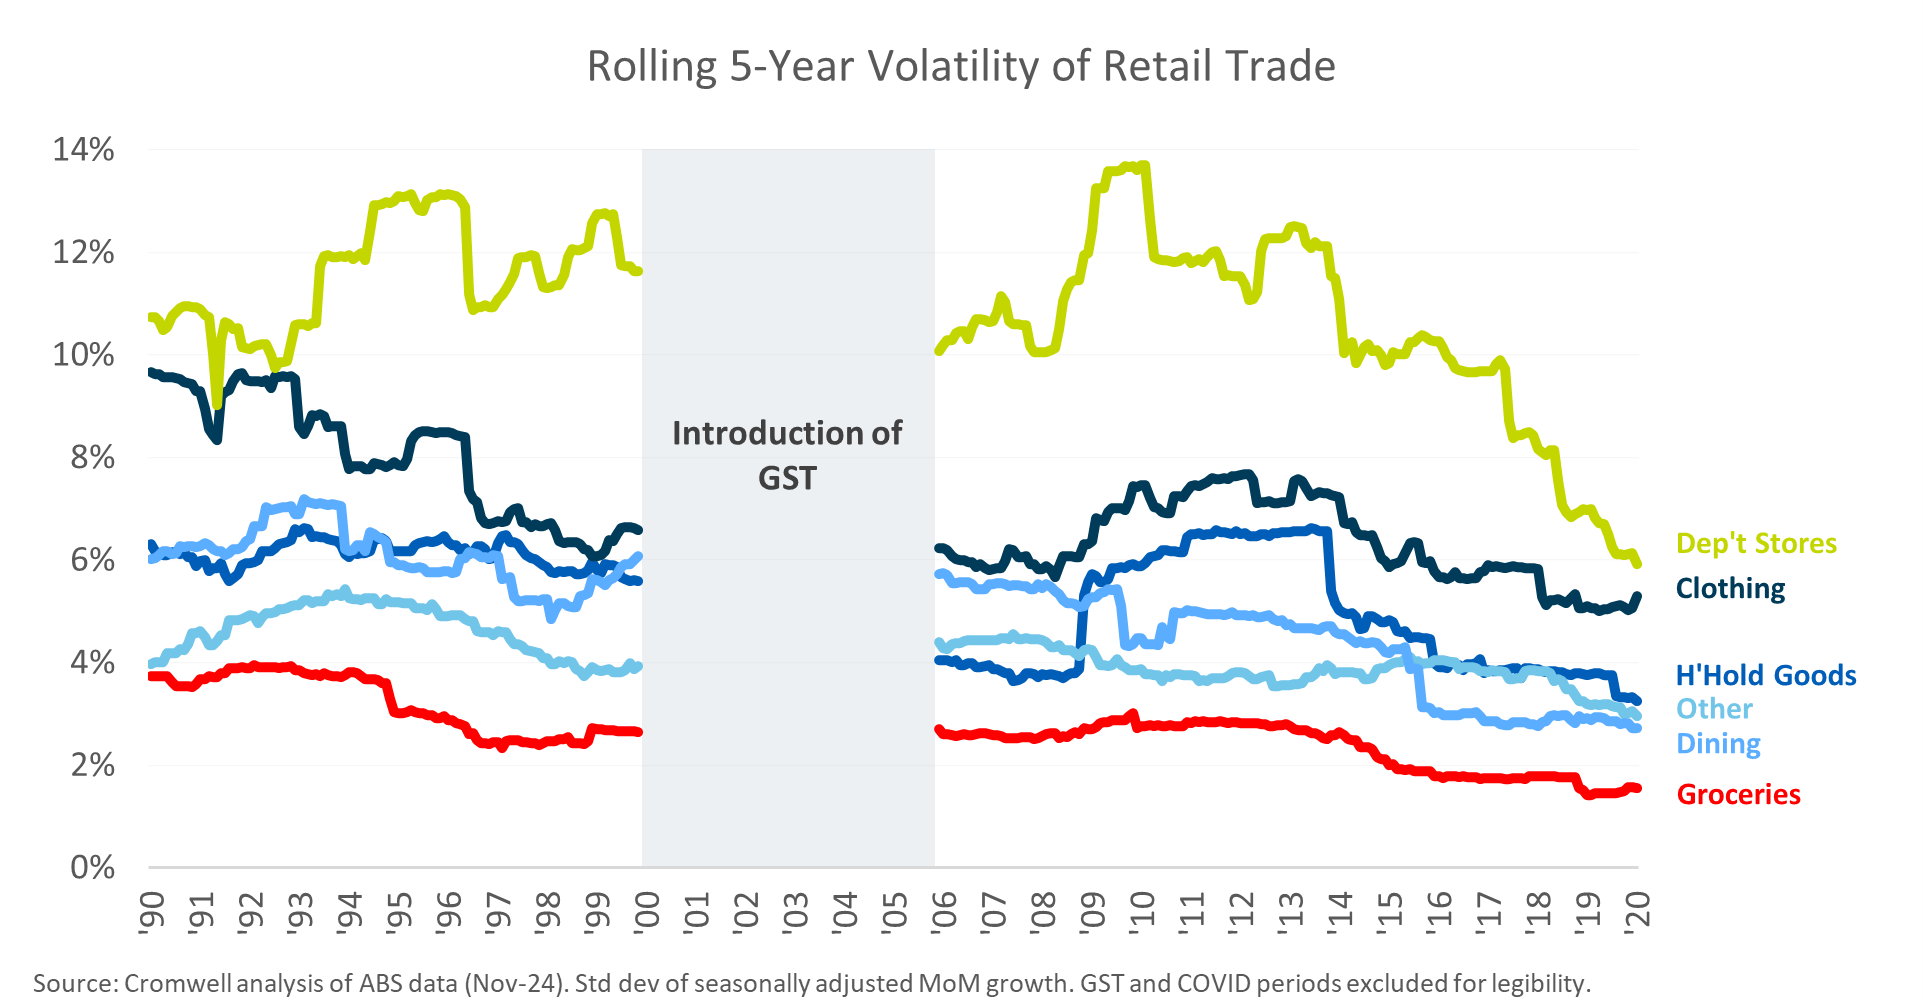
A selection of specialty tenants complements the grocery offer. These smaller shops often span essential categories such as food, services and healthcare, rather than non-essential items such as fashion. This tenant mix means Neighbourhoods are largely focused on meeting basic, long-term human needs rather than fleeting style or brand preferences. As a result, these assets benefit from steady demand and foot traffic, regardless of the business cycle or economic conditions, evident in the lower volatility of grocery sales.
Growth tailwinds

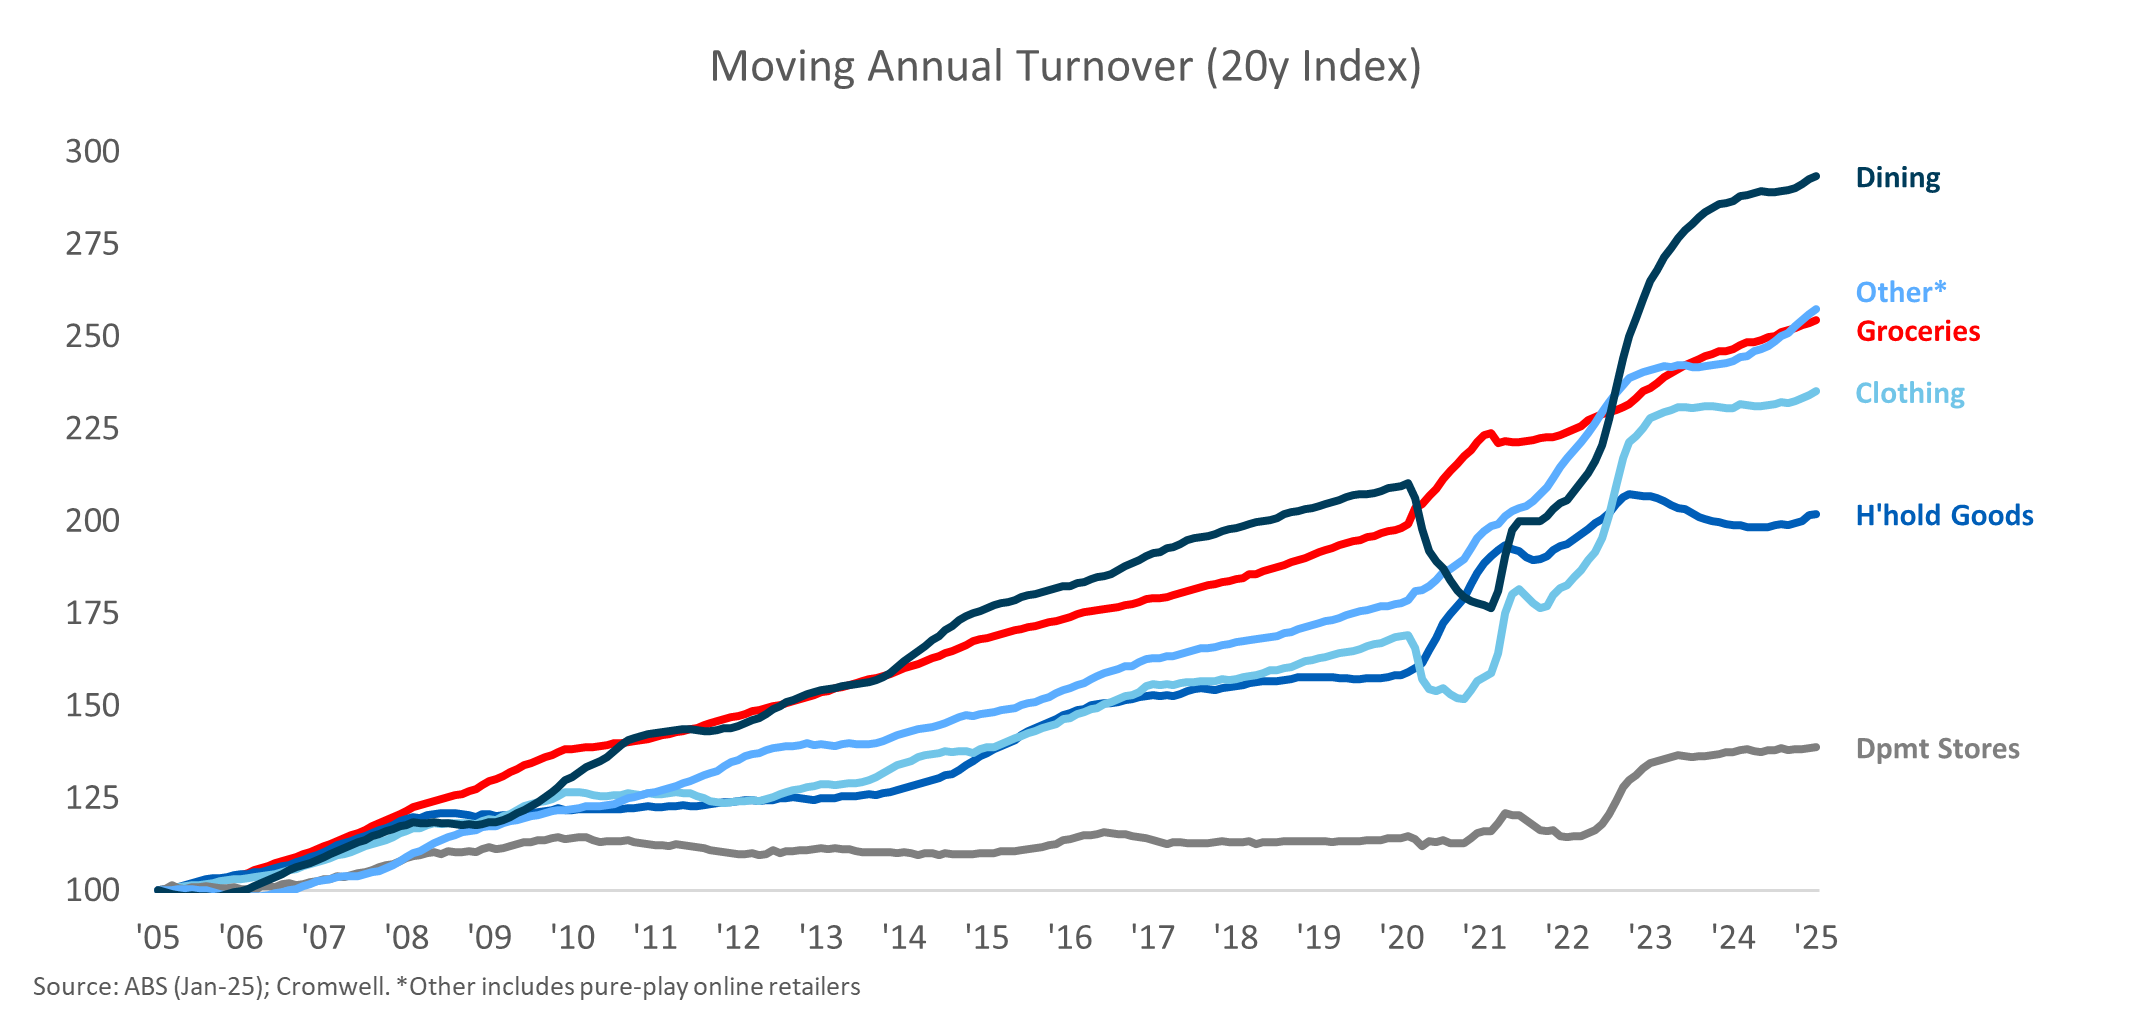
Positively, the lower volatility of grocery spending doesn’t come at the expense of growth. The category has recorded growth of 4.9% p.a. over the last 20 years, behind only Dining and Other (which includes online-only retailers) [1]. One of the factors underpinning headline grocery trading performance is inflation. Since groceries are essential and demand is inelastic, price increases can be more readily passed on to consumers compared to non-essential items. Deflationary effects from technology advancement or cheaper offshore sourcing also apply to a lesser extent than in the case of categories such as electronics or clothing. Stronger headline sales growth supports sustainable rent increases, which escalate on a nominal basis.
E-commerce resilience

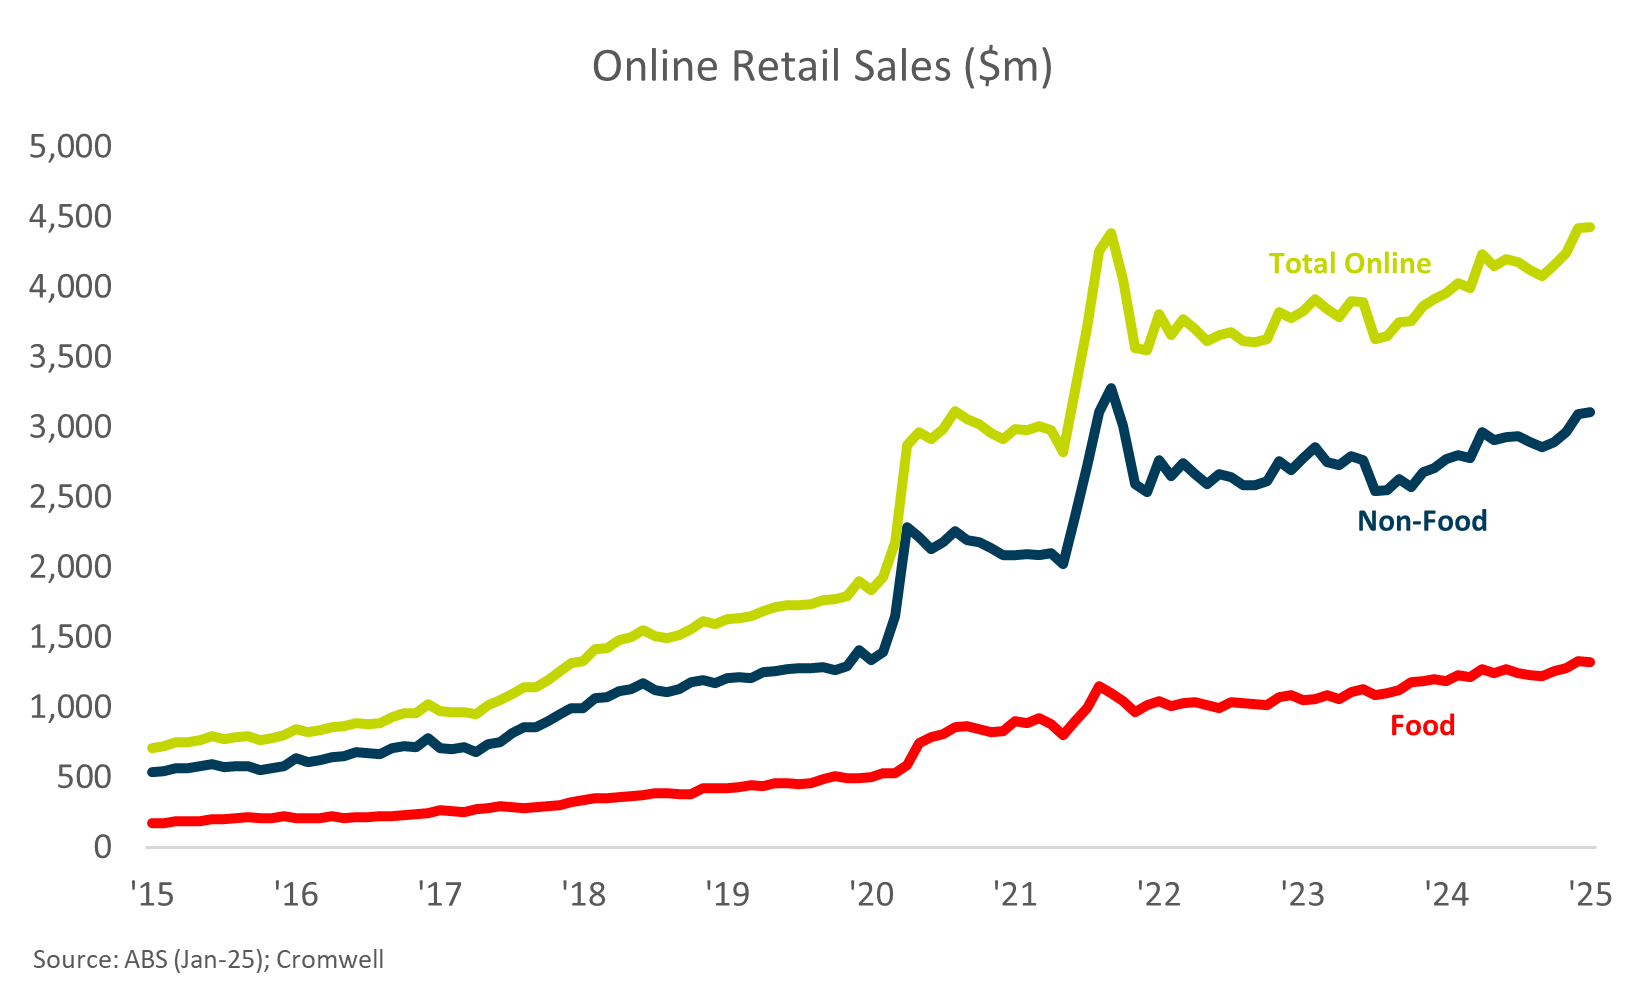
Growth through physical stores, rather than online, is most relevant for the performance of shopping centres. Over the last ten years, for every extra dollar spent on food (like groceries and dining), 16 cents went to online purchases. Meanwhile, non-food items lost 43 cents to online sales [1]. In this regard, Neighbourhood centres have a favourable retail mix which is heavily weighted to food spending through supermarket and specialty grocery exposure. They also have a healthy weighting to categories which consumers must shop in-person, such as personal services (e.g. hairdressing). We also believe the shopping experience small local centres provide, underpinned by convenient carparking and wayfinding, further defends against loss of market share to e-commerce.
Bigger investment universe

Larger forms of retail investment, such as Regional shopping centres, can only be sustained in catchments with sizable populations (i.e. major metropolitan hubs). In contrast, Neighbourhood centres are found in cities and towns all across the country. This provides investors with a less constrained and more diverse investment universe which is around 30 times bigger (by number of assets). It allows exposure to a wider range of regions/catchments and their associated drivers of economic performance.

Investment liquidity

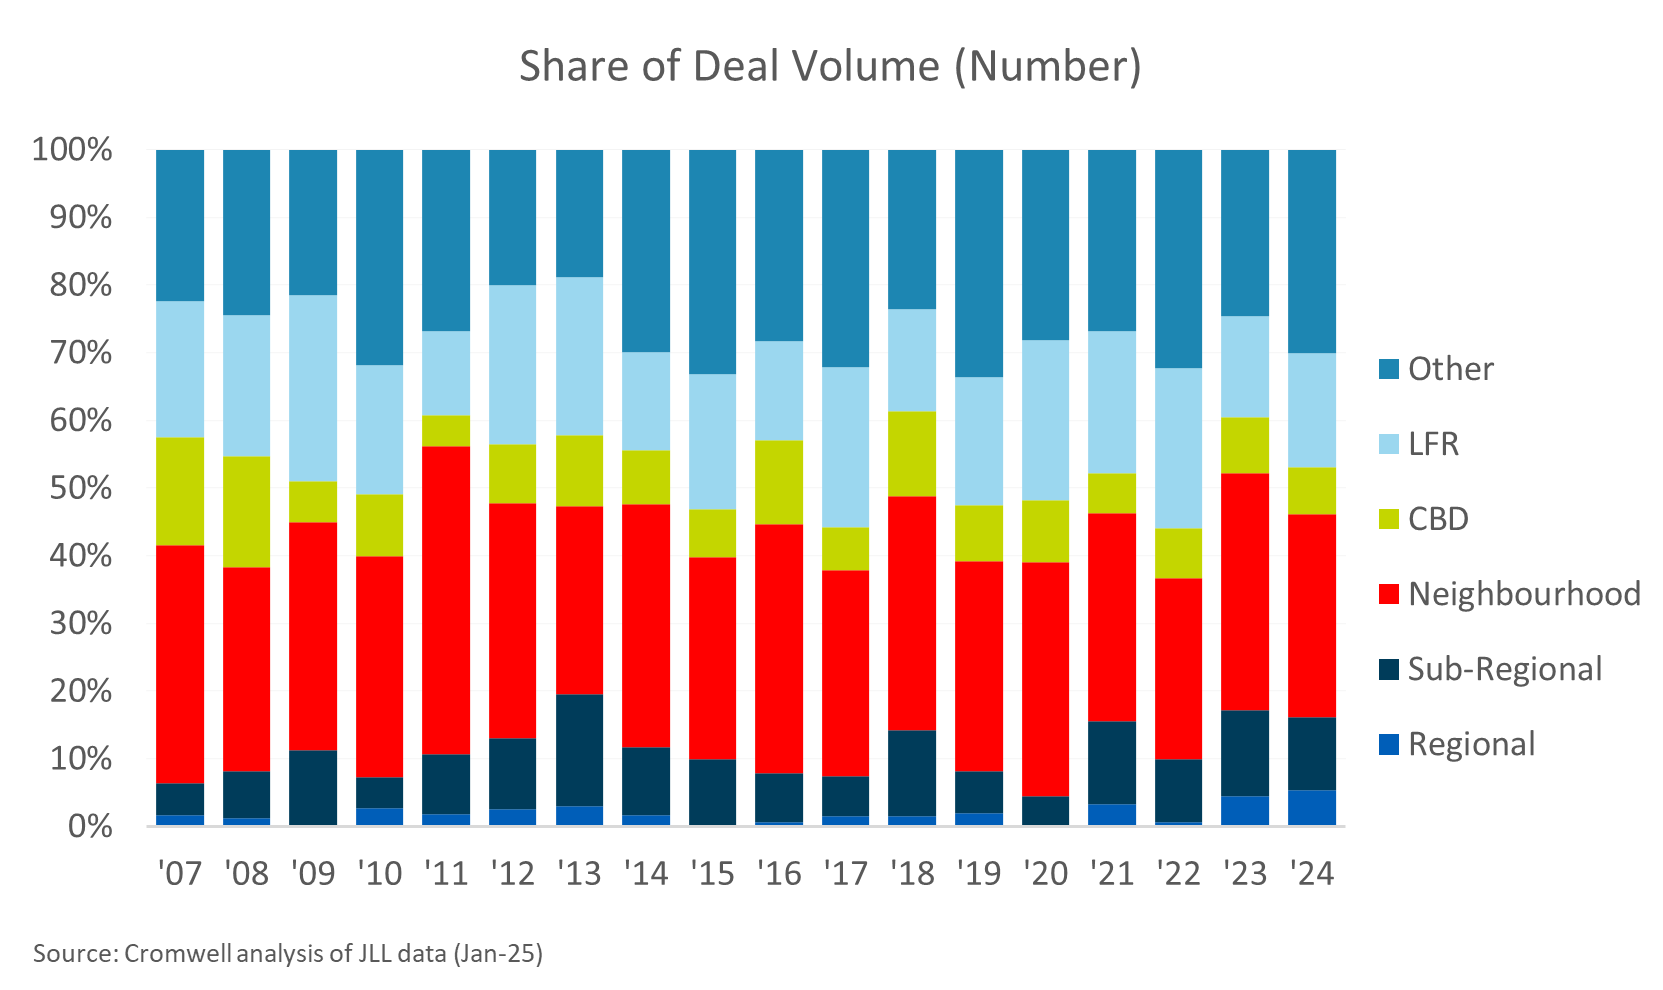
The Neighbourhood investment market is broader than other retail centre types, offering increased liquidity and supporting a competitive bidding process (and outcome) regardless of position within the economic or real estate cycle. Over the last decade, an average of 51 Neighbourhood centres transacted each year compared to 15 Sub-Regionals and four Regionals. Trading was most constrained in 2020, at the height of the pandemic. In that year, there was still 38 Neighbourhoods sold, while only five Sub-Regionals and no Regionals changed hands.
Fragmented sector

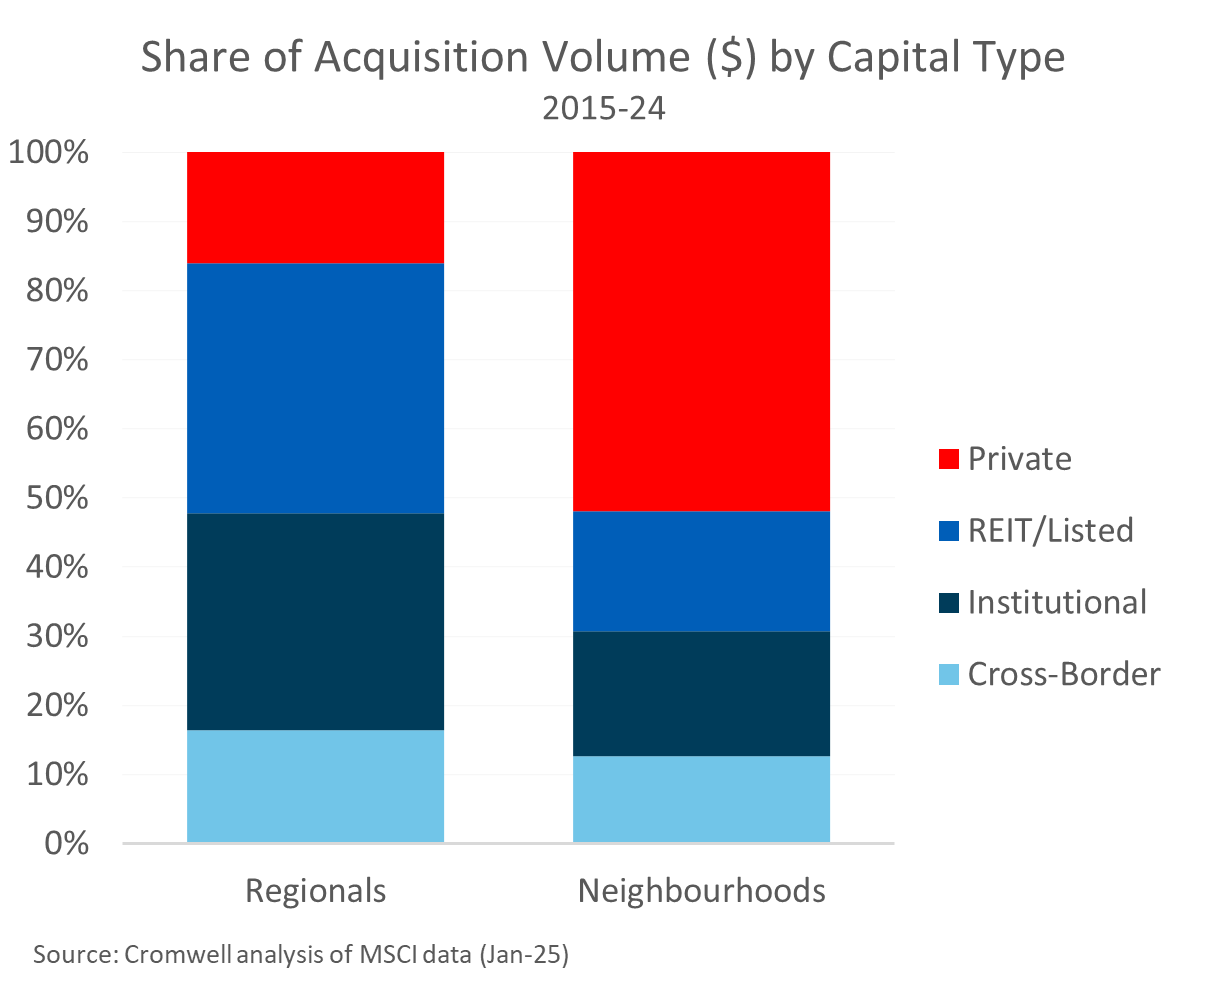
Ownership of Neighbourhoods is more fragmented than other retail centre types. While Regional shopping centres are typically owned by a small number of institutional investors, private investors are the dominant holders of Neighbourhoods. These private investors have different skills, goals, and priorities, which can affect how well the centres are maintained and managed. In our opinion, this presents opportunities for experienced managers to “add value” to assets through capital projects, leasing and operations, and increases the likelihood that an asset can be acquired and sold at favourable pricing.
Bringing home the bacon

Retail conditions are expected to improve over 2025, with consumer sentiment becoming more optimistic and real disposable household incomes increasing as inflation moderates and rate cuts materialise. Stronger retail conditions are a positive for Neighbourhoods, but these shopping centres will also benefit from their unique characteristics and advantages. The combination of strong, long-term leases to blue-chip tenants, consistent bricks and mortar demand for essential goods and services, and resilience to changing economic and capital market conditions has positioned Neighbourhood centres as a robust and attractive asset class.


[1] Cromwell analysis of ABS data (Jan-25)


Colin Mackay is a Research and Investment Strategy Manager for Cromwell Property Group. Cromwell Funds Management is a sponsor of Firstlinks. This article is not intended to provide investment or financial advice or to act as any sort of offer or disclosure document. It has been prepared without taking into account any investor’s objectives, financial situation or needs. Any potential investor should make their own independent enquiries, and talk to their professional advisers, before making investment decisions.

For more articles and papers from Cromwell, please click here.


  •   18 June 2025
  • 3
  •      
  •   
3 Comments
Johns
June 19, 2025

In my local area I can see examples of where these "long term leases to blue chip companies" have been anything but a good investment. Rather they were an "exit" strategy for these blue chip companies out of property ownership as their business model was about to change.

Consider one shop front in the main street. They sold the property with a lease back - 10 plus 10 I seem to recall, with very good return on the sale price. During the first 10 year term, they vacated the building, but the blue chip tenant (as you would expect) paid their rent when due for the full 10 year term. Then stopped paying rent (as they were entitled to under the lease). But the landlord was now faced with a specialised building, that was extremely difficult to rent to another tenant (it has been vacant for 4 years now).

Hardly a good investment. I suppose there is a lesson to be learnt here. And it is hardly an isolated instance. I can see about 4 similar former business nearby, and one a kilometer up the road that are now leased on substantially less rent than the "buy and lease back" deal at the start of the arrangement.

Alex
June 20, 2025

Johns, your anecdote about a single "main street" tenancy isn't relevant. I would agree with you that main street retail can be challenging, but that's not the topic of the article. Colin is referring to neighbourhood shopping centres, which are relatively small centres anchored by a supermarket and often have a small number of convenience-based tenancies (think butcher, cafe, barber, pharmacy, bakery, nail salon, etc). In metro areas, there is typically less risk of having these smaller tenancies remain vacant

Peter Joseph Cryan
June 26, 2025

What are some shares that would be regarded as neighbourhood shares


Leave a Comment:

RELATED ARTICLES

A retail property niche offers a lot more upside

Commercial property prospects are looking up

Lessons from Australia’s largest property busts

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.