Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 190

Trust alternatives after 1 July super changes

Given the impending superannuation changes, it's worth taking a fresh look at estate and superannuation succession planning arrangements.

Background

From 1 July 2017, individuals will be able to have a maximum of $1.6 million in the tax-free pension stage of superannuation. Amounts surplus to the $1.6 million need to either be rolled back to the accumulation stage of superannuation (tax rate of 15% applies to income and 10% to capital gains) or withdrawn from superannuation where earnings may be taxed at personal marginal tax rates.

To illustrate the changes and new opportunities, consider the following example:


  • High net worth retired couple, Simon and Danielle, both age 65 with an SMSF total balance of $3.5 million ($1.6 million for Simon and $1.9 million for Danielle). The SMSF is entirely in pension phase so no tax applies.


  • Simon also has an investment portfolio valued at $2 million outside super.


  • Simon passes away in June 2017.


  • They have two minors as grandchildren who do not have any other income.


  • SMSF succession arrangements are such that Danielle can take Simon’s balance as a reversionary pension, lump-sum payment directed to the estate or Danielle, or a combination of the above (the precise mechanics of this will be discussed in another article).


  • For simplicity, assume an earnings rate of 5% (all income, no franking credits) on investments regardless of entity holding assets.


Pre-1 July 2017 consequences

a) Before Simon’s death

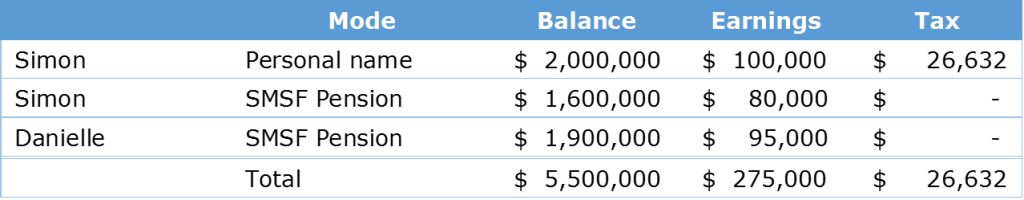
In a pre-1 July 2017 world, there is no tax on earnings within the SMSF as it is all in pension stage. Simon pays tax at his marginal rate on his $2 million personal investment portfolio.
b) After Simon’s death

Danielle continues Simon’s pension as reversionary and inherits the $2 million personal portfolio directly. The tax position is the same as when Simon was alive.

Post-1 July 2017 consequences after Simon’s death

Option 1 - Super roll back

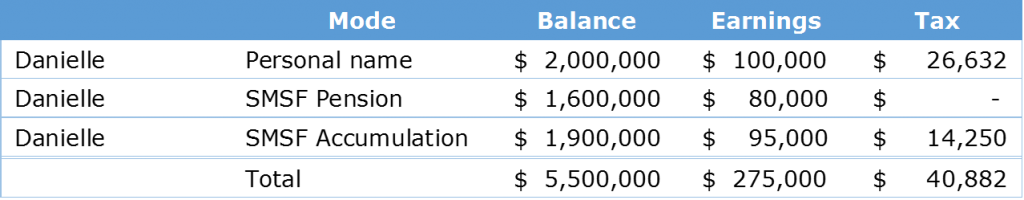
Danielle can hold a maximum of $1.6 million in the pension phase. In this example, we assume that the balance above this amount is rolled back to the accumulation stage. Danielle inherits the $2 million share portfolio and pays tax at her marginal rate.
Option 2 - Withdraw excess from superannuation

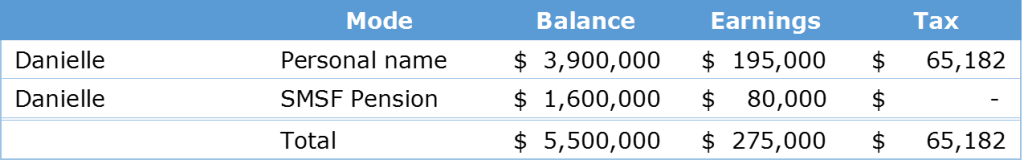
As a superannuation tax dependant, Danielle is paid a tax-free lump sum death benefit of $1.6 million of Simon’s benefit, withdraws $300,000 of her benefit, and retains a total of $1.6 million in pension stage. The funds withdrawn from the SMSF are invested in Danielle’s name alongside the inherited $2 million portfolio and taxed at her marginal rate.
Option 3 - Super roll-back and share portfolio directed to a testamentary trust

[Note: A testamentary trust is a trust which arises upon the death of the testator, and which is specified in his or her will].

This strategy is a combination of the above two with a twist!


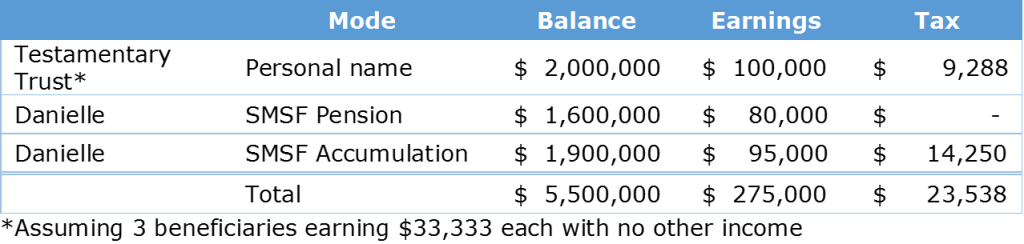
  • $1.6 million stays in pension stage


  • The excess over $1.6 million in the SMSF is rolled back to accumulation stage


  • The $2 million investment portfolio is directed to a testamentary trust with flexibility to distribute income to Danielle and potentially two minor grandchildren who have no other income.
 

Conclusion

In a pre-1 July 2017 world, it was often best to continue a reversionary pension to the surviving spouse given that all earnings would continue to be 100% tax-free. In these circumstances, testamentary trusts may have had limited appeal.

However, from 1 July 2017, given that high superannuation balances will be excluded from the zero-tax pension environment, an individual’s overall tax position may be optimised by using testamentary trusts for estate assets. This, when combined with careful superannuation succession planning, can lead to significantly better outcomes.


Reuben Zelwer is the Principal of Adapt Wealth Management Pty Ltd. Reuben is a CERTIFIED FINANCIAL PLANNER® practitioner and an SMSF Specialist Advisor™. This article is for education purposes and does not consider the circumstances of any person, and is based on an understanding of the legislation at the time of writing.

  •   16 February 2017
  • 10
  •      
  •   
10 Comments
Randall
February 16, 2017

Thanks for a good article Ruben on something I have been pondering over quite a bit. One question please which is what is basis that Simon's super can remain in super on his death? Since Danielle is over the $1.6m limit I would have expected that once the 12 months period of grace has expired after Simon's death, all of his super would have to be taken out.

Phil Brady
February 16, 2017

I think that's covered in option 1 post July 17 scenario

Reuben
February 16, 2017

Simons super of $1.6mn reverts to Danielle as a recessionary pension. Danielle is then able to roll her $1.9 million benefit back to the accumulation phase. But you are quite right that If Simon had say $1.9 million in super, then Danielle could only take $1.6 as a reversionary pension and the extra $300k would need to come out as a death benefit lump sum

Graham
February 16, 2017

Interesting article - as both Simon & Danielle would qualify for the Seniors & Pensioners Tax Offset (SAPTO) I would expect their personal tax liability to be significantly less than that shown in the article.

Randall
February 16, 2017

Thanks for the response Reuben. So here perhaps a good solution with your twist is for Simon to have 4 young grandkids who each draw down via the trust $20,542 each year which would ensure the tax free status for a few more years yet. More seriously, the changes do mean that couples each with more than $1.6m in super have to review their BDNs and wills if they want to minimise taxes and/or also use avenues such as Testamentary trusts for the benefit of any grandkids.

Reuben Zelwer
February 16, 2017

Yes Randall. I'm not necessarily a big fan of BDBNs unless the situation specifically warrants it. I think maximum flexibility in the new super world is best.

peter matters
February 17, 2017

Now I am confused. I read that the deceased spouse pension account could not be rolled back to the surviving spouse accumulation account, and had to be paid out of the super fund. This was the reason I started looking at a testamentary trust.

Reuben Zelwer
February 17, 2017

Peter, we are not rolling back Simon's pension account to superannuation. Simon's $1.6mn is continuing as a reversionary pension to Danielle. Danielle (Survivor) is the one who is able to rollover her pension balance ($1.9 million) back to accumulation stage - or withdraw it. In hindsight, I should have made this clearer

Rahul Singh
February 17, 2017

Nice article Reuben and some nice strategical considerations.

With the removal of the less than 10% test, further strategy considerations can be entertained if Danielle is aged somewhere between 65-75 and meets the work test to enable superannuation contributions.

If she meets the work rest, this enables a deductible contribution of up to $25,000 (or whatever the concessional contribution cap is at the time) thus providing an opportunity to save tax on taxable income. Bearing in mind, SG, if she receives any, eats into her concessional contributions cap.

Of course if she is under 65, then no work test required.

Andrew Ledingham
February 18, 2017

Great strategy!


Leave a Comment:

RELATED ARTICLES

Meg on SMSFs: What do we think about reversionary pensions these days?

How to prevent excessive superannuation balances

When the $1.6m cap is no longer relevant

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.