Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 628

5 charts every retiree must see…

Retirement should be a time to relax and reward yourself after decades of hard work. Yet, for many Australians, our golden years are filled with confusion, uncertainty, and a fear of running out of money. With 700 Australians retiring every day, and over 255,000 a year, it is crucial we provide older Australians with the tools and insight needed to confidently navigate this new stage of life.

Here's five charts every Australian needs to see when thinking about retirement.

1. Understand your retirement goals

For many retirees there are competing priorities and only a finite amount of money. Nobody has a crystal ball for the future and shifting from a regular pay cheque to a lump sum super balance can be a hard transition.

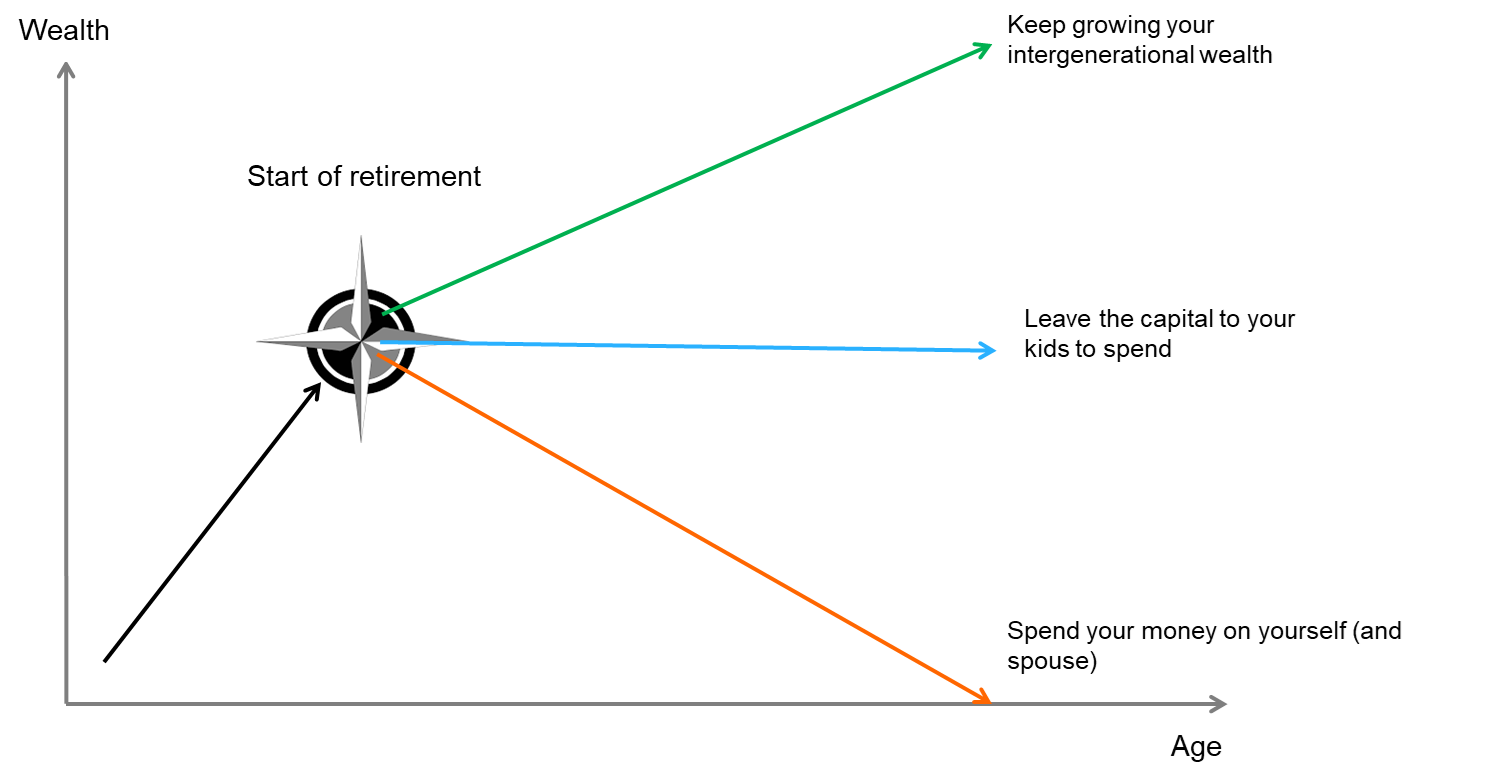
One of the most important considerations is how much to spend on your lifestyle verses leaving an inheritance for your loved ones. Understanding this overarching goal can help you plan for other expenses over time.

While the goal for super is to help fund a comfortable retirement, some retirees may want to leave a nest egg for future generations. To manage these individual goals, it can be worth considering separate investments. For example, investing in a guaranteed retirement income solution, can help you confidently spend on lifestyle expenses throughout retirement while a separate investment can focus on the inheritance for the next generation.

Chart 1: Retirement goals lead to different consumption paths
Source: Challenger Ltd 

2. Understand longevity challenges

Australians are living longer, and the average Australian will spend 20 to 30 years in retirement. Yet, none of us know exactly how long our retirement will last. This gives rise to longevity risk.

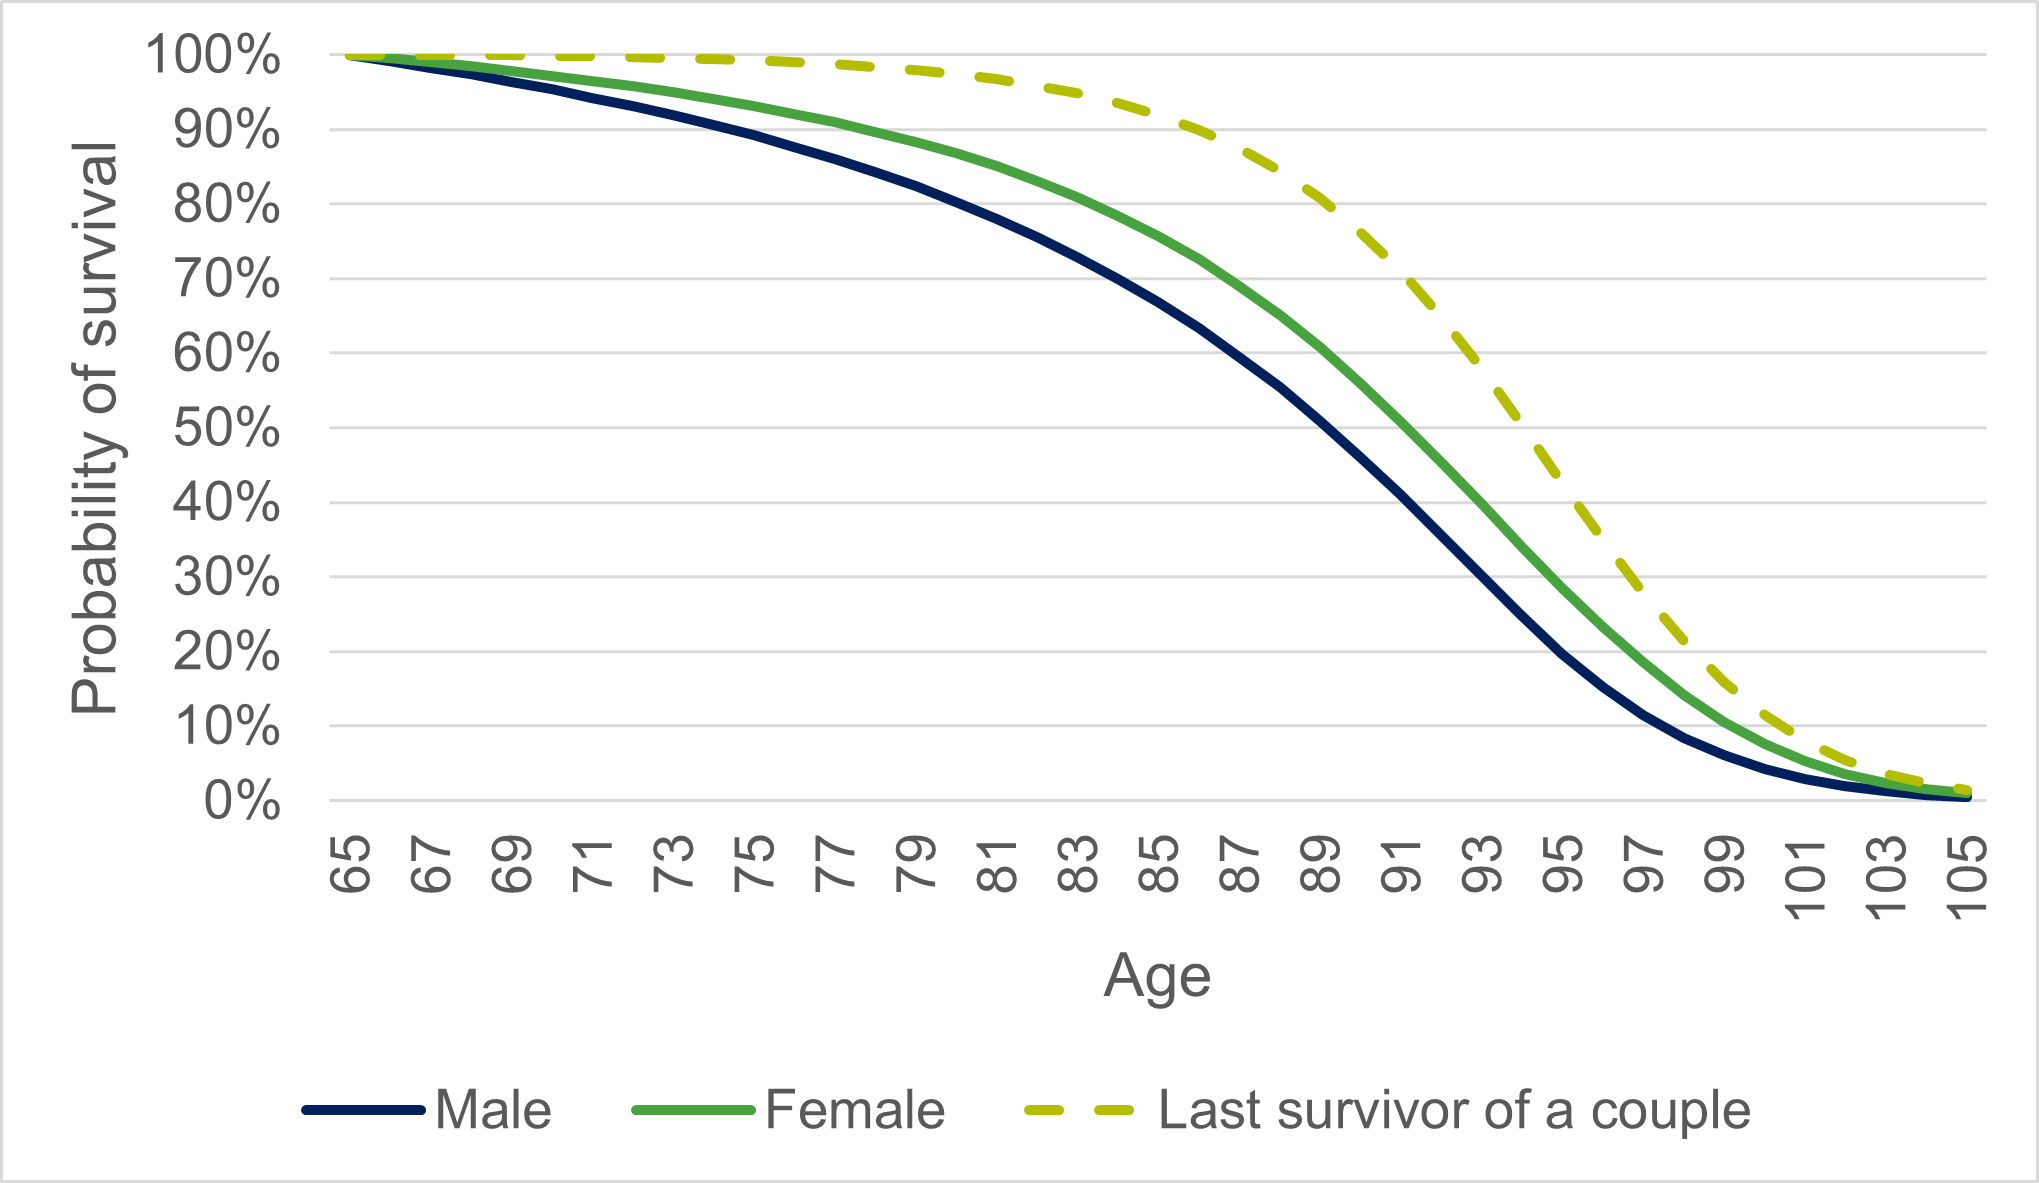
The chart below plots the probability of survival for a 65-year-old in 2025. The solid lines represent the proportion of 65-year-olds that will survive to each age, while the dotted line provides an estimate for the surviving member of a couple.

It is important to have financial mechanisms in place to ensure your income will last, particularly for women who generally live longer. This can help alleviate a lot of anxiety in our older years.

Chart 2: Probability of survival for a 65-year-old
Source: Based on Australian Life tables 2020-22 with mortality improvements from AGA for 25-year factors.

3. Understand the impact of inflation

Rising cost-of-living can be problematic for retirees. Research by YouGov, commissioned by Challenger, found that 2 in 3 Australians over 60 said cost-of-living impacted their confidence they would have enough money for retirement.

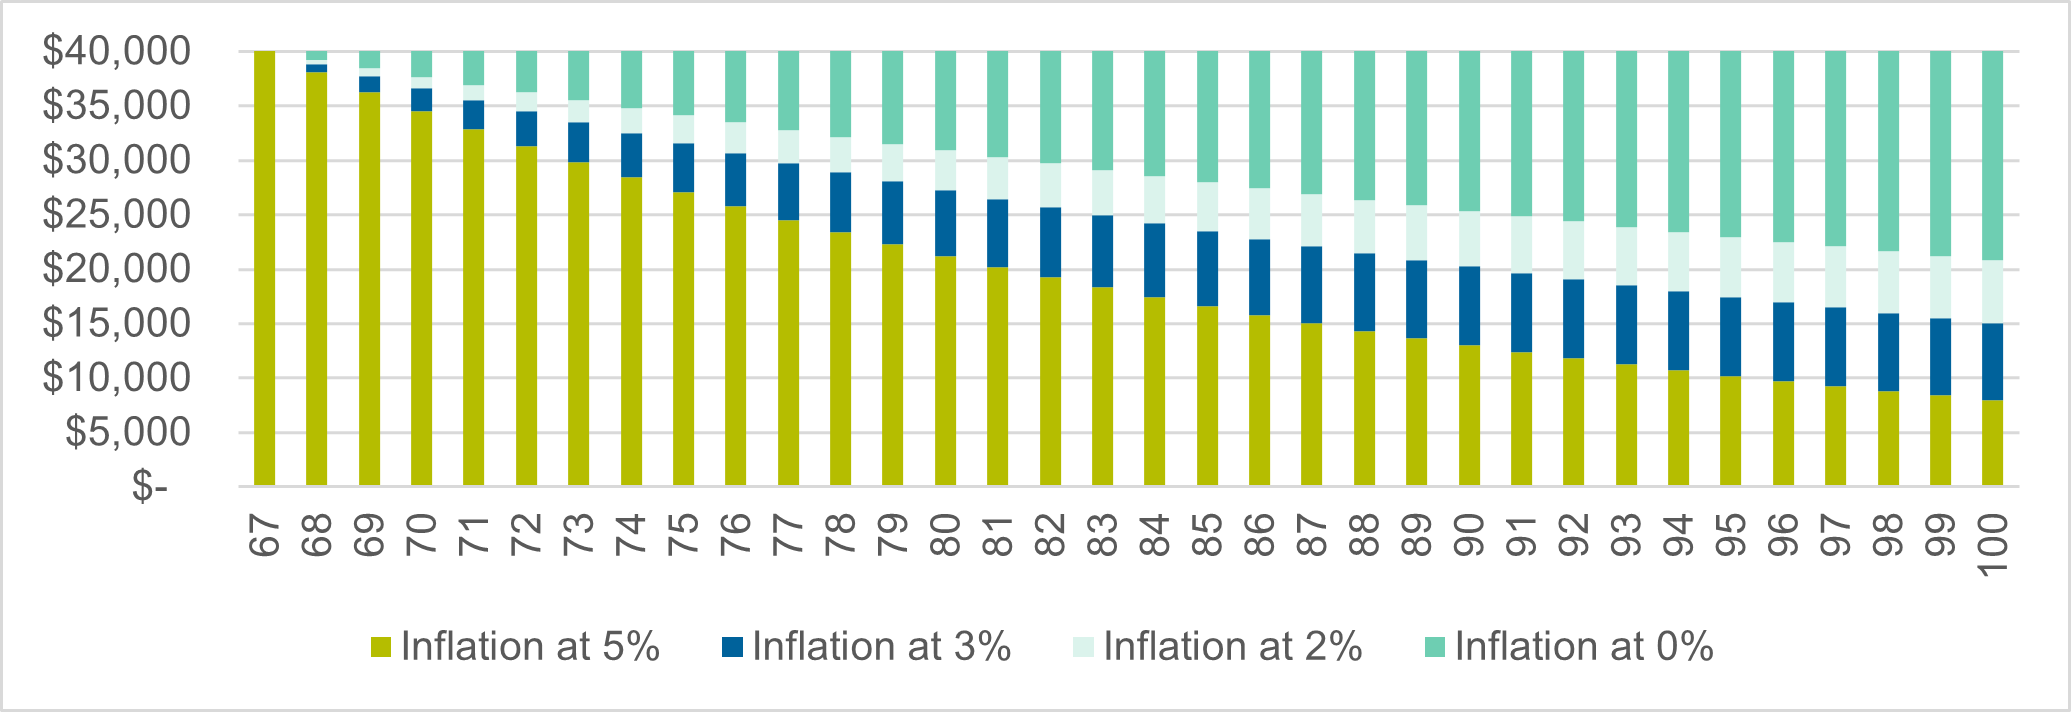
The below chart highlights how a retiree’s lifestyle can be diminished due to the impact of ongoing inflation. A spike in inflation, like we saw in 2023, can also wreak havoc, and retirees need to ensure they have some protection in place. A CPI-linked income stream can help overcome cost-of-living concerns.

Chart 3: Inflation erodes the value of your income over time
Source: Challenger Ltd

4. Understand market risk in retirement (AKA sequencing risk)

A commonly held perception is that the best way to account for inflation and make money last in retirement is through maintaining exposure to equity markets. While, historically, markets have delivered over the long-term and proven valuable in accumulating wealth, it is a different story in and approaching retirement. The impact of poor market performance is not just the length of time it takes to recover the real capital value, but the income that is lost over that period.

The order of investment returns matters in retirement as you are drawing an income from investments. In many cases, the path of returns is more important than the rate of return.

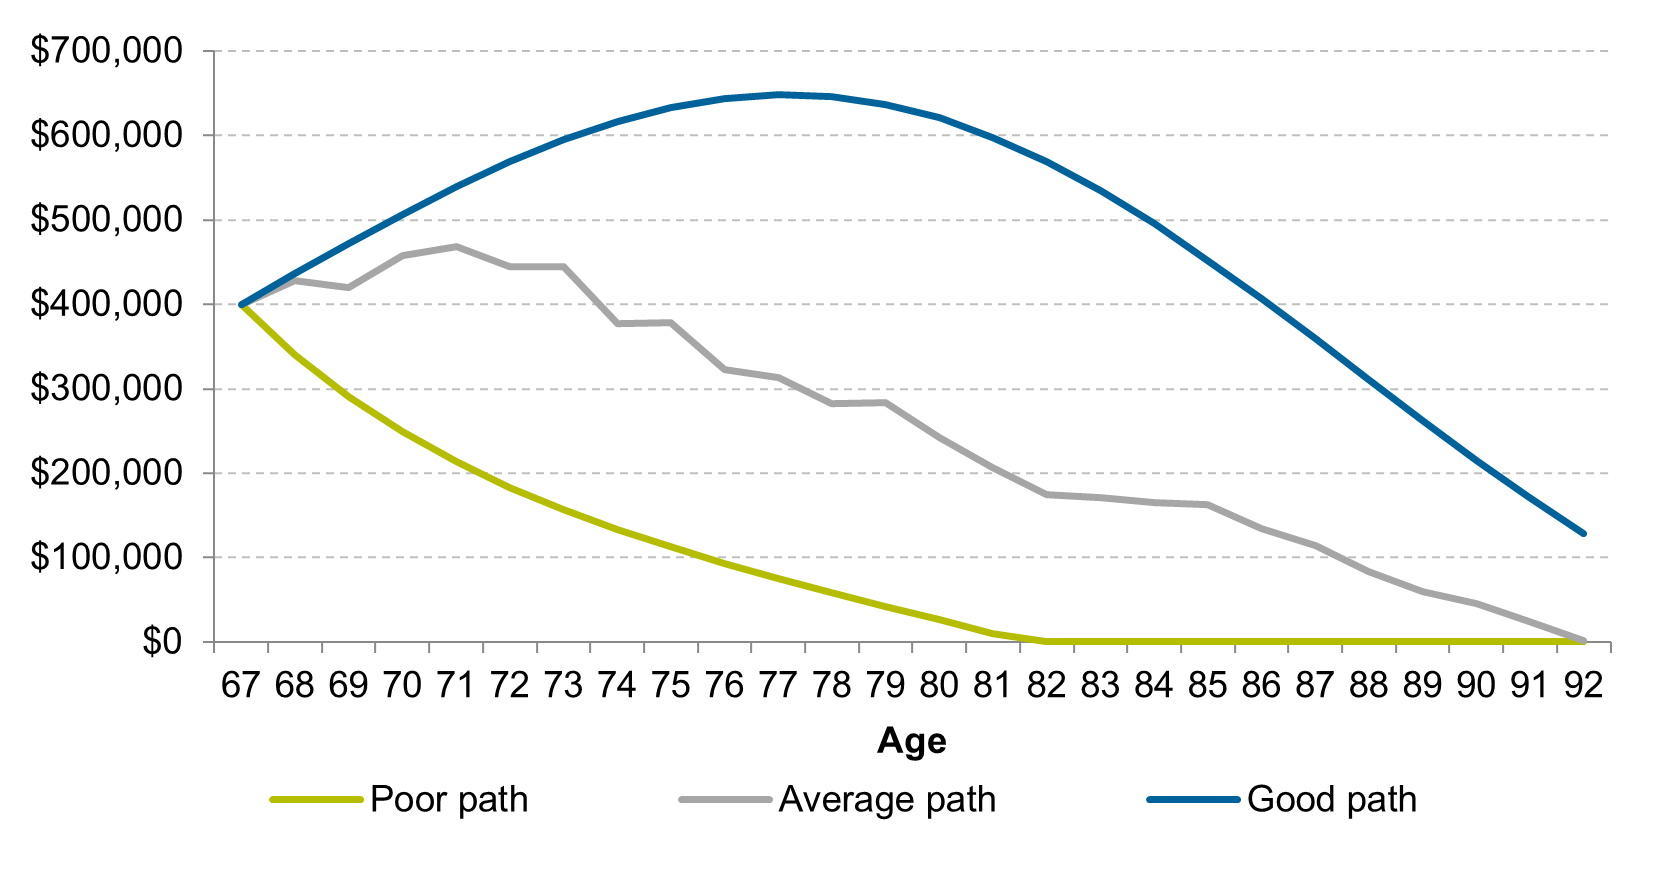
The chart below shows how long your savings might last through retirement. All three paths have the same rate of return – but the returns are in a different order. If returns follow the average path, savings can be drawdown for approximately 25 years. If they follow a good path, there may be excess savings at the end, which could be left as an inheritance.

The good path delivers higher returns early in retirement, while the poor path has weak returns at the start. This means when income in drawn there is less capital invested when the market eventually recovers. The result is that savings can be depleted early.

Chart 4: The impact of the path of returns in retirement
Source: Challenger Ltd

5. Understand the components of retirement income

Research from Challenger and National Seniors Australia revealed 90% of Australians over 50 don’t believe the Age Pension is sufficient to fund their lifestyle in retirement. In fact, half of those surveyed believed they would need an additional $10,000 (singles) and $15,000 (couples) more than the Age Pension per annum to meet their needs.

This is where a partial allocation to a lifetime income stream can help with a retiree’s peace of mind. There is a common misconception that retirees should invest everything into a lifetime income stream. In reality, a partial allocation can be sufficient to look after long-term needs, while maintaining a pool of capital.  It can also give retirees the confidence to spend more on their lifestyle in early retirement, while they have the health and energy to really enjoy it.

Chart 5: Income layers to help meet your needs and wants in retirement
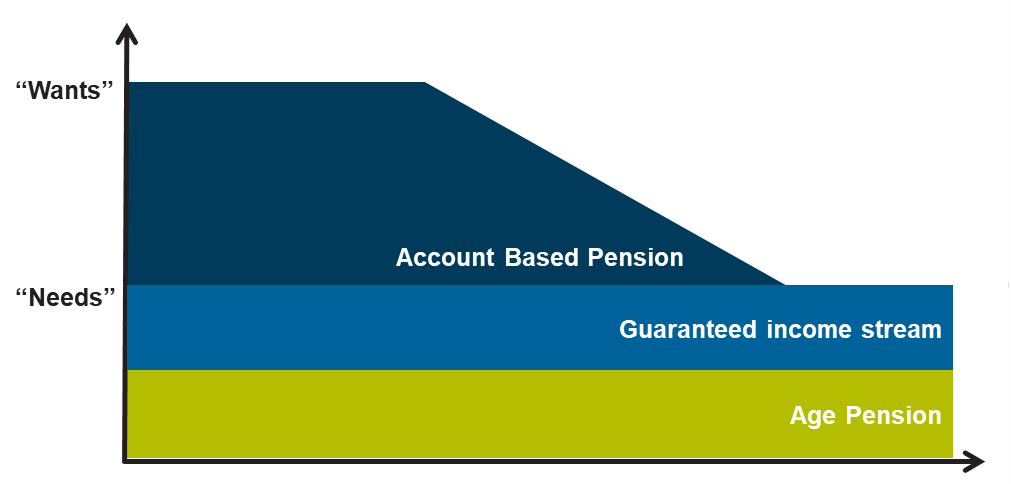
Source: Challenger Ltd

Retirement can be an emotional time. Arming yourself with knowledge, seeking out a trusted support system, which may include professional advice, and setting up the right financial structure at the outset can help alleviate the stress and ensure you enjoy the hard-earned lifestyle you deserve.


Aaron Minney is Head of Retirement Income Research at Challenger Limited. This article is for general educational purposes and does not consider the specific circumstances of any individual.


  •   10 September 2025
  • 14
  •      
  •   
14 Comments
AJH
September 14, 2025

If you buy $500k of dividend paying Australian shares and the market value drops to $250k, you only lose capital value if you sell.

If dividends stay the same or increase, you’re not losing income.

Aaron Minney
September 15, 2025

AJH
That is true, but there are two issues for some retirees:
1) Dividends have sometimes fallen, and they have not always kept up with the cost of living
2) Not everyone can afford to only live off the dividends and pass the wealth to the next generation. This is the key to retirement financing- consuming savings capital to maximise lifestyle in retirement. This is why chart 1 is first- If you can grow or preserve your wealth and enjoy the lifestyle you want, you have no retirement challenge.

Ramani
September 17, 2025

Our super regime now in its 34th year is going through adolescence, with the regular changes suffused with acronyms that would shame a bureaucrat (RBL, TBC, BDBN...). The focus is slowly shifting from accumulation alone to withdrawal. Its (ab)use as an estate planning device is placing too heavy a burden.
Hardworking, prudent and lucky savers grappling with the tensions from making it last the residual time (including reversion to partner), enjoying the nest egg, providing for contingencies (ill health, age-related accidents, relationship difficulties, adjusting for evolving aspirations...) will do well to remember the following:
1. Use the money to live the twilight time.
2. Prioritise physical, mental and relationship welfare.
3. If affordable, give to potential inheritors and worthy causes while alive. The smile on the grand kid's face following your gift on tertiary studies is priceless, not to be deferred after death.
4. Retirement is the time to pursue interests beyond those in working life. Go for them, without fearing the demons of failure.
5. Apologies to the architects of the regime and the professionals it has spawned, it can only deal with money issues (after a fashion). Non financial aspects are outside its brief and cabability (just as your prescribing health professional will not cook your favourite meal). You (with your partner) be the arbiters of your holistic destiny.
6. Manage expectations (of the regime, yourselves and others).
Lounge easy on the easy chair in the Departure Lounge!

Peter Vann
September 11, 2025

“it is crucial we provide older Australians with the tools and insight needed to confidently navigate this new stage of life.”

Yes, yes and yes.

Aaron, what tools can you suggest members of superfunds can use to manage their financial retirement outcomes in such an uncertain world?

Thanks
Peter

Dudley
September 11, 2025

"need an additional $10,000 (singles) and $15,000 (couples) more than the Age Pension per annum":

Drawdown with full Age Pension:
= PMT((1 + 4.3%) / (1 + 2.3%) - 1, (100 - 67), -481500, 0)
= $19,937.66 / y

AccentOnYouenglish dot com
September 11, 2025

Please provide the SOURCES for your charts! In particular, where did Chart 2 come from? Why has a surviving member of a couple got a far higher chance of surviving? These charts have no citations at all as to their source. Why? Thank you

Geoff
September 12, 2025

Because the one who isn't surviving hasn't survived?

Michael
September 12, 2025

In almost 100% of cases the first member of a couple who dies first is outlived by their partner.

Aaron Minney
September 15, 2025

Hi AccentOnYouenglish dot com
Here are the sources for the charts:
1. Author construction
2. Based on Australian Life tables 2020-22 with mortality improvements from AGA for 25-year factors. the Couples are assumed to be the same age at the start, hence the survivor lives longer as Michael notes (unless both die at the same time).
3. Author calculation
4. This is a theoretical version of sequencing. Returns over 25 years are every possibility from -12% to +12%. The good path is high returns first, the poor path is low returns first. The average parr was a random sequence with drawdowns set at 3% of the original balance, growing by 2.5% every year.
This version shows the range of outcomes. Similar versions can be constructed when you take 25 years of returns and simply reverse the order of those returns, (although in some periods the result is similar).
5. Author concept.
Apologies for the missing sources- they were in an earlier draft- I'll own the error for them dropping off.

James Gruber
September 15, 2025

Hi Aaron and AccentOnYouenglish,

For completeness, I've now added the sources for the charts to the article.

AccentOnYouenglish dot com
September 16, 2025

Thank you to the author for adjusting to include some citations. Not sure why other commentators feel the need for 'smart arse', sarcastic and useless responses such as " the survivor has a 100% chance of dying after the first person dies". Really? Isn't this forum for intelligent people with some knowledge of economics/finance to discuss in an intelligent manner? Not some social media thread where smart arses abound? The chart currently indicates that the "surviving" member of a couple lives *longer than average* for that gender. But no explanation as to why they outlive the 'average'? Unless the chart is misleading. That is why the source is important - to try to find out the real intent of that additional curve which is not about averages. Thank you to the authors for your work and to the 'non smart arses' for engaging in elucidating discourse.

Dudley
September 11, 2025


"4. Understand market risk in retirement (AKA sequencing risk)",
"All three paths have the same rate of return – but the returns are in a different order.":

With withdrawals proportional to rates of return, the outcome is identical.

With no withdrawal, the outcome is identical (no withdrawal has same proportion to all rates of return, ie 0).

With fixed withdrawal is when outcome depends on sequence or returns.

Vary withdrawals to maintain proportionality to rate of return to avoid exhausting funds.

If expenses are larger than such withdrawals, then the fund was undercapitalised or the withdrawals too large.

Michael
September 14, 2025

Just stand in the queue at a bank to appreciate there are too many clients, retired or otherwise, who cannot cope with the basics of 21st century banking, let alone managing their finances. Did someone mention we need better productivity? The banks are desperately trying to cut their costs when they are getting such self inflicted low productivity at their retail coalface.

Steve
September 14, 2025

Dudley touched on a simple point earlier. The assumption that income drawn from investments should never change is silly. If investments have a bad year and your pool of capital is lower, spend a bit less, skip the overseas trip for example. Small business owners, farmers etc have for generations had to adjust their expenses to match their incomes, retirees need to show the same level of common sense. If you can, try to target spending as a percentage of assets. Even better, try to arrange your investments to provide a cash flow close to your spending percentage, meaning you have less need to sell down assets to cover costs but rely on the cash flow. As best you can.


Leave a Comment:


RELATED ARTICLES

Protecting retirement income from inflation shocks

Why spending more in early retirement can improve lifetime income

Ranking three common retirement strategies

banner

Most viewed in recent weeks

Why have Australian living standards 'fallen' and how do we fix it?

For the last few years there has been much talk of a 'cost-of-living' crisis in Australia and of 'falling living standards'. Lately this has flared up again with the pickup in inflation resulting in a renewed fall in real wages.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

Four options for an income investor’s next dollar

What if Australia’s golden age of dividends is ending? Rather than overhaul your portfolio, it may be worth considering where new capital can work harder. I discuss four income strategies and the trade-offs behind each.

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Latest Updates

Shares

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Investment strategies

Making a case for the 40 year mortgage

The housing debate tends to focus on prices, interest rates and deposits. Yet an overlooked feature of the mortgage itself could help buyers enter the market sooner without abandoning prudent lending standards.

SMSF strategies

Red flags to watch out for when considering an SMSF

Thinking about an SMSF? Before you sign anything, learn how to spot the difference between genuine advice and a sales pitch, understand the real costs, and avoid the compliance mistakes that attract ATO attention.

Investment strategies

Not all income is created equal

Market conditions are shifting as familiar yield sources quietly lose momentum. Australian public credit may be the most compelling source of income in today's market but many investors haven't noticed the shift. 

Investment strategies

The market paid for change, not comfort

Reporting season has delivered a clear message: the market is no longer paying simply for quality, resilience or an earnings beat. It is paying for change in earnings expectations and the outlook ahead. 

Investment strategies

Will AI destroy investor capital?

Some of history's most important innovations changed the world while leaving investors much poorer. As trillions pour into AI, a familiar pattern may be emerging, one that rewards society far more generously than capital.

ASX reporting season: Signals, surprises, stock stories

August reporting season delivered strong earnings and bigger-than-expected dividends, but beneath this, a more nuanced story emerged. First Sentier Investors’ David Wilson and Christian Guerra unpack the key trends.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.