Consumers have never been more fickle, in a world of fast fashion and next-day delivery. Covid has further upended our purchasing behaviours and expectations, but some companies have benefitted.
Against the odds, luxury goods giant LVMH (EPA:MC) has become more desirable over many centuries and emerged from this disruptive period stronger than ever. What’s its secret?
LVMH (Louis Vuitton Moët Hennessy) is the largest global luxury goods company, owning 75 iconic brands such as those in its name as well as Christian Dior, Sephora, Bulgari and Tiffany. It has a long history of growth and profitability, even in difficult market environments – in fact it has not made a loss in a single year of its existence.
Let me share with you five features of this business that have allowed it to prosper in the face of ever-changing consumer preferences.
1. Heritage
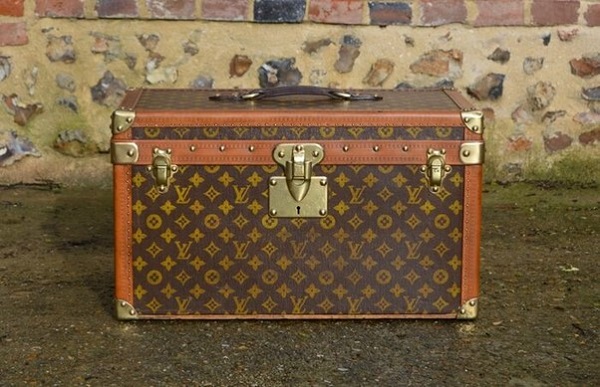
The Clos des Lambrays vineyard dates back to 1365. Chaumet was founded in 1780 as a jeweller for the French Empress. Louis Vuitton was born 200 years ago and founded his business to make suitcases, featuring the classic monogrammed logo design, for the French royal family.
LVMH’s brands are steeped in history and tradition. There is a story behind their products, they stand for something. The depth and authenticity of their heritage cannot be replicated by younger luxury goods brands. This heritage and desirability only builds over time, making it even more difficult for new entrants to succeed.
2. Innovation
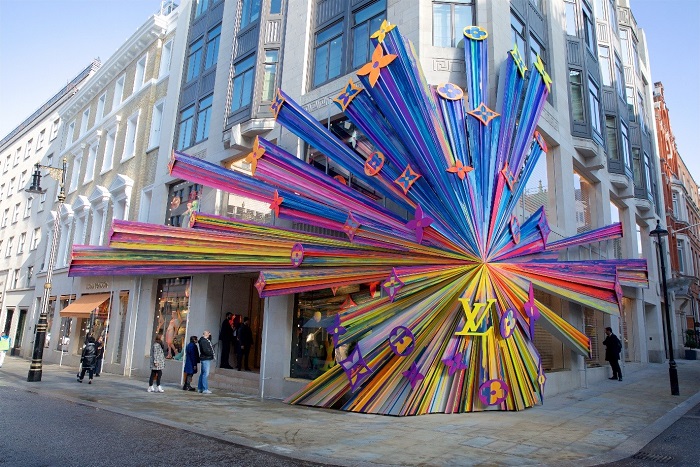
But they aren’t just old, tired brands. LVMH has done a great job of straddling tradition with innovation, remaining contemporary and relevant with consumers. It invests over €20 billion each year into creating new products (which represent about a quarter of its sales in a given year), advertising its brands through engaging campaigns, and refurbishing its stores with vibrant and constantly evolving displays.
LVMH also has an ongoing annual intake of thousands of new apprentices and talented young designers that bring with them new ideas. Half of LVMH’s employees are under the age of 34, which is remarkable for such a longstanding business.
3. Agility
There are 75 brands owned by LVMH which operate as largely independent businesses, keeping them agile and entrepreneurial. The company’s response to the Covid pandemic was a great validation of this strength.
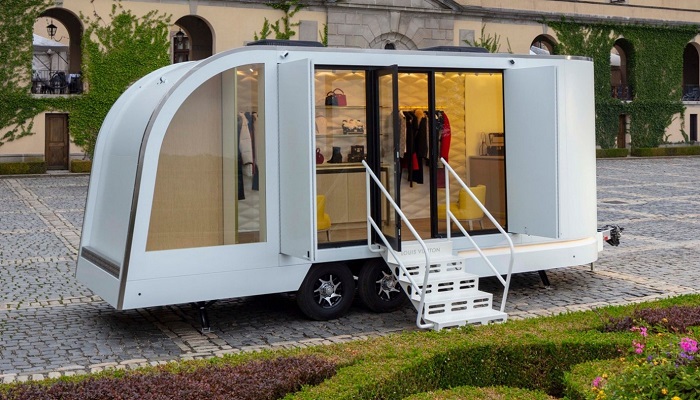
Consumer behaviour changed drastically, with retail stores shut and travel grinding to a halt (which is when a large portion of luxury sales are traditionally made). LVMH adapted more rapidly than its competitors, resulting in massive market share gains and a quick recovery in profits. Its brands continued to invest in new product launches, virtual fashion shows and marketing, unlike others which withdrew their investments. They also found novel ways to serve a local clientele, such as these incredible mobile stores which brought a caravan with a bespoke selection of products directly to the homes of their most valued clients.
4. Control
LVMH makes most of its products in-house and sells most of its products through directly-operated stores, giving it full reign over the quality of its products, how they’re priced (Louis Vuitton is notoriously the only luxury brand that never discounts its products), and the customer experience. Contrast the look and feel of a Louis Vuitton store and the attentive customer service you’d receive in one, to the unorganised mess of a department store.
The company is obsessed with product quality, taking the long-term view that if you can focus on satisfying your customers, the financial outcomes will naturally be favourable. It has a high degree of control over its supply chain and materials usage, e.g. recently acquiring a sustainable crocodile leather tannery in Singapore to ensure its supply of a scarce resource, which is proving valuable amid the current global disruptions.
5. Breadth
LVMH sells a lot more than Fashion and Leather Goods; it also has businesses across Wines and Spirits (where it is the largest global producer of champagne and cognac), Perfumes and Cosmetics, Watches and Jewellery (where it recently acquired Tiffany) and Retailing (where it owns Sephora).
Its breadth across these five divisions, 75 brands and many countries provides valuable balance and resiliency to the inevitable ups and downs in any one area of consumer spending.
LVMH’s breadth is important when considering the Chinese government’s increasingly intrusive stance on the behaviour of its citizens. China has certainly been an important contributor to LVMH’s growth, and today Chinese consumers represent a third of its sales across a very broad range of goods. However, LVMH is a truly global business that is growing strongly in other geographies as well. The company reported exceptional results in the first half of 2021, where sales grew faster from its US and European customers than in China. LVMH shares have fallen by 10% over the last month, and some of its luxury peers have fared worse, but the market’s focus on these events may be masking the business’ finer qualities.
In conclusion
These five attributes have contributed to LVMH’s growing desirability, long track record of growth, and enviable profitability. In the Aoris International Fund we own a portfolio of 15 durable, all-weather businesses like LVMH, which we expect to keep compounding in value for many years to come.
Delian Entchev is a Senior Equity Analyst at Aoris Investment Management. This article is general information and does not consider the circumstances of any investor.