Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 336

Millennials struggle to invest, but property top priority

As fund managers globally scramble to diversify and future-proof their client base, more attention is now being paid to the financial needs of millennials, a demographic born between 1981 and 1996, which investment firms have struggled to appeal to.

However, a recent Calastone study of 3,000 people aged between 22 and 34 across the UK, France, Germany, US, Hong Kong and Australia sheds light on some of the lifestyle habits, ambitions and general trends among millennials in what could help fund managers better target younger investors in the Australian market.

Property priority top, ability to invest bottom

Investing does not elicit much interest from millennials globally, and young people in Australia do not buck this trend. The study found that while millennials in Australia may not be assiduously saving on a monthly basis, 71% do have some sort of saving, ranking the country higher than every market bar Hong Kong. Respondents in Australia said their primary motivation for saving was to fund their first property, a higher proportion in Australia than any other country in the study.
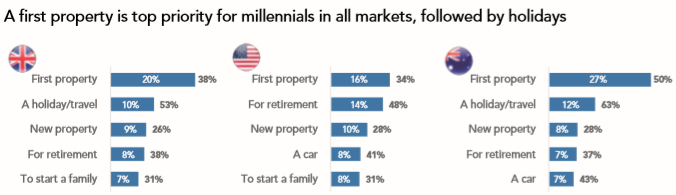
Blue bar is ranked 1st choice, other number is ranked in top 5 choices.

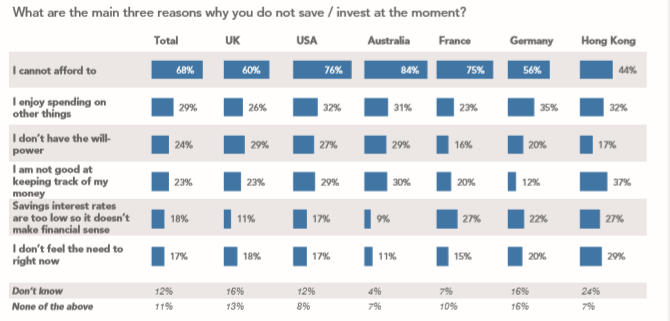
However, as shown below, a disproportionate number of Australians (84%) said their main reason for not saving was because they were unable to afford to, well above the global average of 68%. Calastone also found most Australians (71%) felt they were unlikely to receive a high-value inheritance in the next 20 years, although this is aligned with the global average. 
Millennials and money management

Although the majority of millennials globally keep their money in a savings or current bank account, there are some regional divergences in terms of how young people invest. The study found 10% of Australians invest in funds – putting it ahead of the UK and France, but a long way behind the US and Hong Kong. Most Australians said they were investing to achieve long-term capital accumulation and returns, something which is presently unavailable from many savings accounts due to the low interest rates.

Looking ahead, Australia could be quite attractive for fund managers with 76% of all millennial respondents in the local market saying they planned to invest in the future, well exceeding that of France (54%), Germany (56%) and the UK (64%), but falling short of Hong Kong (81%) and the US (77%). However, if the funds industry is to attract these assets from millennial investors in the Australian market, it needs to better understand how this generation currently purchases its goods and services.

Attracting millennials into investment funds

Technology is clearly important to millennials, with local respondents confirming they organise their personal lives online and use apps wherever possible.

According to the study, 57% of Australians will buy services and products either online or via a mobile app, putting the country on a parity with the global average. Australian millennials appear to be more technically astute when it comes to banking with 64% saying that having online access to their account information was critical, compared to the global average of 56%. Furthermore, 52% confirmed they wanted access to their bank account information through an app, which was far higher than anywhere else, particularly in Germany where only 27% said the same.

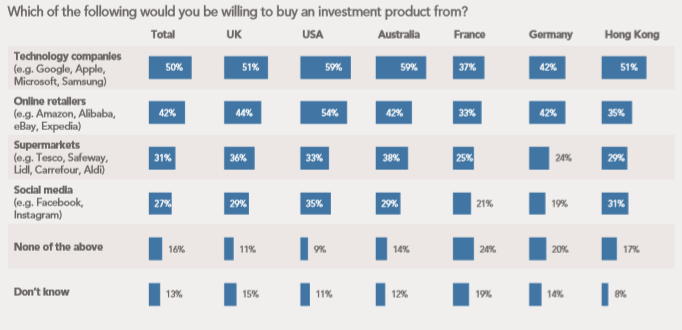
A large proportion of Australian millennials (59%) – along with those in the US (also 59%) – told Calastone’s survey they would willingly purchase investment products from technology companies such as Google or Apple in contrast to investors in Europe and Hong Kong who appear to be more sceptical about the idea. Among those Australians who already invest, 73% said they would buy an investment product through a technology company, well above the global average of 63%. Furthermore, 48% of Australians said they would trust a computer algorithm to invest their money, which is broadly in line with other countries.
Australia's millennials have a strong savings culture, and while Australian respondents have yet to fully embrace investment products, many young people are keen to invest in the future. However, embracing digitalisation will be crucial for asset managers if they are to win mandates in the tech-savvy local market. A failure to digitalise could impede asset managers’ efforts to raise funds from millennials.


Ross Fox is Managing Director and Head of Australia and New Zealand at Calastone.


  •   11 December 2019
  • 5
  •      
  •   
5 Comments
Chris
December 11, 2019

It's easy for the finance industry to engage. Shift your focus from the boomers to Gen-X and start from there. The time to build wealth and engage with these people is when they are young, not when they are older and "might" have been able to do so. There is also no guarantee (especially for me, who has two parents in 24hr care and the family home just got sold to pay their medical bills) that we will inherit the boomer's money. In fact, some of us - like myself - don't and never did expect it.

Unfortunately, it's hard to find a financial planner, even as a Gen-X because most that I've seen ARE boomers and hence, more interested in servicing and relating to their own demographic. You can't have it both ways.

As an example, the amount of questions in the financial media (esp. in the AFR Q+A section on the weekend in Smart Money) are all about SMSFs, retirees, "what pension I can get because I earn X and my wife earns Y but we have A, B and C in shares, property and super" etc. Yawn, not relevant to me as a Gen-X.

Most also look like the cookie cutter corporate - white, male, grey suit. That's not necessarily something that younger demographics (born into the internet age of no ties and polo shirts) or even female investors relate to.

So for now, I think I'll keep on keeping on with my DIY approach (which has done quite well, thank you) and maybe when I get closer to retirement, I'll ask a financial planner then, who would be Gen-X.

Jeremy
December 11, 2019

Aussie fixation with property continues for another generation. Is it our culture or tax system, because European countries are not like this.

Gen Y'er
December 11, 2019

A bit of both, but I think it starts with how us Gen Y'ers (I refuse to use the cringey term 'Millenial') were raised.

We're the children of the Boomers, and the Boomers, like a lot of people, love a good asset bubble. It's an easy 'get rich quick' scheme which requires little work or effort to benefit from. Stocks used to be all the rage through the '80s until the early 2000s when stupid Boomers over-leveraged and got burnt for a second time in the tech wreck; the first being in 1987. They then started to fear the sharemarket and see it is dangerous, and never went back to 'investing' in it at the same levels they used to. Then they turned to property as it was an investment class outside the sharemarket and they saw it as a 'safe' investment. Constant buying, coupled with the original 'Australian dream' of home ownership, greed, stupidity, increasing immigration, falling interest rates and so on caused another bubble. This property bubble, however, is constantly inflating which pushes house prices higher, which creates a 'you can't lose' attitude, which causes more buying and selling and a feedback loop is created.

Now, all the while since 1987 the Boomers have been having children. Their children (like myself) are then taught the distorted teachings of the Boomers; the sharemarket is evil and bad, and property is the only good investment. They started to (and still do) trot out the same inane and idiotic dribble; "Property always goes up," "you can't go wrong with property," "don't invest in shares because you'll lose all your money." etc. This creates a new generation worshipping The Cult of Property, which fosters tunnel-vision towards only one class of investing at the detriment of all others, and the buying and selling of this one asset class causes prices to continually rise, which strengthens the belief in The Cult.

SMSF Trustee
December 11, 2019

European countries face a situation in which most land is owned by 'old money', made from feudal and other systems that didn't allow the home ownership aspiration that a young country (at least in Western terms) has been able to support.

So I guess it's cultural, at the core of what Australia offered to get people to come here (once the penal colony days ended, at least). The fact that it's been possible for everyone to aspire to own their own 'quarter acre block' has in turn resulted in a poor landlord-renter relationship structure so that most people would prefer not to rent.

I hope this never changes. I don't want most land to be in the hands of only those who own it because their family owned it 200 years ago!

Peter
January 06, 2020

I think most millennials see fund managers are superfluous and would rather just invest in a diversified low fee index tracker which is proven to outperform investment funds in the long run. Unfortunately there’s not much you can do to appeal when you’re seen as a middleman that ought to be cut out to maximise returns


Leave a Comment:

RELATED ARTICLES

It’s as much Smashing Pumpkins as smashed avocado

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.