Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 344

NAB hybrid: one says buy, one says sell, you decide

Two fixed income specialists have opposite views on NAB National Income Securities (ASX:NABHA). Differences of opinion make a market as each side determines whether NAB is likely to call the bond. The debate is heightened by the recent decision by Macquarie Bank to call Macquarie Income Securities (ASX:MBLHB).


MBLHB call at par bodes well for NABHA

Justin McCarthy, BGC Securities

After the market close on 30 January 2020, Macquarie Bank announced that it will call/redeem the legacy Tier 1 Macquarie Income Securities (MBLHB) for $100 (par) plus accrued interest on 15 April 2020.

The MBLHBs traded at $93.00 prior to the announcement but promptly moved to ~$100.00 the next day, where they have remained.

The MBLHBs join a long list of legacy securities that have been called in recent years as the capital treatment towards regulatory ratios falls in line with the Basel III transitional rules. All legacy/non-Basel III compliant Tier 1 and Tier 2 securities will become completely ineligible for regulatory capital from 1 January 2022.

Macquarie Bank noted in its call announcement that only $94 million or 23.5% of the MBLHBs were counting towards Additional Tier 1 (AT1) ratios at present which would have been a strong reason in favour of the early call.

The MBLHBs were issued in 1999, as were the similar NABHAs, which were both classified as ‘Income Securities’.

The call at par of the MBLHB follows last year’s call by ASB Bank (a subsidiary of CBA) of two NZD legacy Income Securities which were trading at ~NZD82.50 and ~NZD85.00 prior to the announcement.

Our opinion and base case is that NAB will likely call (or possibly roll over into a new capital security) the NABHAs in early 2021. Whilst MBLHB is only counting 23.5% towards Macquarie Bank’s AT1 ratios, NABHA is considerably higher at ~62% in 2020, suggesting they still have a meaningful contribution to NAB’s AT1 ratios. From 1 January 2021, the contribution falls to just ~31% and then 0% from 1 January 2022.

The call announcement of the MBLHB strengthens our already high confidence that the NABHAs will be called before 2022. Following the Macquarie Bank announcement, the NABHAs jumped $2.55 or ~2.7% to a high of $95.45 (at the time of editing on Tuesday, they are $95.35).

The following table details the yield to February 2021 call and November 2021 for various purchase prices (dirty price).

Purchase Price

Yield to Feb-2021 Call

Yield to Nov-2021 Call

$93.50

9.13%

6.06%

$94.50

8.06%

5.44%

$95.50

7.00%

4.83%

$96.50

5.96%

4.22%

$97.50

4.92%

3.62%

$98.50

3.90%

3.03%

Given our base case is for a call in early 2021, we believe the NABHAs still exhibit good value. A call in 2020 (and hence higher returns than in the table above) can’t be ruled out either with hybrid refinance conditions currently favourable and new issue margins near post GFC lows.

NAB has also been proactively buying back their legacy Tier 2 USD ‘Discos’ issued in the US market despite the very cheap credit margin of just 15bps (0.15%).

This recent announcement from Macquarie Bank also continues to support our strategy of investing in well-priced hybrids and securities from best-of-breed companies but down the capital structure. Many of our best-performing recommendations have been from the maligned hybrid sector, including SVWPA, MXUPA and MBLHB which have now all been called at par despite trading in the $70s just a few years ago.

NABHA perhaps not on road to redemption

Simon Fletcher and Charlie Callan, BondAdviser Hybrid Research

NABHA was issued in 1999 and was originally due to be called on the 29 June 2004 but, at its discretion, NAB decided to leave it outstanding. Unlike the NAB Convertible Preference Shares or the more recent Capital Notes, this security has no conversion features or triggers embedded in the documentation and therefore we are much more comfortable with the security from a structural perspective. However, as was evident during the GFC, the capital value of this security is still subject to significant volatility during a period of stress.

As a perpetual security (meaning it has no defined call date or maturity date), it is difficult to put a true valuation on it. Due to the effect of changes in what now qualifies as regulatory capital, we do expect it will be redeemed or exchanged within a reasonable time horizon (before or during 2022). The reason we have identified this timeframe is that although the contribution to regulatory capital value is still high (2019/2020), it will rapidly decrease and will reach zero at the start of 2022.

We have revised our recommendation on NABHA to Sell, as the Notes rallied strongly in response to Macquarie Bank announcing that MBLHB will be repaid.

Following the introduction of the Basel III regulatory scheme, APRA bundled several NAB securities issued under Basel II together, permitting NAB to use $6.05 billion of its Basel II capital as Tier I under Basel III. Under the scheme, the Bank is required to reduce the Basel III contribution by 10% per year, with the allowance reaching 0% in 2022.

However, with a number of the securities in the initial pool having since been redeemed or refinanced, the share of NABHA that counts as AT1 capital has not progressively reduced. Rather, in 2019 ~90% counted toward AT1, up from ~80% in 2018, a result of the redemption of securities in the initial pool of Basel II Notes. This will reduce to ~60% in 2020, ~30% in 2021 and finally to 0% in 2022.

From a NAB Treasury perspective, NABHA appears to be cheap relative to any refinancing alternatives, and as such we estimate that NAB will have incentive to leave the Notes to run for longer than current market-consensus.

Furthermore, with the Bank facing significant refinancing hurdles in the near-term, opting to redeem an additional $2 billion through repaying NABHA would be relatively surprising in 2020. Given the above, as NAB leaves the Notes running, and assuming market consensus consequentially becomes more aligned to ours, we would expect the Notes to sell off in the shorter-term but we are reasonably confident that NAB will eventually redeem the securities.

If the security is called, the capital upside to investors is significant and the biggest driver of the Bank executing this call option is a lower marginal cost of funding. We continue to believe the cost will remain low enough over the coming years to warrant replacement but following strong price returns and margin compression since 2017 (which we captured with variable Buy recommendations), we believe the wider market is under-estimating the chance NAB may choose not to redeem NABHAs in the next few years.

We note NAB has two large, new-style hybrids to refinance in 2020 - $1.3 billion (NABPC) in March and $1.7 billion (NABPB) in December. In July 2022, NAB also has $1.5 billion to refinance (NABPD). It most recently raised $1.9 billion (March 2019) for NABPF.

We would likely revise our recommendation at a capital price lower than $90.

Investors should be aware the margin for this security has been volatile in the past, primarily due to the movement in the broader listed bank capital market (i.e. Tier 1 hybrids) rather than anything specifically related to this security or the Issuer.
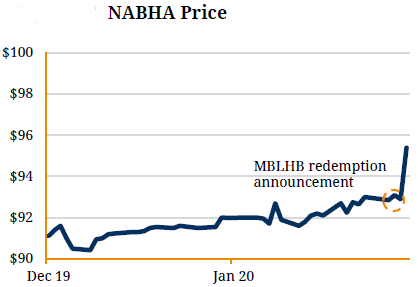
Source: Bloomberg, BondAdviser


This article is general information and does not consider the circumstances of any investor.

  •   12 February 2020
  • 1
  •      
  •   
1 Comments
Warren Bird
February 12, 2020

I think the comment in the second half of the article, saying that the perpetual nature of the NABHA's makes "it difficult to put a true valuation on them", requires some discussion.
First, it seems irrelevant to the thrust of the article, which is about second guessing the issuer in relation to a potential early redemption date. It's the uncertainty of the termination date that's creating the difficulty here, not the perpetual nature of the security otherwise.
This is an important distinction. If you can assign a date at which the security will be valued at $100, then you can include amortisation from the current market price to $100 as part of the nominal return you'll earn to that date. A perpetual security, even thought it has a 'face value' of $100, has no date at which it will actually be worth $100 to its holders - like any share price, the market will decide at any point in time what you could get if you sold your holding.
Still the comment is there and I'm not sure what it's trying to say. I can only presume that it's not intended to be as absolute a comment as it sounds. After all, every equity in the market is perpetual and the market has no problem valuing them. So I take it that the comment is meant to say that, relative to ordinary fixed income securities, it's harder to determine a value. That is, the maths is a little more complex.
But if you had a perpetual fixed rate bond, there'd be no difficulty. Discount the cash flows at an appropriate long term rate and voila, there you have your value.
So it's not the perpetual nature that provides the complexity, but the variable rate nature of this perpetual security that creates some complexity.
But again, surely it's easier to value a perpetual that has a fixed formula for generating the cash flows (90 day bank bill plus 1.5% per $100 face value) rather than ones that have the uncertainty of future dividends.
So the comment isn't wrong - I'm not saying that - but it's just not clear either why it's in the article or what it is really trying to say.

It's fascinating to me to see the potential end of the NABHA's being discussed. Funds I managed were among the first buyers of the NABHA's back in 1999. We put a small holding into a diversified fixed income fund that had a longer term investment horizon. We did have to work out how to value them. It was an unusual asset at the time - I think it still is! But it wasn't modelling cash flows to an indefinite end-date that was the problem - the maths of that is quite straightforward. The question was, compared with other credit spreads in the market at the time, was the margin over swap good value to lock in for a perpetual cash flow?
Sure, it was a wider margin than NAB's normal short-dated FRNs and corporate bonds, as you'd expect for an asset with some additional term risk in it. But the jump from 3 and 5 year market to a perpetual asset required some subjective judgment about whether there was enough term risk. There was also the question of whether it would be liquid enough for an institutional manager to be able to buy and sell based on value at any point in time.
We took the view that there probably wasn't enough to make it a really attractive asset, but that a small exposure could be taken to see how they travelled. We sold a fair bit of it at, I think it was, around $103 soon after as the implied margin in that price was definitely not attractive any more.

So I read the two opinions in the article as essentially a debate about when NAB will call the securities. Not if, but when. In either case, I think holders should celebrate because you're looking good to get full face value back soon. That hasn't looked likely for most of the two decades since it was first issued (which incidentally comforts me that our assessment that it wasn't great value at issue was right).


Leave a Comment:

RELATED ARTICLES

Is it time to sell bank hybrids?

The best income-generating assets for your portfolio

Why bank hybrids are far too expensive

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.