Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 631

The enduring wisdom of John Bogle in five quotes

Vanguard founder John C. Bogle had many famous quotes relating to investing that still hold true in today’s context. In this article, we revisit some of them in the hopes that they can inspire and guide you no matter where you are in your investment journey.
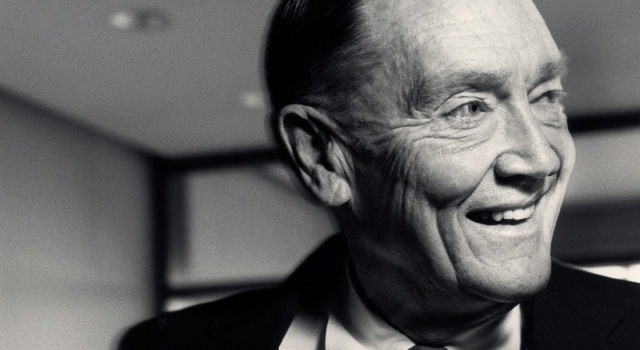
“Don’t look for the needle in the haystack. Just buy the haystack!”

This quote is probably the most famous of all Bogle quotes. The haystack refers to a broadly diversified index fund and is the basis on which one of the largest index funds — the Vanguard 500 Index Fund1 — was created nearly 50 years ago in 1976.

Bogle’s belief was that rather than try to pick winning stocks, market returns could be captured through a low-cost index fund. This approach not only offers exposure to potential growth across multiple sectors, but also provides the diversification benefits inherent in index investing. Today, millions of investors around the world benefit from the broad diversification and low costs of index investing.

However, index funds won’t suit everyone. Whether they fit your circumstances depends on your goals, time horizon and risk tolerance.

"Where returns are concerned, time is your friend. But where costs are concerned, time is your enemy."

Albert Einstein is often credited with calling compound interest the eighth wonder of the world. Whether or not he actually said it, the sentiment rings true. But even small differences in fees and costs can erode returns over time, which is why Bogle was so focused on reducing them.

As investments generate returns, these returns can be reinvested and over the long term, that can lead to exponential growth over time. On the other hand, every dollar that goes towards investment costs is a dollar less in investment returns. And over time, these costs can add up and have a significant impact on your portfolio balance.

“If you have trouble imagining a 20% loss in the stock market, you shouldn't be in stocks.”

Market ups and downs are a reality for every investor. But while bear markets (defined as a 20% or more drop in share prices from their high) can be unsettling, history has shown us that staying invested during volatile periods can improve an investor’s chances of investment success over the long-term.

However, Bogle’s quote not only emphasises the importance of staying focused on your long-term investment goals but also highlights the value of understanding your own risk appetite.

It is natural to feel confident when markets are doing well and to feel concerned when they are not. But if short-term volatility is causing you extreme anxiety, perhaps consider if your asset allocation is aligned to your personal risk tolerance, and if it is sufficiently well diversified for you to weather difficult market environments.

“Speculation leads you the wrong way. It allows you to put your emotions first, whereas investment gets emotions out of the picture.”

Speculation and investing both mean putting your money into things you hope will grow, but the way you go about it is vastly different. Speculation is about chasing quick wins — trying to catch the next big jump by following market trends or timing. It can be risky and come with big losses, as well as occasional big wins. Investing, on the flip side, is about playing the long game: picking things based on real value, steady growth and patience. Knowing the difference will help you choose what fits your goals and risk appetite.

"Don't do something — just stand there."

In times of market volatility or severe market disruption, it can be tempting to “do something” instead of just watching the market indices go down and further down.

However, it is important to recognise that choosing not to act in response to a volatile period in the markets demonstrates intentional decision-making. Perhaps it was a conscious decision in consultation with your financial adviser, or willing yourself to stop checking your investment balance too often.

History shows that those who remain invested are often the ones who benefit the most in the long run.


Vanguard is a sponsor of Firstlinks. For more articles and papers from Vanguard Investments Australia, please click here.

All investing is subject to risk, including the possible loss of principal. Be aware that fluctuations in the financial markets and other factors may cause declines in the value of your account. There is no guarantee that any particular asset allocation or mix of funds will meet your investment objectives or provide you with a given level of income. Diversification does not ensure profit or protection against a loss.

1 The Vanguard 500 Index Fund is a US domiciled fund and is not offered in Australia. This reference is for historical context only and does not constitute an offer or recommendation. Australian investors should refer to locally available products and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD) before making any investment decision.


  •   1 October 2025
  • 3
  •      
  •   
3 Comments
Kevin
October 02, 2025

All well and good,and true. Perhaps add the Buffett quote,put your hands under your arse and sit on them,that stops you from doing anything stupid and typing anything stupid.

People are incompetent ,they cannot grasp the simple concept of compounding.If I had a $ for the incompetence of people that invent time machines, or keep saying "we can all look back" I would never need to invest.If you put X$$ into a Vanguard fund and compound it for a long period of time. (30 years at least) you'll be very comfortable. Or for me CBA and NAB all those decades ago.Add on a few more as the journey continues.

It takes a special kind of stupid to deny that for an entire lifetime,keep repeating time machines,we can all look back,you can't do that,how come everybody else isn't doing that,get everything precisely wrong etc etc.

They work so hard to avoid to avoid wealth and then cry"why do the rich get richer,how can we stop this".In 10 years time we'll know how much shares in CBA and NAB are worth. People have had another 10 years to show how incompetent they are,get everything precisely wrong,come out with the stupidity of time machines etc etc.Investing is such good fun,it highlights how money makes fools of people.

Blue skies,sunshine,bike time,also great fun. Does the value of the portfolio increase $100K today,or decrease $100K. The bike is my secret "time machine".

Good article,completely shows just how incompetent people are as they make up there own nonsense and invent their own facts

Dudley
October 02, 2025


"time machines, or keep saying "we can all look back"":

Everyone can look back in time due to the ninth wonder of the world - writing.

Only the time traveller can go back and make investments, sure in the knowledge that they are not gambles.

DamienP
October 02, 2025

Hmmm, Kevin the bike rider makes some good points but delivers them with the same brashness and disdain of a bike rider who feels he owns the road. Hint: more than a handful of bike riders are ‘a special kind of stupid’.
Not going the distance on an investment doesn’t make a person stupid, there are many other reasons. for consideration. I love my home but spartan common sense might suggest I would have been wiser to invest a large chunk of it. That said, no coffin is built with pockets…so I am very happy with my decisions.


Leave a Comment:

RELATED ARTICLES

A tonic for turbulent times: my nine tips for investing

The new capital gains tax trap for your portfolio

The investing rule that explains the next market crash

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.