Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 199

Why Australians love dividends and franking

In no other country do shareholders love dividends as much as in Australia. Here are 10 key facts on dividends and franking, including one concluding piece of trivia.

1. Over the long haul, dividends have generated about half of the total return – capital gains plus dividends – investors have earned from Australian shares.

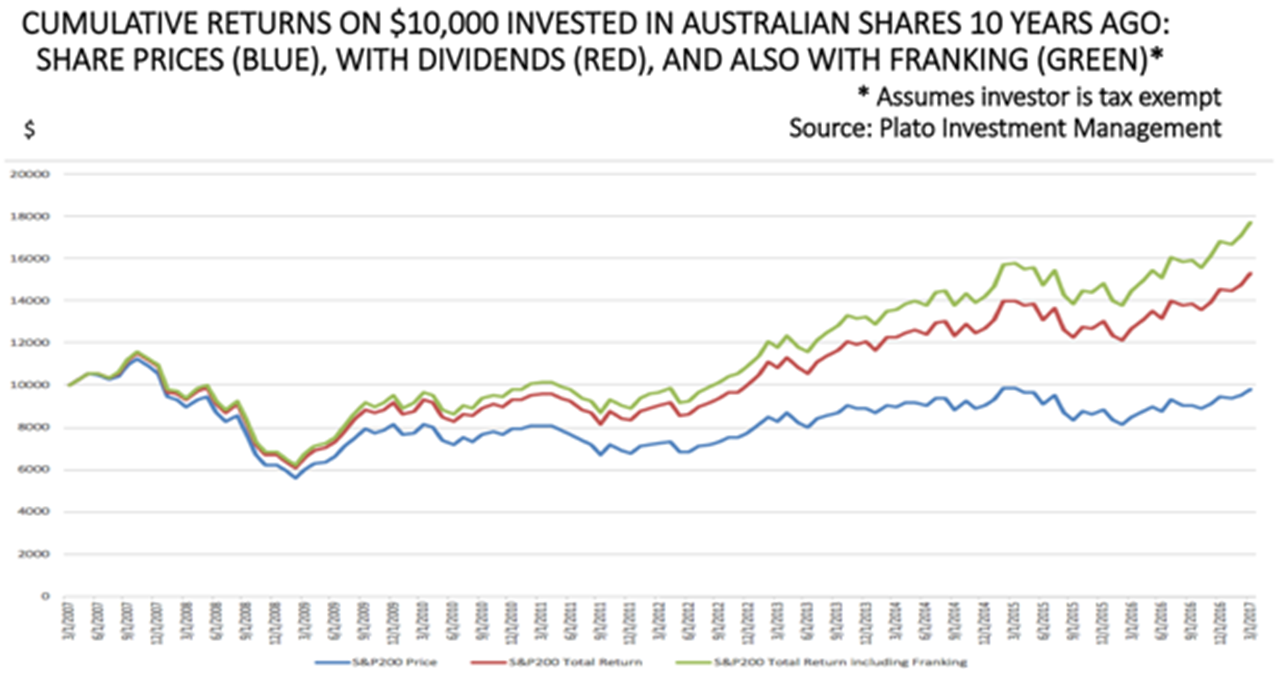
2. Dividends have more than pulled their weight in the last 10 years. Despite the collapse of share prices in 2008, the average investor who entered the share market a decade ago has achieved positive total returns, mainly due to the combination of good dividends and franking credits. The S&P/ASX200 Price Index (excluding dividends) is currently around 5,900, still well below its October 2007 level of 6,754.

The importance of dividends and franking credits to investor returns is illustrated in this chart from Don Hamson of Plato Investment Management. For many years, Plato has successfully run a managed fund specialising in franked dividends, and is currently launching a similar listed investment company.
3. Dividend franking particularly benefits investors on low tax rates. To a tax-free investor, including superannuation funds in pension mode, each dollar of a fully franked dividend is worth $1.43. That dollar of fully franked dividends would be worth $1.21 to an investor paying tax at 15%, including superannuation funds in accumulation mode. (From 1 July, tax at 15% will also apply to income paid into a retiree’s superannuation balance on assets exceeding $1.6 million).

4. For eight years, the average dividend yield on Australian shares has consistently been between 4% and 4.5% a year. With interest rates at low levels, and many investors on the hunt for yield, shares with good dividend prospects have had additional appeal.

5. Of course, it’s sustainable dividends that matter in stock selection. Among other things, investors need to avoid holding shares on which dividends are ‘paid’ from asset revaluations and capital raisings, and to be alert for ‘dividend traps’ (where the high dividend yield on a share may simply reflect the low share price because of an expected cut dividend).

6. Over the investment cycle, dividends are more stable than either company earnings or share prices. At times, however, dividends vary suddenly and unexpectedly, such as the dividend cuts announced by banks in 2009 and resource companies in 2016. The usual sequence in the investment cycle is for share prices to go through their cyclical turning point (maybe after one or more ‘false dawns’), followed by the turning points in company earnings and (later) in dividends.

7. On average, dividends account for about 80% of the after-tax earnings of Australian companies. That’s more than double the proportion paid in the US, where dividends are taxed twice and capital gains are taxed at lower rates than in Australia. Often in the US, total share buybacks exceed dividends. Even then, however, US companies finance a higher proportion of their future growth from retained earnings than Australian businesses.

8. Over the long haul, the average dividends per share in Australia has risen by about 7% a year – or slightly above the long-term increase we’ve experienced in nominal GDP. Looking ahead, trend growth in average dividend per share is likely to be a more modest 5% a year.

9. Dividend franking will lose some appeal from the recent legislation to cut the rate of company tax on businesses with revenues of less than $50 million.

10. Finally, let’s look at a dividend yield that shows this year’s dividend as a per cent of the share price an investor would have paid when purchasing the share many years ago. When the Commonwealth Bank was floated in 1991, its shares each cost $5.40. In the last 12 months, the dividend per share has been $4.21. Thus, the dividend yield is 5% on the current share price, but 78% when calculated on the share’s original cost. A zero-taxed investor would also have benefited by $1.80 a share in the past year from the franking credit, giving a dividend plus franking yield of 111% on the price many (patient) investors would have paid.


Don Stammer has been involved with investments since the early 1960s including senior executive positions in Deutsche Bank and ING. These days, in his semi-retirement, he’s an adviser to Altius Asset Management and Stanford Brown Financial Advisers and he contributes a fortnightly column on investments for The Australian. The views expressed in this article are his own.

  •   27 April 2017
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Should you bank on the Westpac buy-back?

An easy fix for Dick Smith’s franking problem

Why high-dividend investing deserves another look

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.