If you had told me a year ago that the United States would be waging an intractable war in the Middle East, oil prices would rise to more than $100 a barrel, interest rates would be moving sharply higher, and inflation would be running well above 3%, my forecast for the US economy would have been gloomy to say the least.
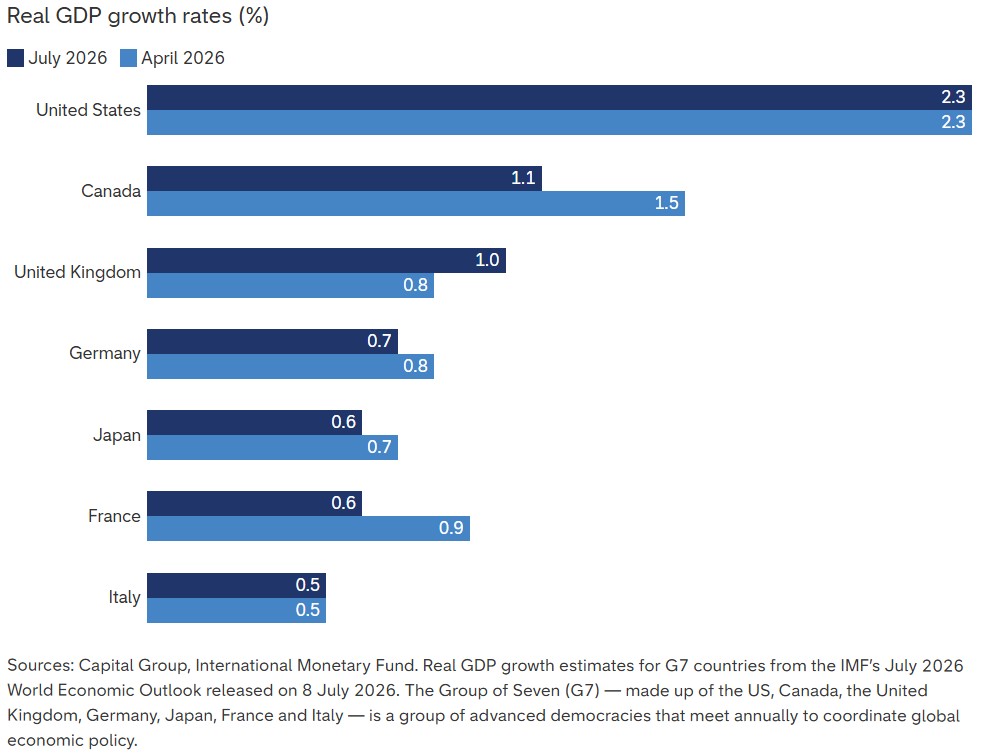
Yet here we are with consensus GDP growth estimates above 2%, significantly higher than developed-market peers around the world. And, in my estimation, the consensus data is too low. Based on my research, I see the US economy growing at a rate of 2.5% to 3% this year and next, thanks to a stronger-than-expected labour market, healthy consumer balance sheets and massive corporate spending on artificial intelligence.
US economic growth is outpacing other developed nations
What explains the remarkable resilience of the US economy? There are many reasons but, in my view, these are the three primary drivers:
1. The US labour market is defying expectations
The latest US jobs report, released on 4 September, was nothing short of a blockbuster. The US economy added 162,000 jobs in August, three times higher than consensus estimates, with the largest gains coming in leisure and hospitality, government, education and healthcare. The jobs report was so unexpectedly strong that it helped change expectations for US monetary policy. Accelerating job growth and higher inflation were two of the key factors that convinced the US Federal Reserve to raise interest rates on 16 September — the first hike in more than three years.
A healthy labour market is important because, even at a more modest average of 75,000 new jobs a month, the additional income that brings to the US economy is substantial. If you do the maths, it translates into consumer spending growth of roughly 2% on an annualised basis, which is pretty good relative to history, particularly at a time when elevated inflation is straining household budgets.
US job creation is bouncing back after a period of weakness
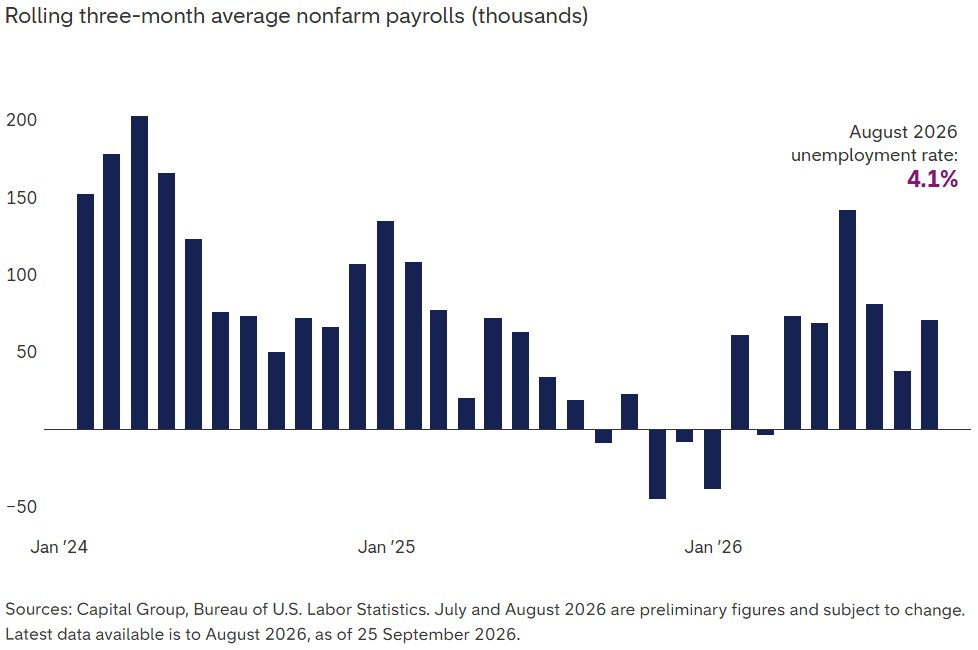
A growing labour market also reinforces the view that the Fed probably can afford to raise interest rates without hurting employment. It means Fed officials can refocus their attention on fighting inflation, which is now running hot at 3.4%, well above the Fed’s 2% target. The US unemployment rate, meanwhile, remains at 4.1%, which is widely considered full employment. If these trends continue, we should expect a few more Fed rate hikes in the months ahead. The US economy is most likely strong enough to handle it.
2. Consumer balance sheets are healthy despite higher inflation
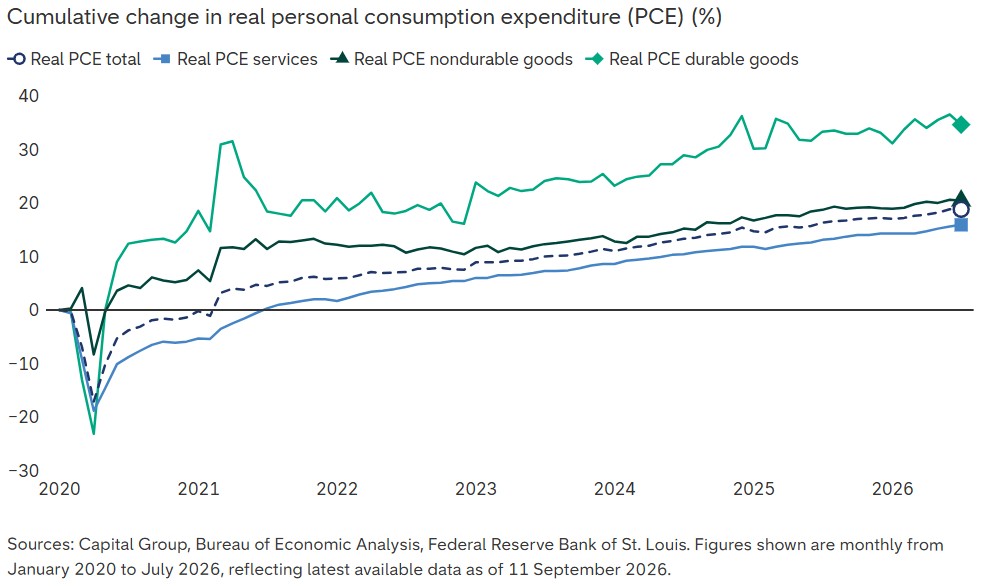
US consumer balance sheets are holding up well in the face of mounting inflationary pressures. Wage growth has remained steady at an annualised rate of 3.7% to 4.1% as of August 2026, generally outpacing inflation. So, even with higher-than-usual inflation, American consumers have managed to stay in relatively good shape, and their spending activity shows it. We have seen weakness among low-income households hard hit by rising energy prices, but middle- and high-income groups appear to have adjusted to the shock and made up the difference.
This trend is attributable to several factors, including rising stock market wealth — particularly in 401(k) accounts — appreciating home values, the recovering job market, higher tax refunds and various other government stimulus measures. For most American consumers, they simply do not see a reason to pull back. US consumer spending rose by 0.2% last month to a record high of $16.8 trillion, exceeding consensus forecasts, according to the Commerce Department.
Consumers are continuing to spend in the face of higher prices
Consumer sentiment, in contrast, remains negative. That is to be expected when you consider the cumulative price increases that US consumers have absorbed since the COVID-19 pandemic. Prices have soared roughly 30% over the past six years, as measured by the US Consumer Price Index. By comparison, from 2012 to 2019, prices rose about 14%. There is probably no scenario where consumers are going to be happy about such a rapid rise. Beyond that, I tend to give less weight to consumer sentiment surveys than hard economic data.
3. The AI-related spending surge is unprecedented
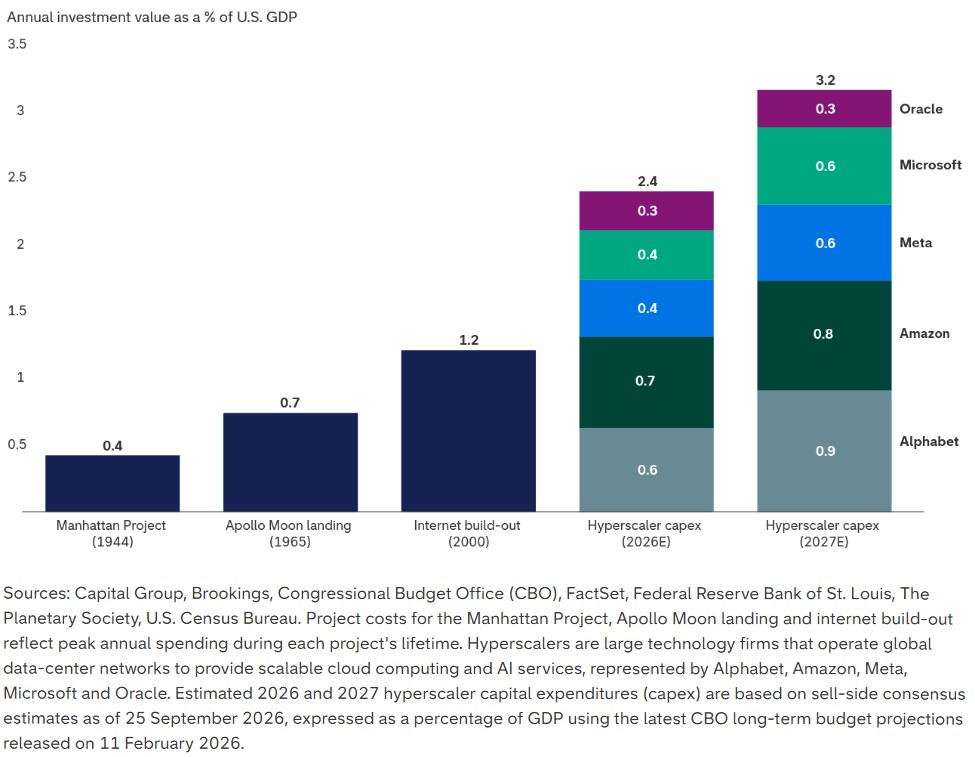
The sheer scale of AI-related spending is like nothing we have seen before. Most of the capital expenditures — an estimated $800 billion this year — are going toward the construction of massive AI data centres and related projects across the United States. Despite a mounting political backlash, there appears to be no slowdown. On the contrary, AI-related spending estimates have been revised upward on numerous occasions. I expect upward revisions in 2027 and 2028, as well.
That adds a great deal of fuel to the US economy. Moreover, I don’t think we are measuring the impact of the AI boom properly. It could take years for economists to devise an accurate way to measure this rapidly growing segment. It is just an educated guess, but I think we may be underestimating GDP growth by 0.5 to 1 full percentage point. How do you measure every instance someone uses an AI token to build a more efficient financial model in a fraction of the time it takes a human to do it? A decade from now, we may find that 4% to 5% growth is a more accurate measurement of what we are experiencing today. Going back to the dot-com era, we have often struggled to measure the economic benefit of bits of data zipping around the world.
In addition, it is clear that the giant technology companies spending most of this money view it as existential. The so-called hyperscalers — Amazon, Alphabet, Meta, Microsoft and Oracle — are among the most profitable companies in the world, and they are engaged in an epic race for AI supremacy. Given how high the stakes are, I do not see any of them slowing down anytime soon.
AI spending spree dwarfs some of the largest endeavors in history
What does this mean for US stock prices?
Over long periods of time, US stocks tend to rise along with a solid, growing economy. There are four economic cycles: early, mid-, late and recession. I believe the US economy is currently at mid-cycle, which generally bodes well for stock prices. Double-digit returns are common in a mid-cycle environment, and that is about where we are right now — with the S&P 500 Index up 14.1% on a year-to-date basis, and up 18.6% over the past 12-month period, as of 25 September. My outlook becomes more cautious as we approach a late cycle economy, which I believe may surface sometime in 2028.
There are certainly risks to this optimistic outlook, including further escalation of the Iran war, additional increases in oil prices, sharply higher interest rates, and the possibility that AI will not produce the return on invested capital companies expect. Any of these could reverse the favourable investment environment of the past few years.
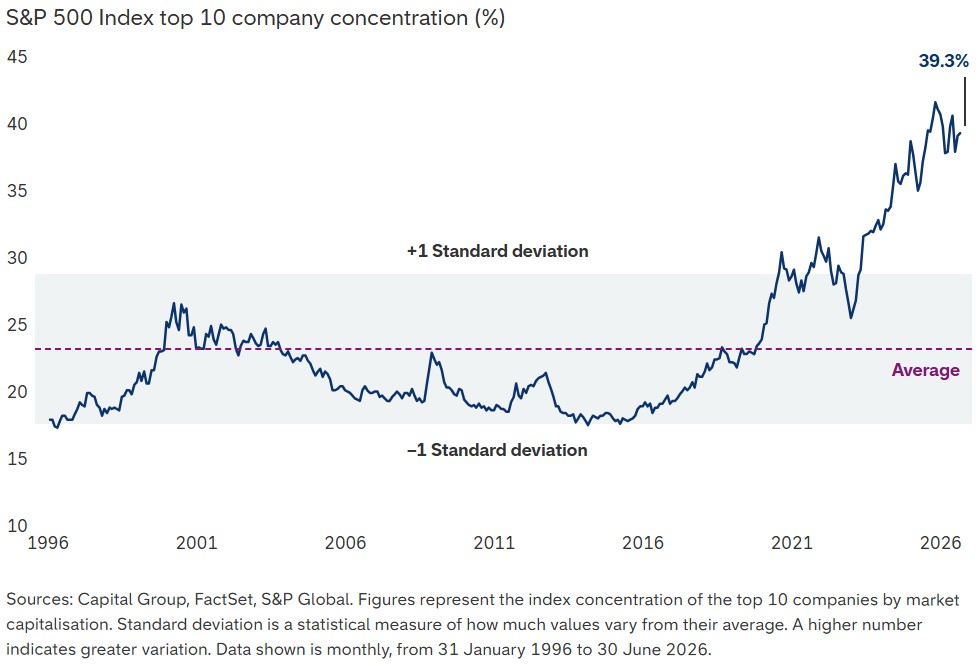
That said, the economy and the markets are not the same thing. Today’s high levels of market concentration have embedded risks, which is why it’s important to consider a broadly diversified investment approach that goes beyond top-heavy indexes.
A handful of stocks are driving a highly concentrated market
For now, I feel comfortable with the view that the US economy will continue to surprise on the upside, thanks to a strong labour market, healthy consumer spending and an AI revolution that could produce significantly higher growth rates in the years ahead.
Jared Franz is a US-based economist at Capital Group, a sponsor of Firstlinks. Statements attributed to an individual represent the opinions of that individual as of the date published and may not necessarily reflect the view of Capital Group or its affiliates. This article contains general information only and does not consider the circumstances of any investor. Please seek financial advice before acting on any investment as market circumstances can change.
© 2026 Capital Group. All rights reserved.
For more articles and papers from Capital Group, click here.