Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 480

Why we believe bonds are now beautiful

The Reserve Bank of Australia (RBA) announced a surprise adjustment to its policy path when it reduced the pace of tightening to 0.25% after months of 0.5% increases. We applaud the RBA for moderating its pace as it should minimise the chance of over-tightening and a potential accident. Lags between policy changes and impact are approximately three months on average and the RBA increasingly acknowledges that most borrowers have still only experienced the first handful of rate hikes.

Monetary policy has reached a critical point

This new pace of rate increases represents an important stage in the tightening cycle. The RBA estimates the neutral policy setting for the Australian economy is circa 2.50%. Hence, any additional increase in the cash rate above 2.50% represents an ever-greater level of intensity applied to the economic brakes. It appears Australia is now entering the late stages of the tightening cycle.

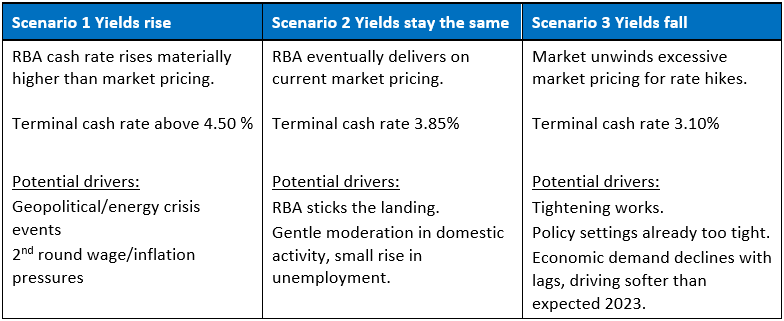
The forward-looking market impact from October’s RBA policy announcement was immediate. Prior to the RBA meeting, market pricing had the terminal cash rate in Australia circa 4.35%. This quickly came down 0.50% to 3.85%, validating our view that market expectations for policy in Australia have been too aggressive. At 3.85%, we believe market pricing remains aggressive relative to where the RBA is likely to pause.

Where to from here?

At the risk of over-simplifying, in fixed income, there are three broad scenarios:

  1. Yields rise
  2. Yields stay the same (track sideways in a range)
  3. Yields fall

What is less widely-understood is the consequences of the market already building these scenarios into existing interest rates.

Scenario 1 (yields rise) has been the experience for much of the last 12 months as markets adjusted to higher interest rates, driving negative bond returns. The chart below shows the path of the actual cash rate from 0.1% in May 2022 to the current 2.60% in October. The chart also shows that the market has already priced (projected) the cash rate will rise to 3.85% next year.
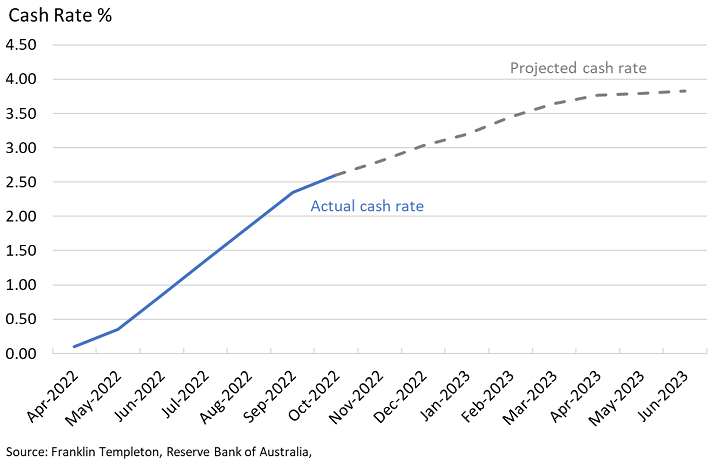
Both components – i.e. the change in actual cash rate and the market projected cash rate – are already ‘in the price’. So, for scenario 1 to have a meaningful return impact over the next 6-12 months, the market will need to be concerned that the actual cash rate will rise above market projections, above 4.0%. The tone and actions of the RBA in this past week suggest this is now a low probability scenario.

Scenario 2 (yields stay the same, track sideways in a range), suggests that with time the market projections in the above chart will be broadly met and no material adjustment in yields (higher or lower) is likely. Under this scenario, the portfolio effectively earns its yield over the next 12 months.

Our core view is that current market pricing for the terminal cash rate remains too high. We believe the actual cash cate will settle at 3.10% and scenario 3 (yields fall) is most likely over the next 6-12 months.
Tightening works

Monetary policy works with a lag and the strident leaps the RBA has taken in recent months won’t show up in behaviour and key data until the few remaining months of this year. But show up they will and that is before any further tightening that will ensure 2023 will be truly a challenging year.

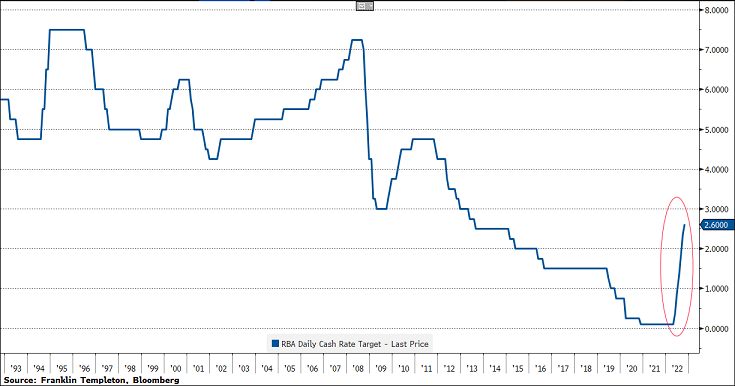
The chart below shows policy settings over the last 30 years and illustrates how sharp the current adjustment has been. The full impact of tightening has not yet been felt in the economy. It’s a bit like having six shots of vodka and suddenly you realise that you’ve drunk too much!
Some indications the worst is in the past

Our economic indicators show that momentum has turned down significantly across several indicators: namely, consumer confidence, housing (cash flows, prices, construction approvals, work done and construction materials prices), financial conditions, and trading partner growth.

Global pressures behind high inflation this year also appear to be through the worst. Global supply chains are flowing more freely with shipping costs retracing significantly lower. Commodity prices are down, and inflation expectations are contained across consumers and financial markets.

On the strong side, business sentiment remains elevated, and the labour market is tight with jobs for anyone who wants one. In fact, this is arguably the tightest labour market we have seen in 50+ years. This has translated into wages growth from the Covid lows up 2.6% so far. Looking forward, partial indicators suggest further wage increases up to the 3.50-3.75% area next year.

But, by 2H2023, labour supply will have improved substantially through an accelerated net migration program. Preliminary signs of a slowdown in job vacancies, albeit from elevated levels, are also emerging. This coincides with the lags in central bank policy, ultimately driving diminishing domestic demand from the RBA’s tightening this year, including what’s still to come.

Modelling our core view suggests that the term yields will adjust materially lower. Initially, we estimate bonds to rally in the order of 0.5%-0.75% as the excessive tightening priced in the market is unwound. The market will then take several months to assess the underlying economy after which we expect a second rally as the market begins to price for subsequent policy easing by late 2023, early 2024. 

In sum, what makes bonds beautiful is the favourable skew in return outcomes under various scenarios. We believe fixed income investment is supported by either scenario 2 (yields stay the same), or scenario 3 (yields fall). Today, we believe probabilities are skewed to these scenarios.


Chris Siniakov is Managing Director, Fixed Income at Franklin Templeton, a sponsor of Firstlinks. This article is for information purposes only and does not constitute investment or financial product advice. It does not consider the individual circumstances, objectives, financial situation, or needs of any individual.

For more articles and papers from Franklin Templeton and specialist investment managers, please click here.


  •   19 October 2022
  • 4
  •      
  •   
4 Comments
Big Mike
October 19, 2022

All I know is that fixed interest managers continue to lose money when interest rates go up and every Johnny could see this coming 18 months ago . They cannot hold the Bonds to maturity for some reason and have the balance in cash thus eliminating the capital losses. They get paid the big money either way ? Dont understand why in this market when the writing was on the wall.

Greig
October 19, 2022

Even if a manager held all the bonds to maturity (Vanguard for instance), they would still be showing losses for the past 12 months. I have been out of fixed interest for about 7 years because I thought I could see the writing on the wall. Japan has been at zero rates for nearly 30 years and yet cash/bonds have still been the best performing asset class over that period. There is very little that is obvious in financial markets without the benefit of hindsight.

James
October 19, 2022

Jack Bogel's dirty little secret about probable market movements: "Nobody knows nothing!" Fund managers love to drum up business by predicting with some authority and gravitas! Shame there's not a more public, true scorecard!

Martin
October 19, 2022

Wouldn't be surprised if bond fund managers were saying the same thing 18 months ago. I know I was "advised" to tip a fairly large sum (for me) into a global bond fund about then. Even given scenario 2 or 3 occurs, it will be a long time before my defensive investment gets back to par


Leave a Comment:

RELATED ARTICLES

Which asset class in Australia offers the best value now?

Reserve Bank has both a date and data dilemma

Shares rebound on hopes of war ending, but stalemate the likely outcome

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.