Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 403

The fascinating bank hybrid journey of the last year

This time last year we were scrambling to figure out how best to explain the hybrid market’s performance. From 2 March 2020 to the close of business on 23 March 2020 the broader market, as represented by Elstree Hybrid Index declined by a material 15.7%. By the month’s end the index had managed to claw its way back such that it was down, over the month, by a relatively pedestrian 6.2%.  

Wow, that was some 12-month period!

On the 12-month anniversary of the biggest drawdown since the GFC, it's an interesting time to reflect.

Most risk markets, hybrid markets included, bottomed on or around 23 March before rallying strongly on coordinated government and central bank intervention. The rally that ensued produced extraordinary return outcomes – we might even go so far as to say ‘ridiculous’ return outcomes.

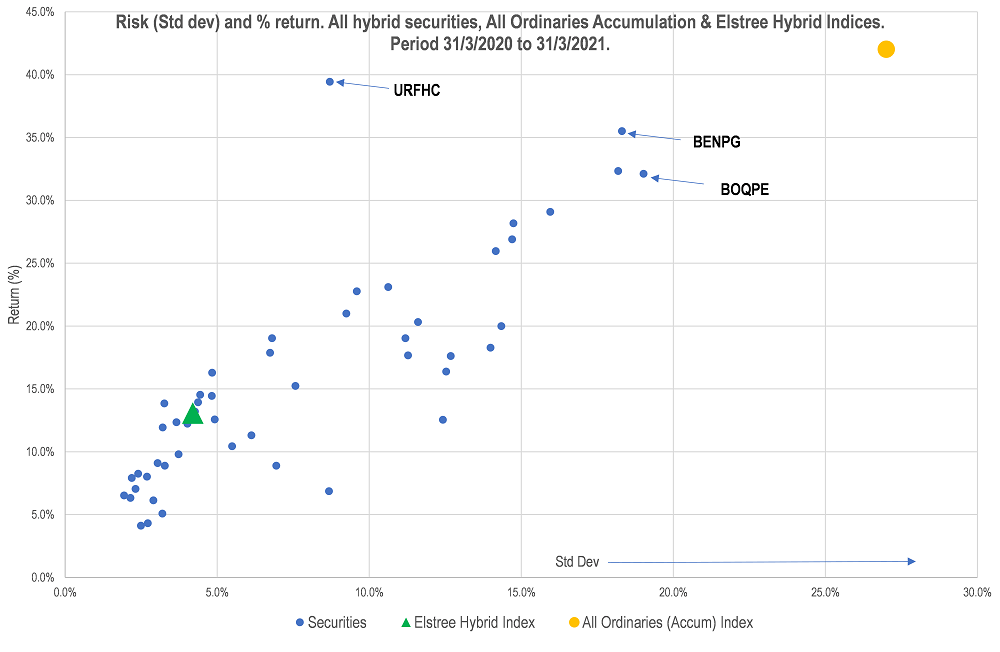
Over the year to end 31 March 2021 the hybrid market as represented by the Elstree Hybrid Index returned 13.32%. This compares (now) with an expected hybrid market return of cash +3% (i.e. 3%). Investors certainly should not expect those hyper-inflated return outcomes again any time soon. The chart below shows the returns on individual hybrids (vertical axis) and the standard deviation (horizontal axis). We’ve also shown the Elstree Hybrid and All Ordinaries Accumulation indices.
What does this tell us?

  • Almost everything did well but the non-major bank hybrids did best with many producing around 30% returns.
  • Volatility was relatively subdued given the return outcomes. Pretty much everything went up in a straight line.
  • If you produced the same chart but started it at 28 February 2020, you would get different outcomes with hybrids still producing an acceptable return and risk profile with equities displaying more risk and less return.

What were the fascinating days?

  • The hybrid market’s worst day was a -6.1% decline on 23 March 2020. This was the day that the NAB announced that they were converting their maturing NABPB hybrid into shares via a VWAP (Volume Weighted Average Price) agreement with UBS. This ‘option’ is present in almost every hybrid document and it allows the issuer to raise $1-$2 billion of equity capital without the usual complexities. In this instance investors received their $100 (for the note) and then the NAB ‘on sells’ the note to UBS and NAB then issues ordinary shares to UBS. The market erroneously interpreted the cleansing statement issued by NAB to mean that the maturing NABPB holders would not get $100 and instead would receive NAB shares at an estimated 30% premium to the last traded price. Investors sold everything including equities. NABHA fell 12%, AMPPB fell 11% while the broader equity market declined by just under 6%.
  • The hybrid market’s best day was a mere two days later on 25 March 2020 resulting in a 3.8% return. This was the day investors realised they had sold for the wrong reasons and bought back the stocks they had sold. The market had a net gain of 3.9% for that week.

Probably the biggest lesson is that many investors don’t understand the structures, and in a crisis, everyone panics first and thinks later.


Campbell Dawson is an Executive Director of Elstree Investment Management, a boutique fixed income fund manager. The Elstree Enhanced Income Fund delivered 18.7% in the 12 months to end March 2021. This article is general information and does not consider the circumstances of any individual investor.


  •   14 April 2021
  • 2
  •      
  •   

RELATED ARTICLES

What now for SMSFs and hybrids?

The end of the strong US dollar cycle

Today’s case for floating rate notes

banner

Most viewed in recent weeks

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.