The four horsemen of the Apocalypse are Conquest, War, Famine, and Death. Artificial intelligence (AI) has ‘Conquered’; in the Middle East, ‘War’ is underway and could take years to resolve, and changes afoot in enterprise-level AI spending would be akin to ‘Famine’ for AI hyperscalers that have spent trillions on scaling out the technology. All that awaits is the ‘Death’ of the AI bubble.
Consider these four observations:
- 23 May 2026, Rapid Response Podcast: Uber COO, Andrew Macdonald, says spending Uber’s entire AI budget in the first four months of the year, primarily on Claude Code, has not produced “more useful consumer features”. In other words, drawing a link between spend and revenue “is not there yet.” Meanwhile, Uber CEO, Dara Khosrowshahi said AI “Token Maxxing” has no connection to delivering genuinely valuable products.
- 29 May 2026, Axios reports that an AI consultant revealed that a client company had forgotten to set a usage cap on employee licenses for Claude, resulting in a US$500 million expenditure in just one month. As AI costs surge, businesses are feeling financial pressure, and senior execs are publicly questioning the yield from AI spend.
- Ask a Large Language Model (LLM) to answer a question, and about 100 tokens are used for every 75 words produced. But ask an AI agent to create a worker to follow a competitor’s announcements, to track property opportunities or to alert a fund manager to a new investment theme, and, according to analysis from U.S.-based SemiAnalysis, almost 100,000 tokens will be used even before an answer is generated.
- As quickly as AI has emerged, customer AI experimentation (which has triggered massive revenue increases for the likes of Anthropic, largely from token-maxxing leaderboards at Meta and Amazon) is now giving way to budgeted and considered token usage. The dreamers and builders are moving out, and the accountants are moving in. Enterprises that earlier embraced AI at all costs are publicly adopting a return on investment (ROI) lens.
Worryingly, this shift is occurring just as stock markets have turned hyper-exponential, and Private Equity valuations also reflect maximum hype.
Figure 1. General purpose technology (GPT) booms and busts, Gartner’s hype cycle
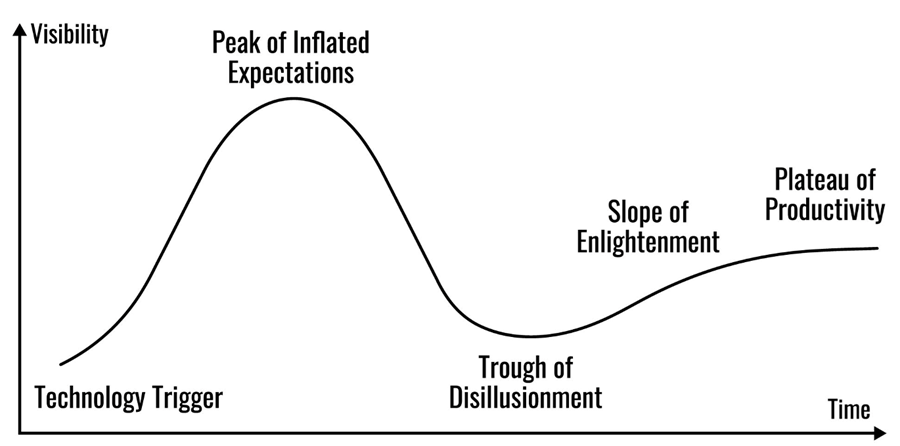
Source: Gartner
According to reports, NVIDIA CEO Jensen Huang, speaking at a recent employee meeting, discussed staff concerns about ‘running AI intensively every day, merely wasting tokens on superficial efforts without boosting productivity.’ His response is perhaps telling; He noted that when people encounter any new technology or tool, the initial period of experimentation or “unfamiliarity” produces “imperfect usage”, adding, what matters is taking the first step to embrace new technologies – “It’s fine to waste a little money, but never waste time.”
Huang’s words reflect the certainty of AI’s adoption, which I don’t contest. But will enough revenue from AI customers be generated to provide a reasonable return on the investment made by hyperscalers and data centre developers?
It would be unusual if this time is different
It might be worth remembering the words of journo Derek Thompson, who wrote in his November 4 newsletter, AI Could Be the Railroad of the 21st Century. Brace Yourself, “Memories are short, and prudence and natural risk aversion are no match for the dream of getting rich on the back of a revolutionary technology that “everyone knows” will change the world.
The global railway mania of the 1800s bankrupted thousands of investors, wiped out hundreds of companies, but left nations with a rail network that powered a century of industrial dominance. Similarly, when the fibre-optics/internet/broadband boom of 1999 crashed in early 2000, it vaporised $US5 trillion in market value, but it also laid the wiring on which the Internet Age was built. Similar stores can be told about the electricity bubble, aviation, broadcast radio and automobiles.
Indeed, about three-quarters of General-Purpose-Technology (GPT) booms share a similar pattern of colossal over-investment, financial carnage through creative destruction, then lower prices and decades of productivity gains assembled on the residual infrastructure.
At the core of today’s AI boom is a GPT on the scale of electricity or the internet, and the infrastructure being built will support decades of economic activity. And unlike the Dot.Com bubble, the investment isn’t billions in speculative debt being loaned to ‘pre-revenue’ companies with no path to profitability. This time, the investment is coming (so far) mostly from companies with strong balance sheets. But beyond that core, the classic signs of every bubble are on display.
It would be unusual, given the great enthusiasm or hype, the high asset prices, the overbuilding, the uncertainty of future demand, indeed, the many elements that conform to past bubbles, if this boom doesn’t also conform to the pattern illustrated in Figure 1. it would indeed be a first.
Roger Montgomery is the Founder and Chairman of Montgomery Investment Management, a leading Australian boutique investment manager, which offers investors access to high-quality investment strategies in Australian equities, private credit, and digital assets. Roger is widely regarded as one of Australia’s most insightful professional investors and thought leaders. He is the author of the best-selling investment guide Value.able and is a well-known media personality in Australia.
For more information, contact the Montgomery Team on (02) 8046 5000 or [email protected] or visit www.montinvest.com
Sign up for Roger’s insights at www.rogermontgomery.com
This article is for general information only and does not consider the circumstances of any individual.