Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 594

How can you not be bullish the US?

Great question. (Wish I had asked it 5, 10 or 15 years ago.) Near-term – say, to pick a random date, until 20 January 2025 – momentum may stay with the US trade. But beyond that US equities look rich, their EPS advantage may narrow, rising bond yields may crimp returns, and the next cycle – which isn’t here yet – should favour other markets. I’m not convinced Trump can offset these headwinds.

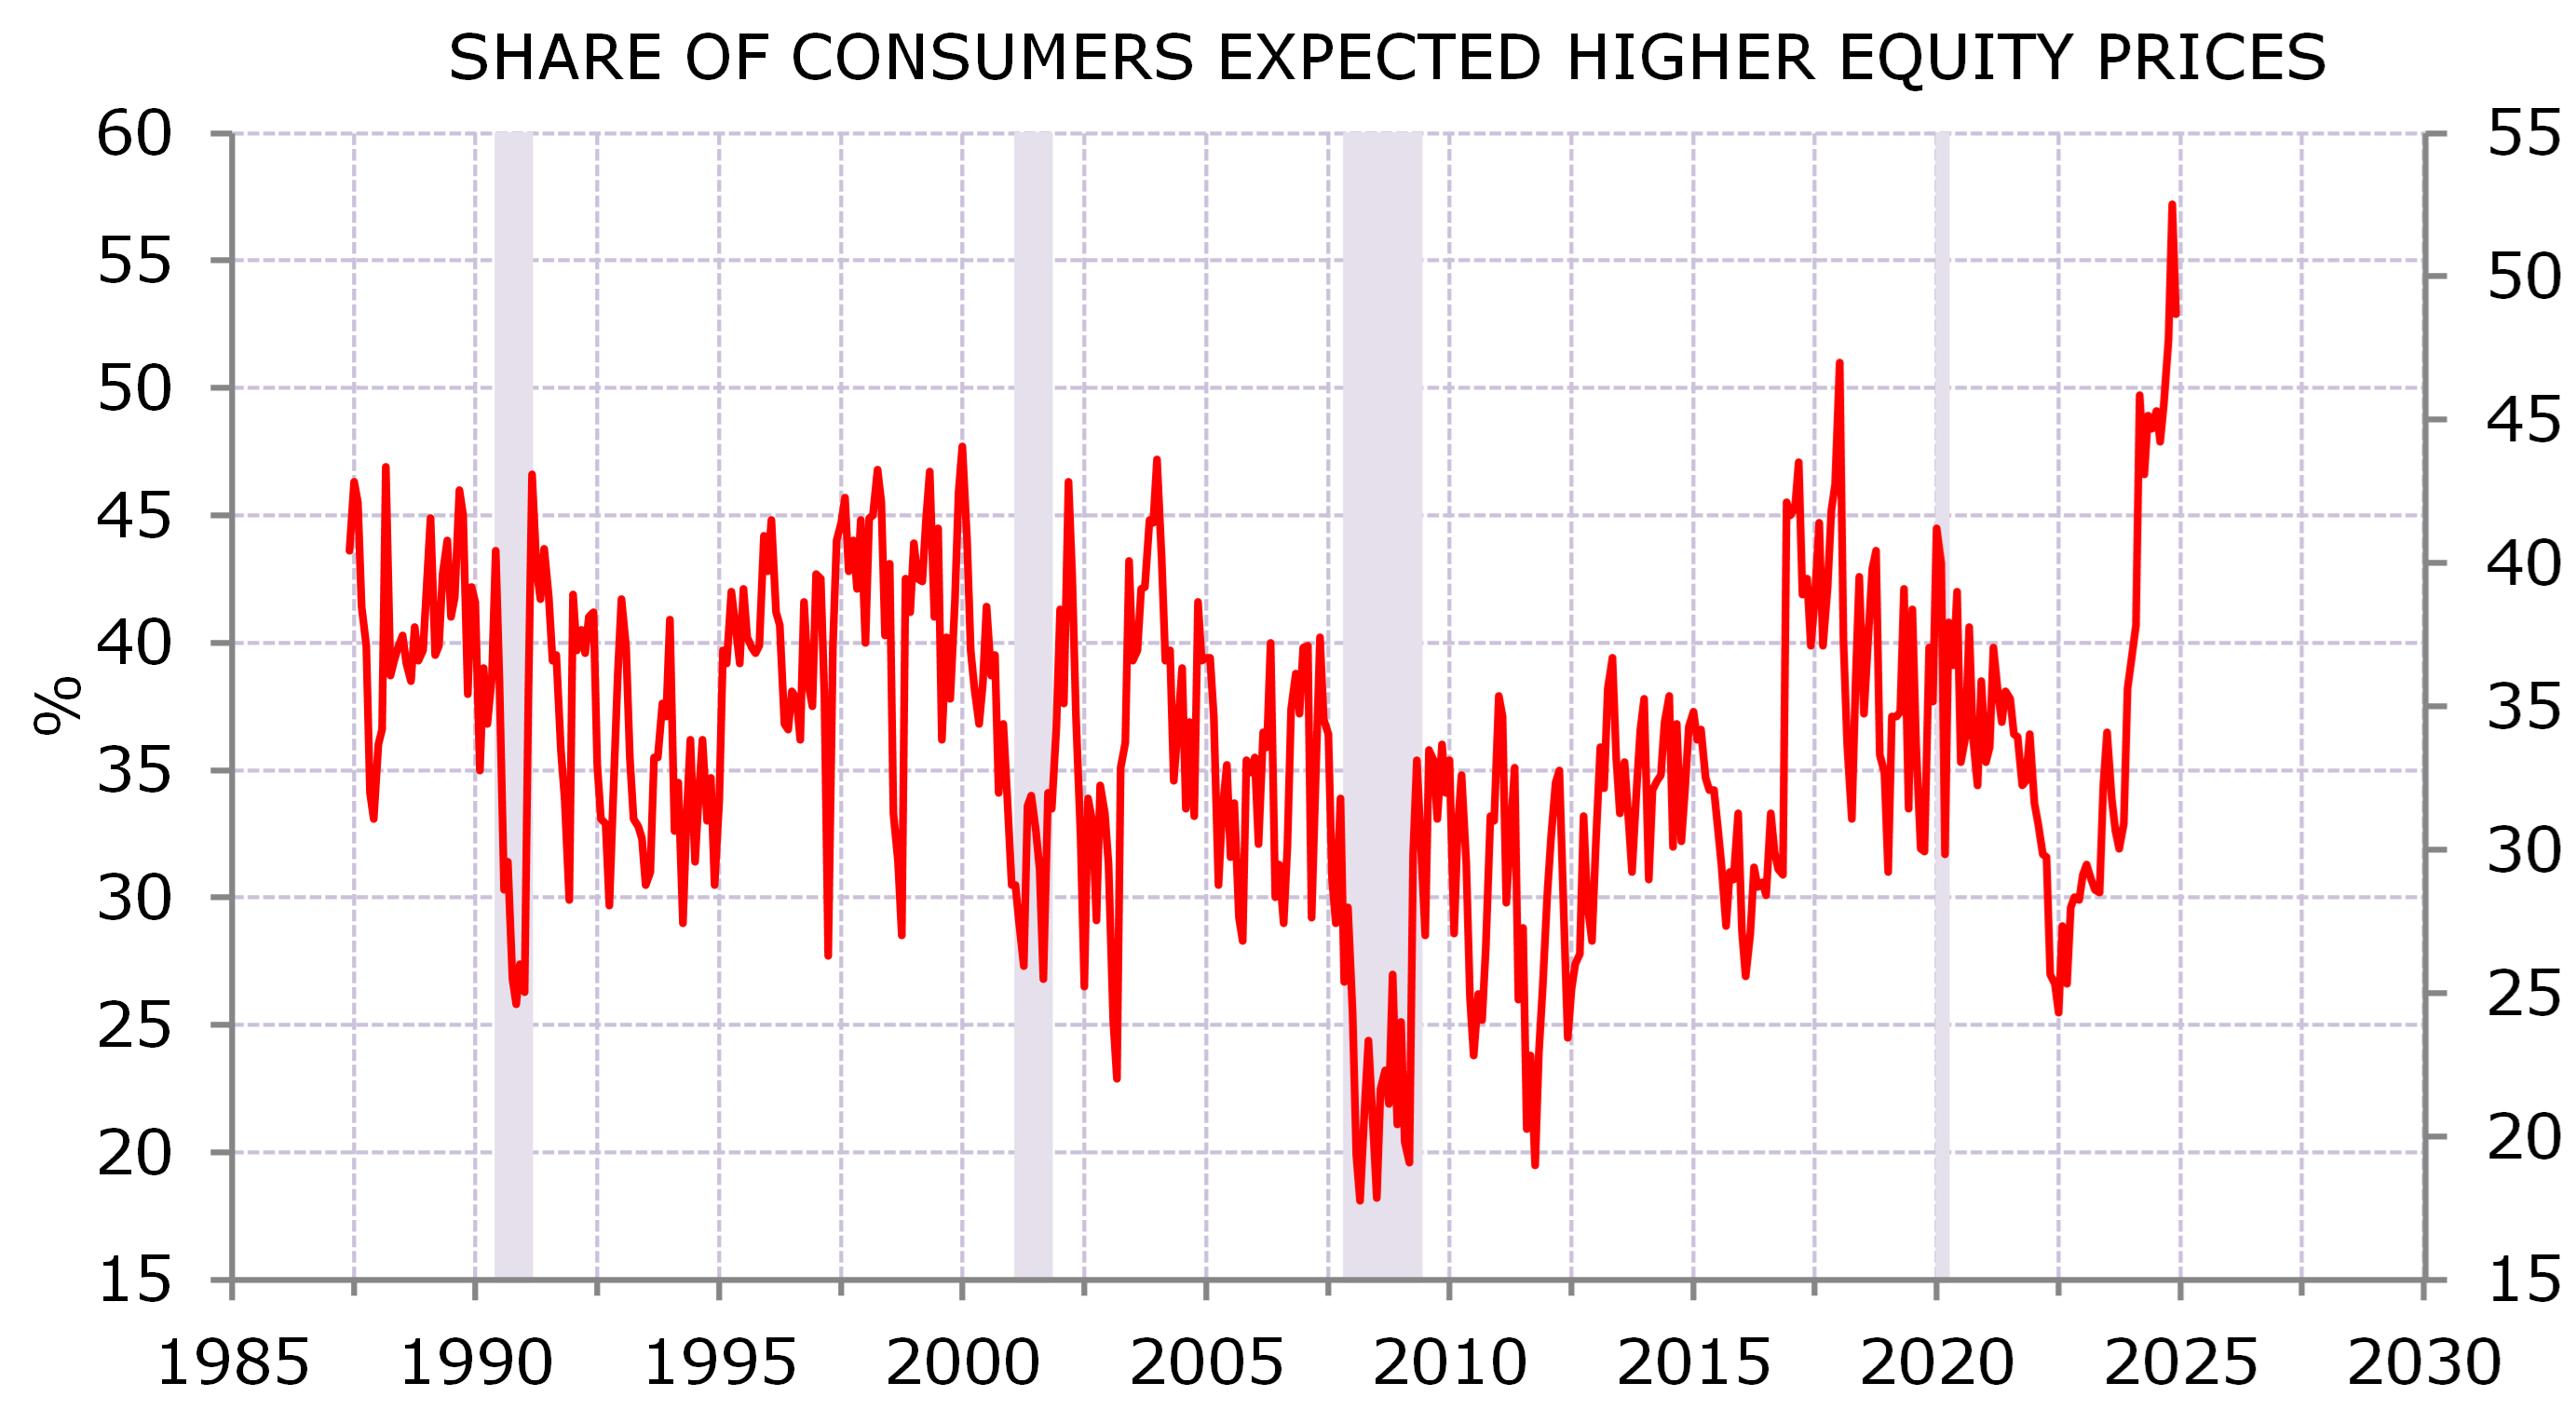
Who’s not bullish the US? Exhibit 1 – nicked from Torsten Slok – shows the share of US consumers expecting higher equity prices is now at an all-time high. The AAII survey is also high (not at a record). So is Mike Hartnett’s BoA fund manager survey. I don’t know when this will peak. The bulls can project their hopes and dreams on the President-elect until inauguration day (20 January 2025).

Exhibit 1: Everyone (almost) expects higher equity prices
Source: Conference Board, NBER; Minack Advisors (thanks Torsten Slok)

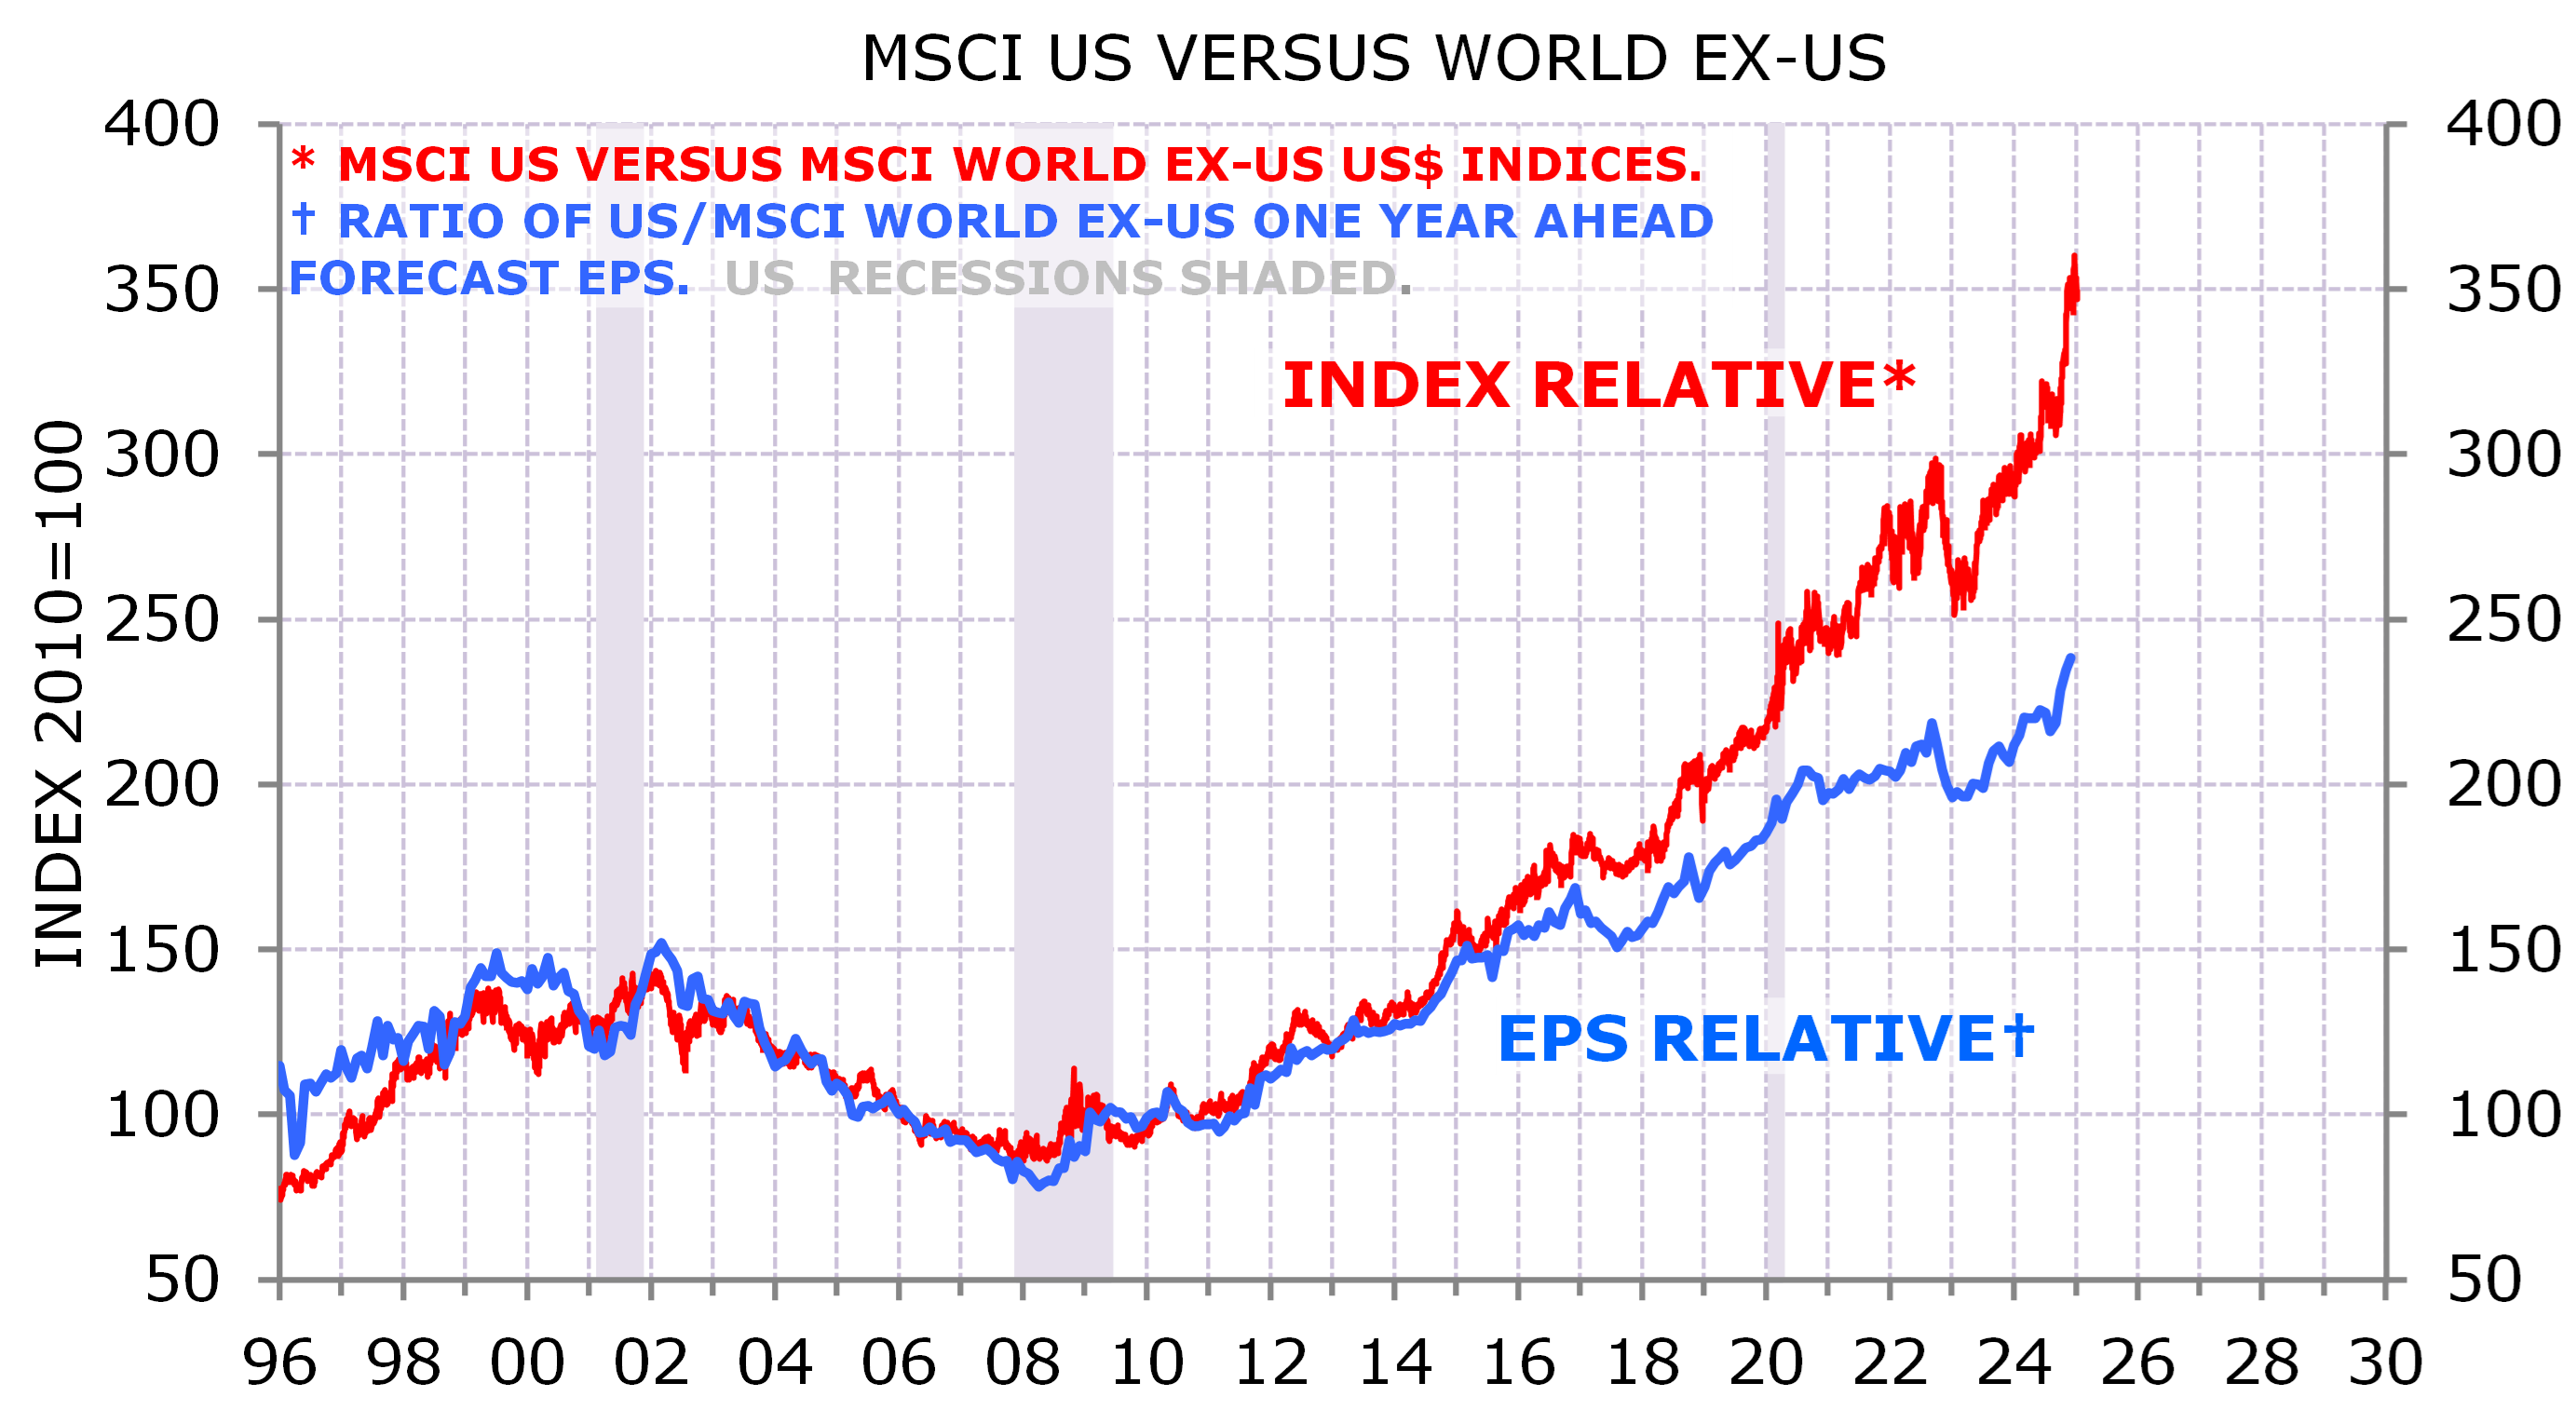
The key to US exceptionalism has been earnings out-performance. Since 2016 EPS-driven out-performance has been enhanced by the US market rerating versus other markets (Exhibit 2).

Exhibit 2: Earnings drove most (not all) US exceptionalism
Source: MSCI, IBES/DataStream, NBER; Minack Advisors

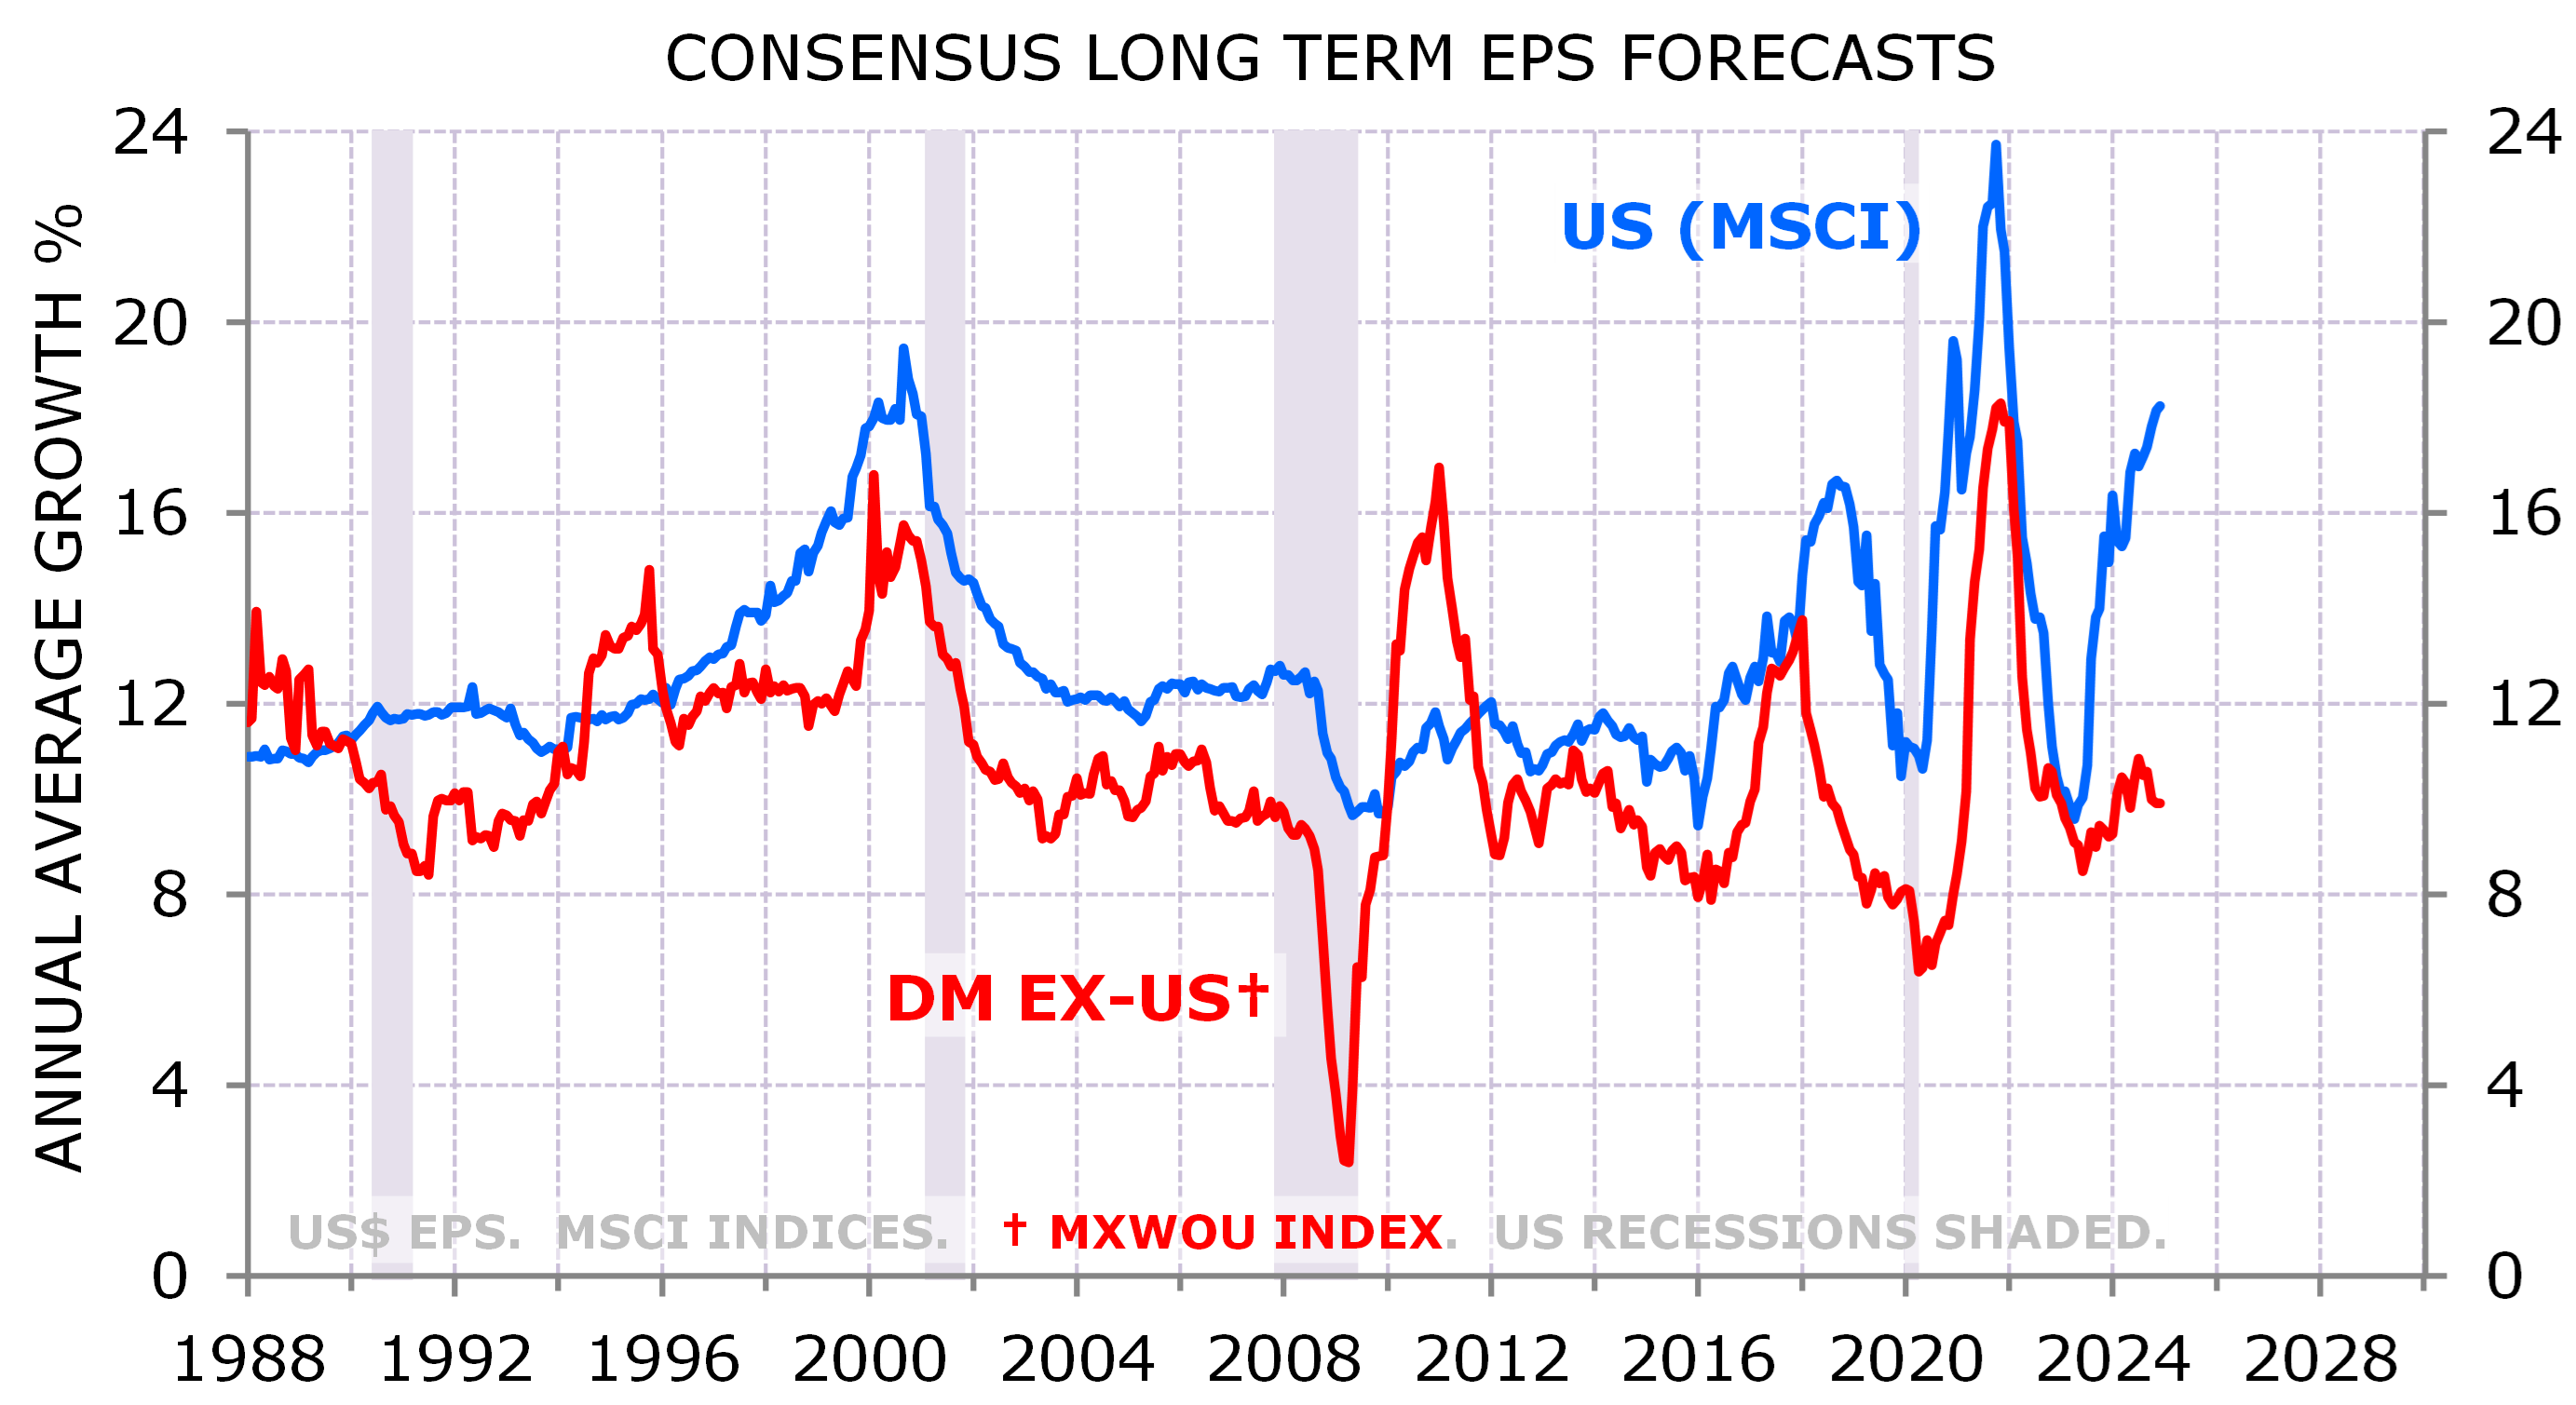
That rerating coincided with a widening gap between US and non-US long-run EPS forecasts. The gap between expected US and non-US long-run EPS growth is now at 8%, a record, excluding 4 months in the GFC (Exhibit 3).

Exhibit 3: US exceptionalism is for the long run
Source: MSCI, IBES/DataStream, NBER; Minack Advisors

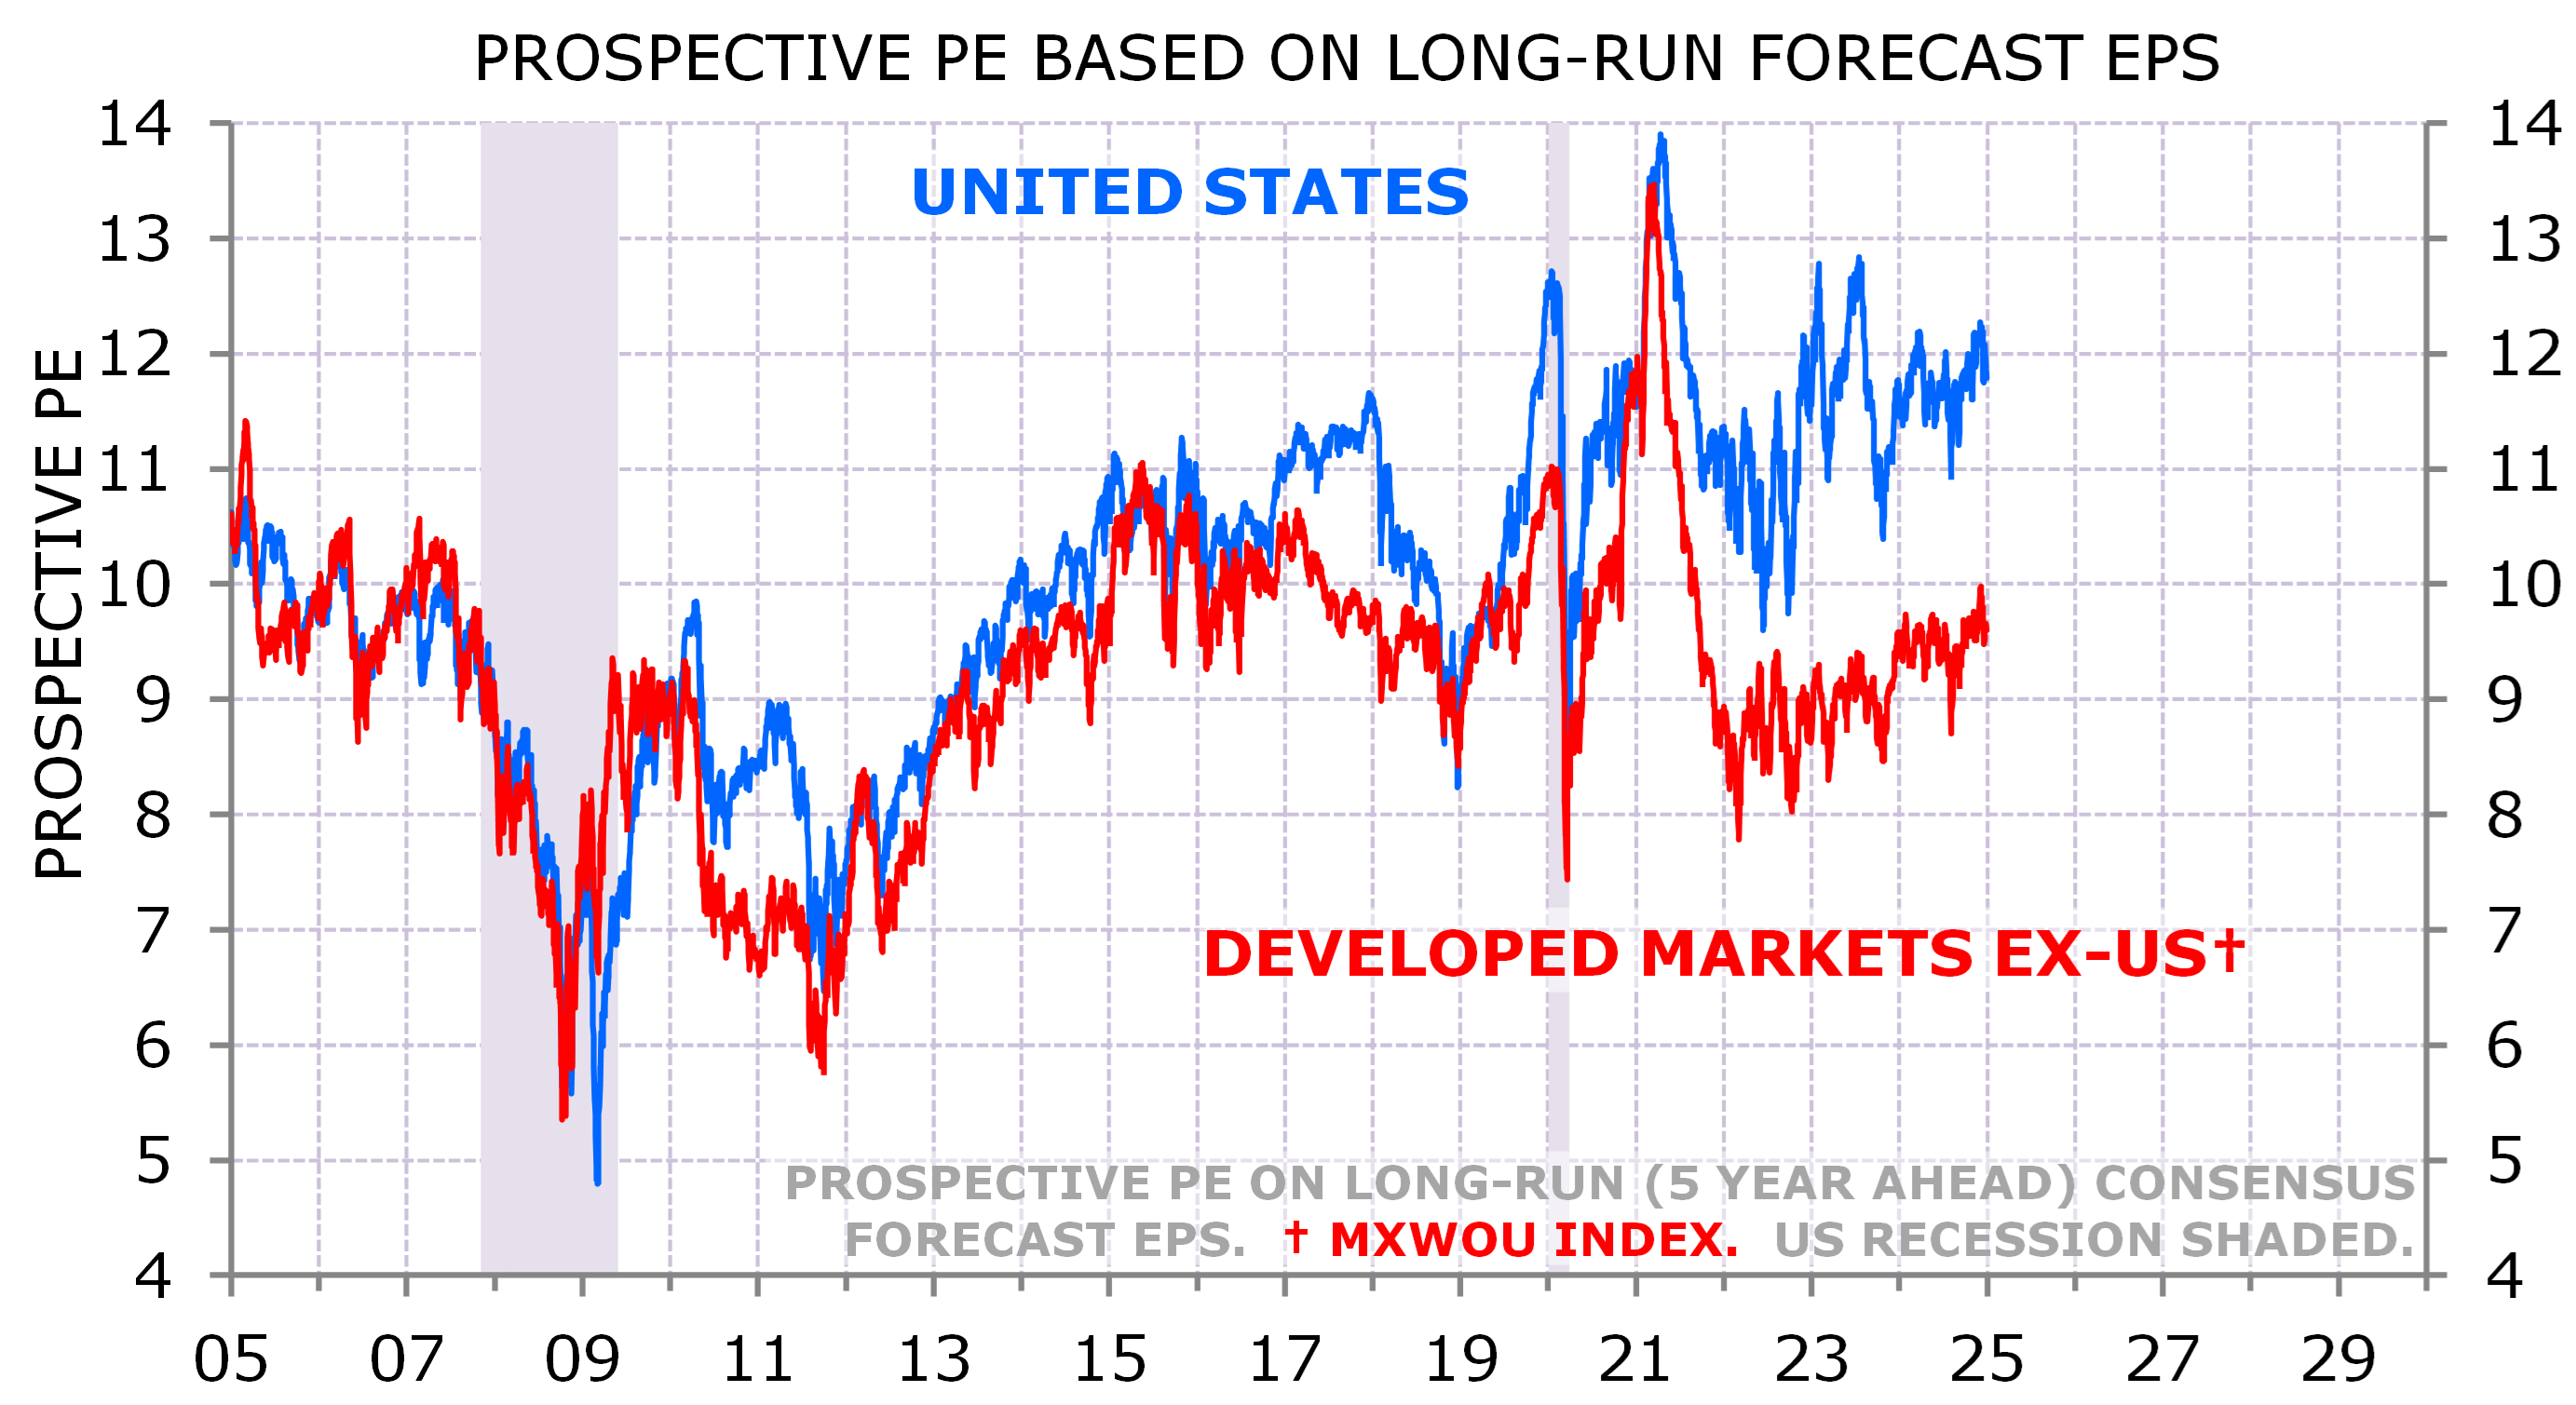
I doubt that US EPS growth will outpace the rest of the world’s by that much. Even if it does, that superior EPS growth is now in the price. Exhibit 4 shows prospective PE ratios based on long-run (5 years ahead) EPS level. The US market has re-rated relative to other developed markets even after taking into account its faster long-run EPS growth.

Exhibit 4: US is expensive even with exceptional EPS
Source: MSCI, IBES/DataStream, NBER; Minack Advisors

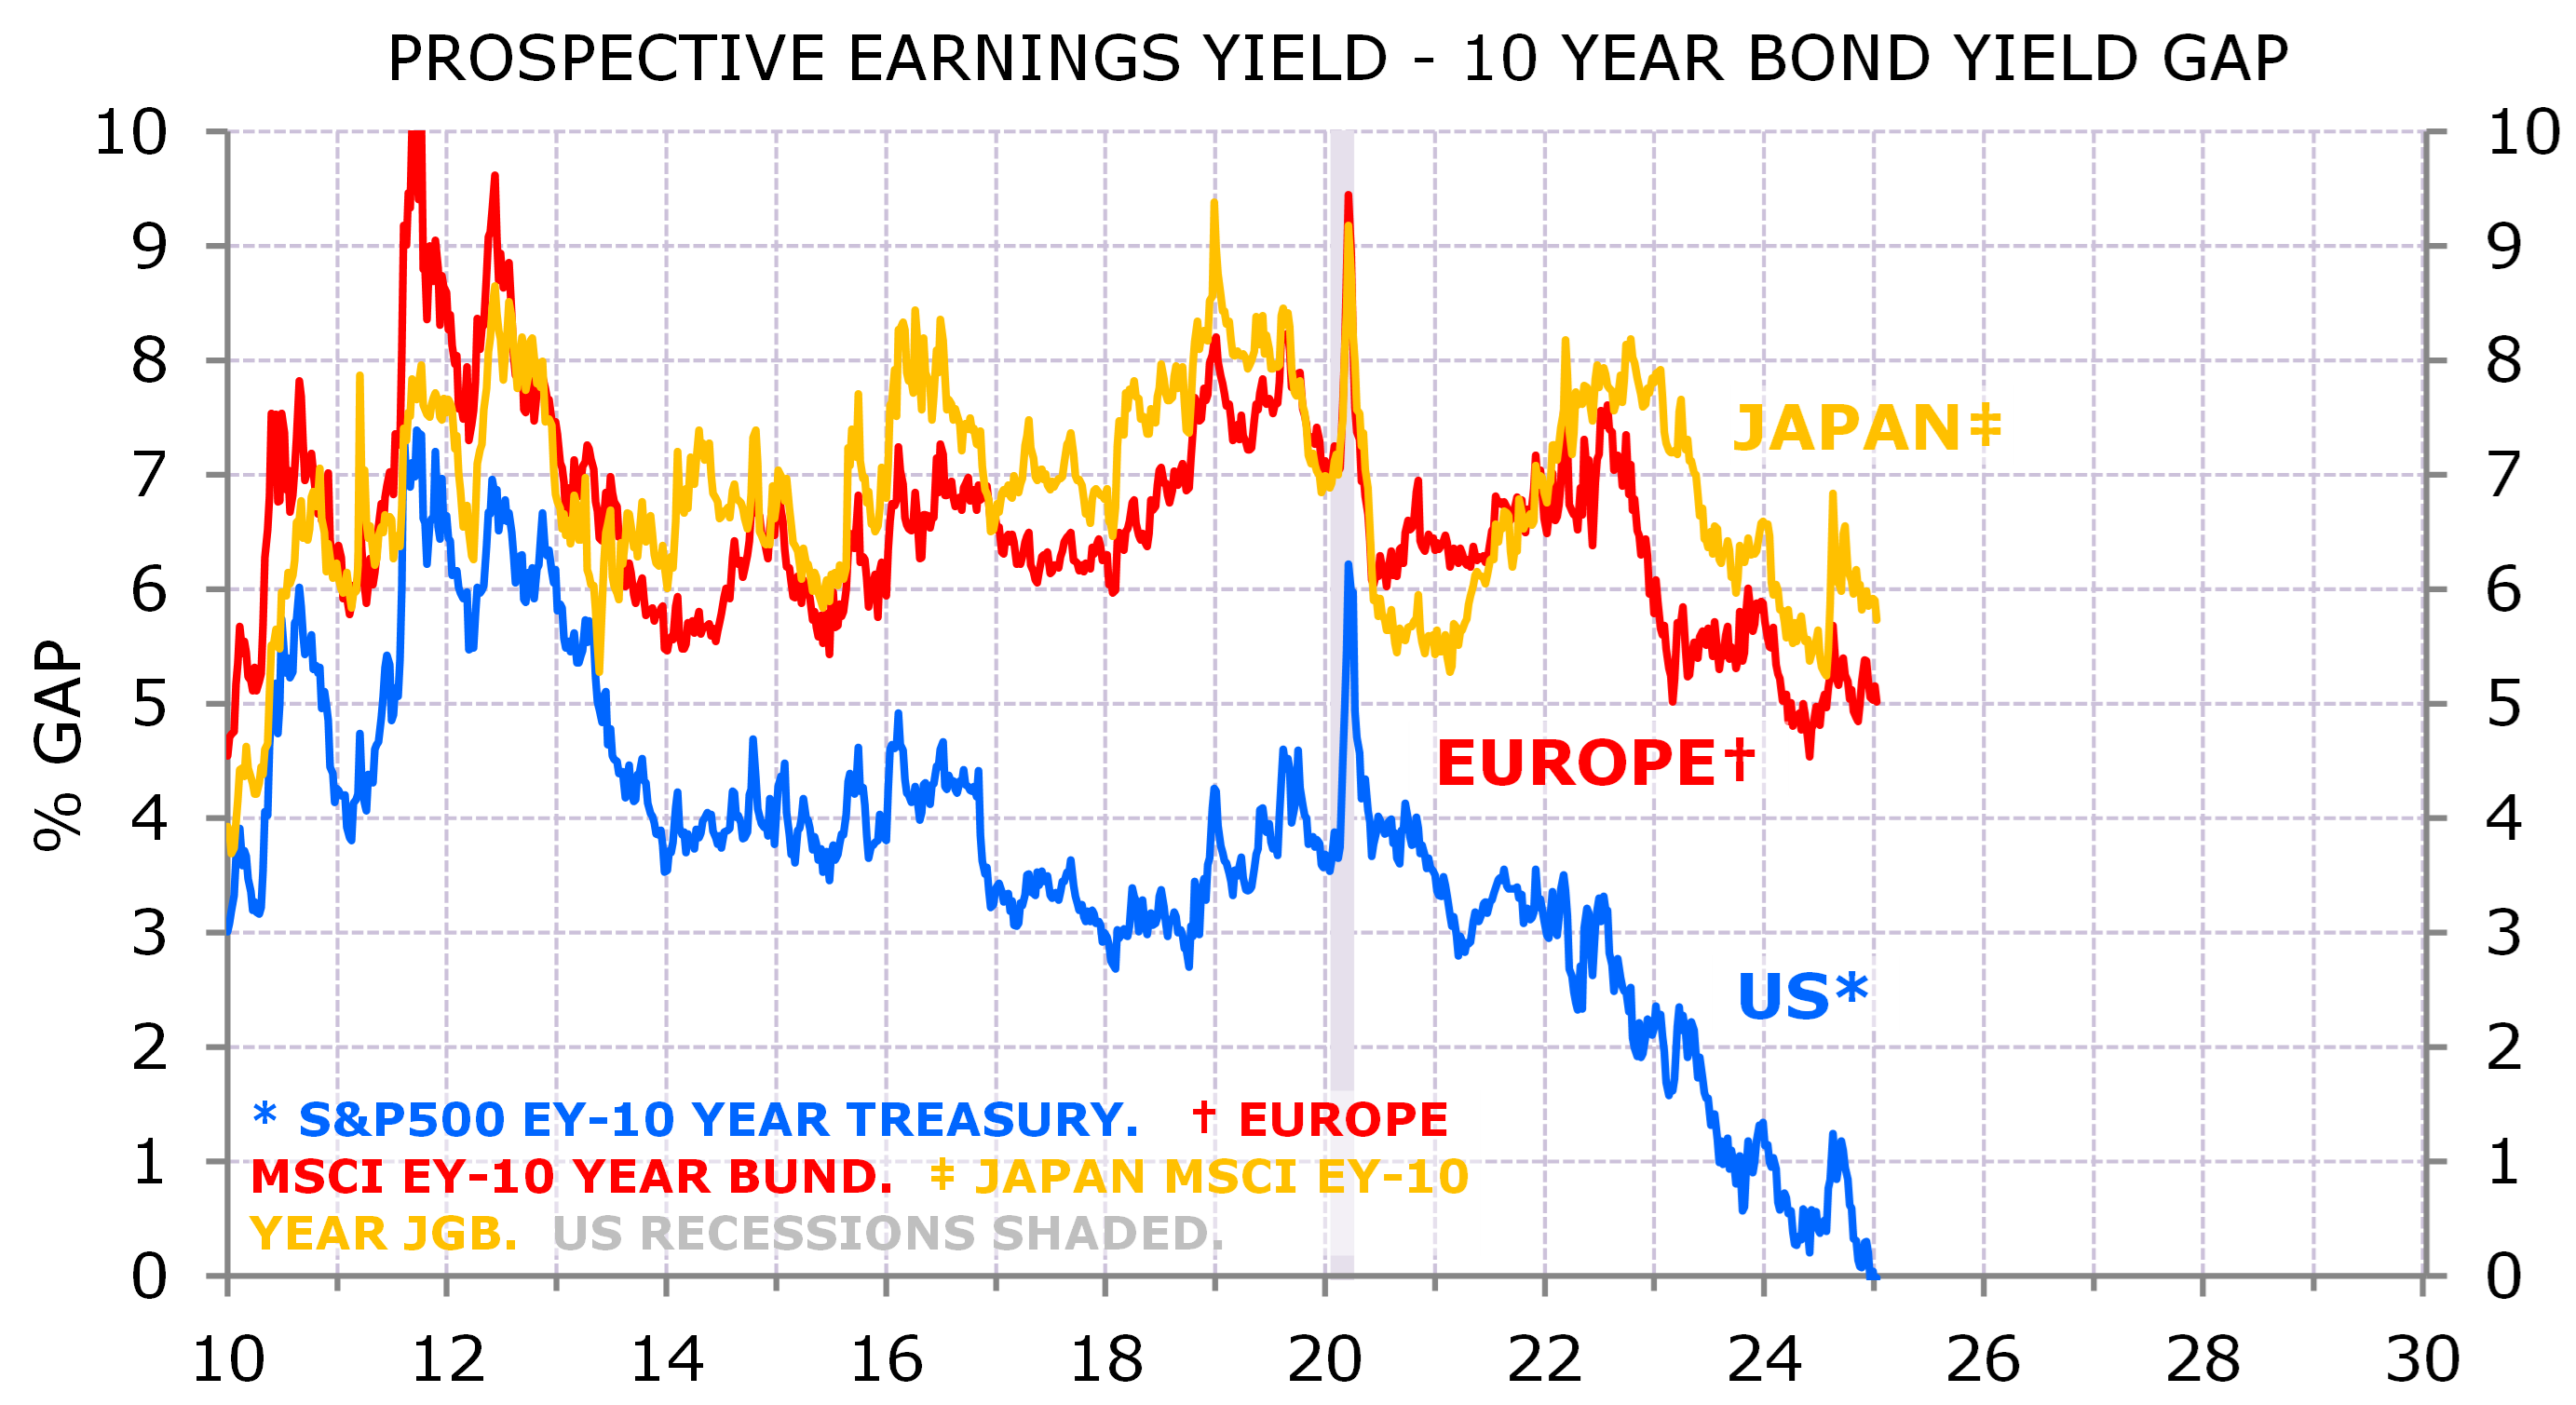
The US market is expensive relative to its own history, relative to other markets and relative to other assets. The prospective earnings yield is now in line with the 10-year Treasury yield (Exhibit 5). I expect 10-year yields to breach 5% in 2025. At some stage rising long-end yields will be a headwind for equity valuations in the US.

Exhibit 5: Exceptional valuation at risk from bond yields
Source: MSCI, IBES/DataStream, Bloomberg, NBER; Minack Advisors

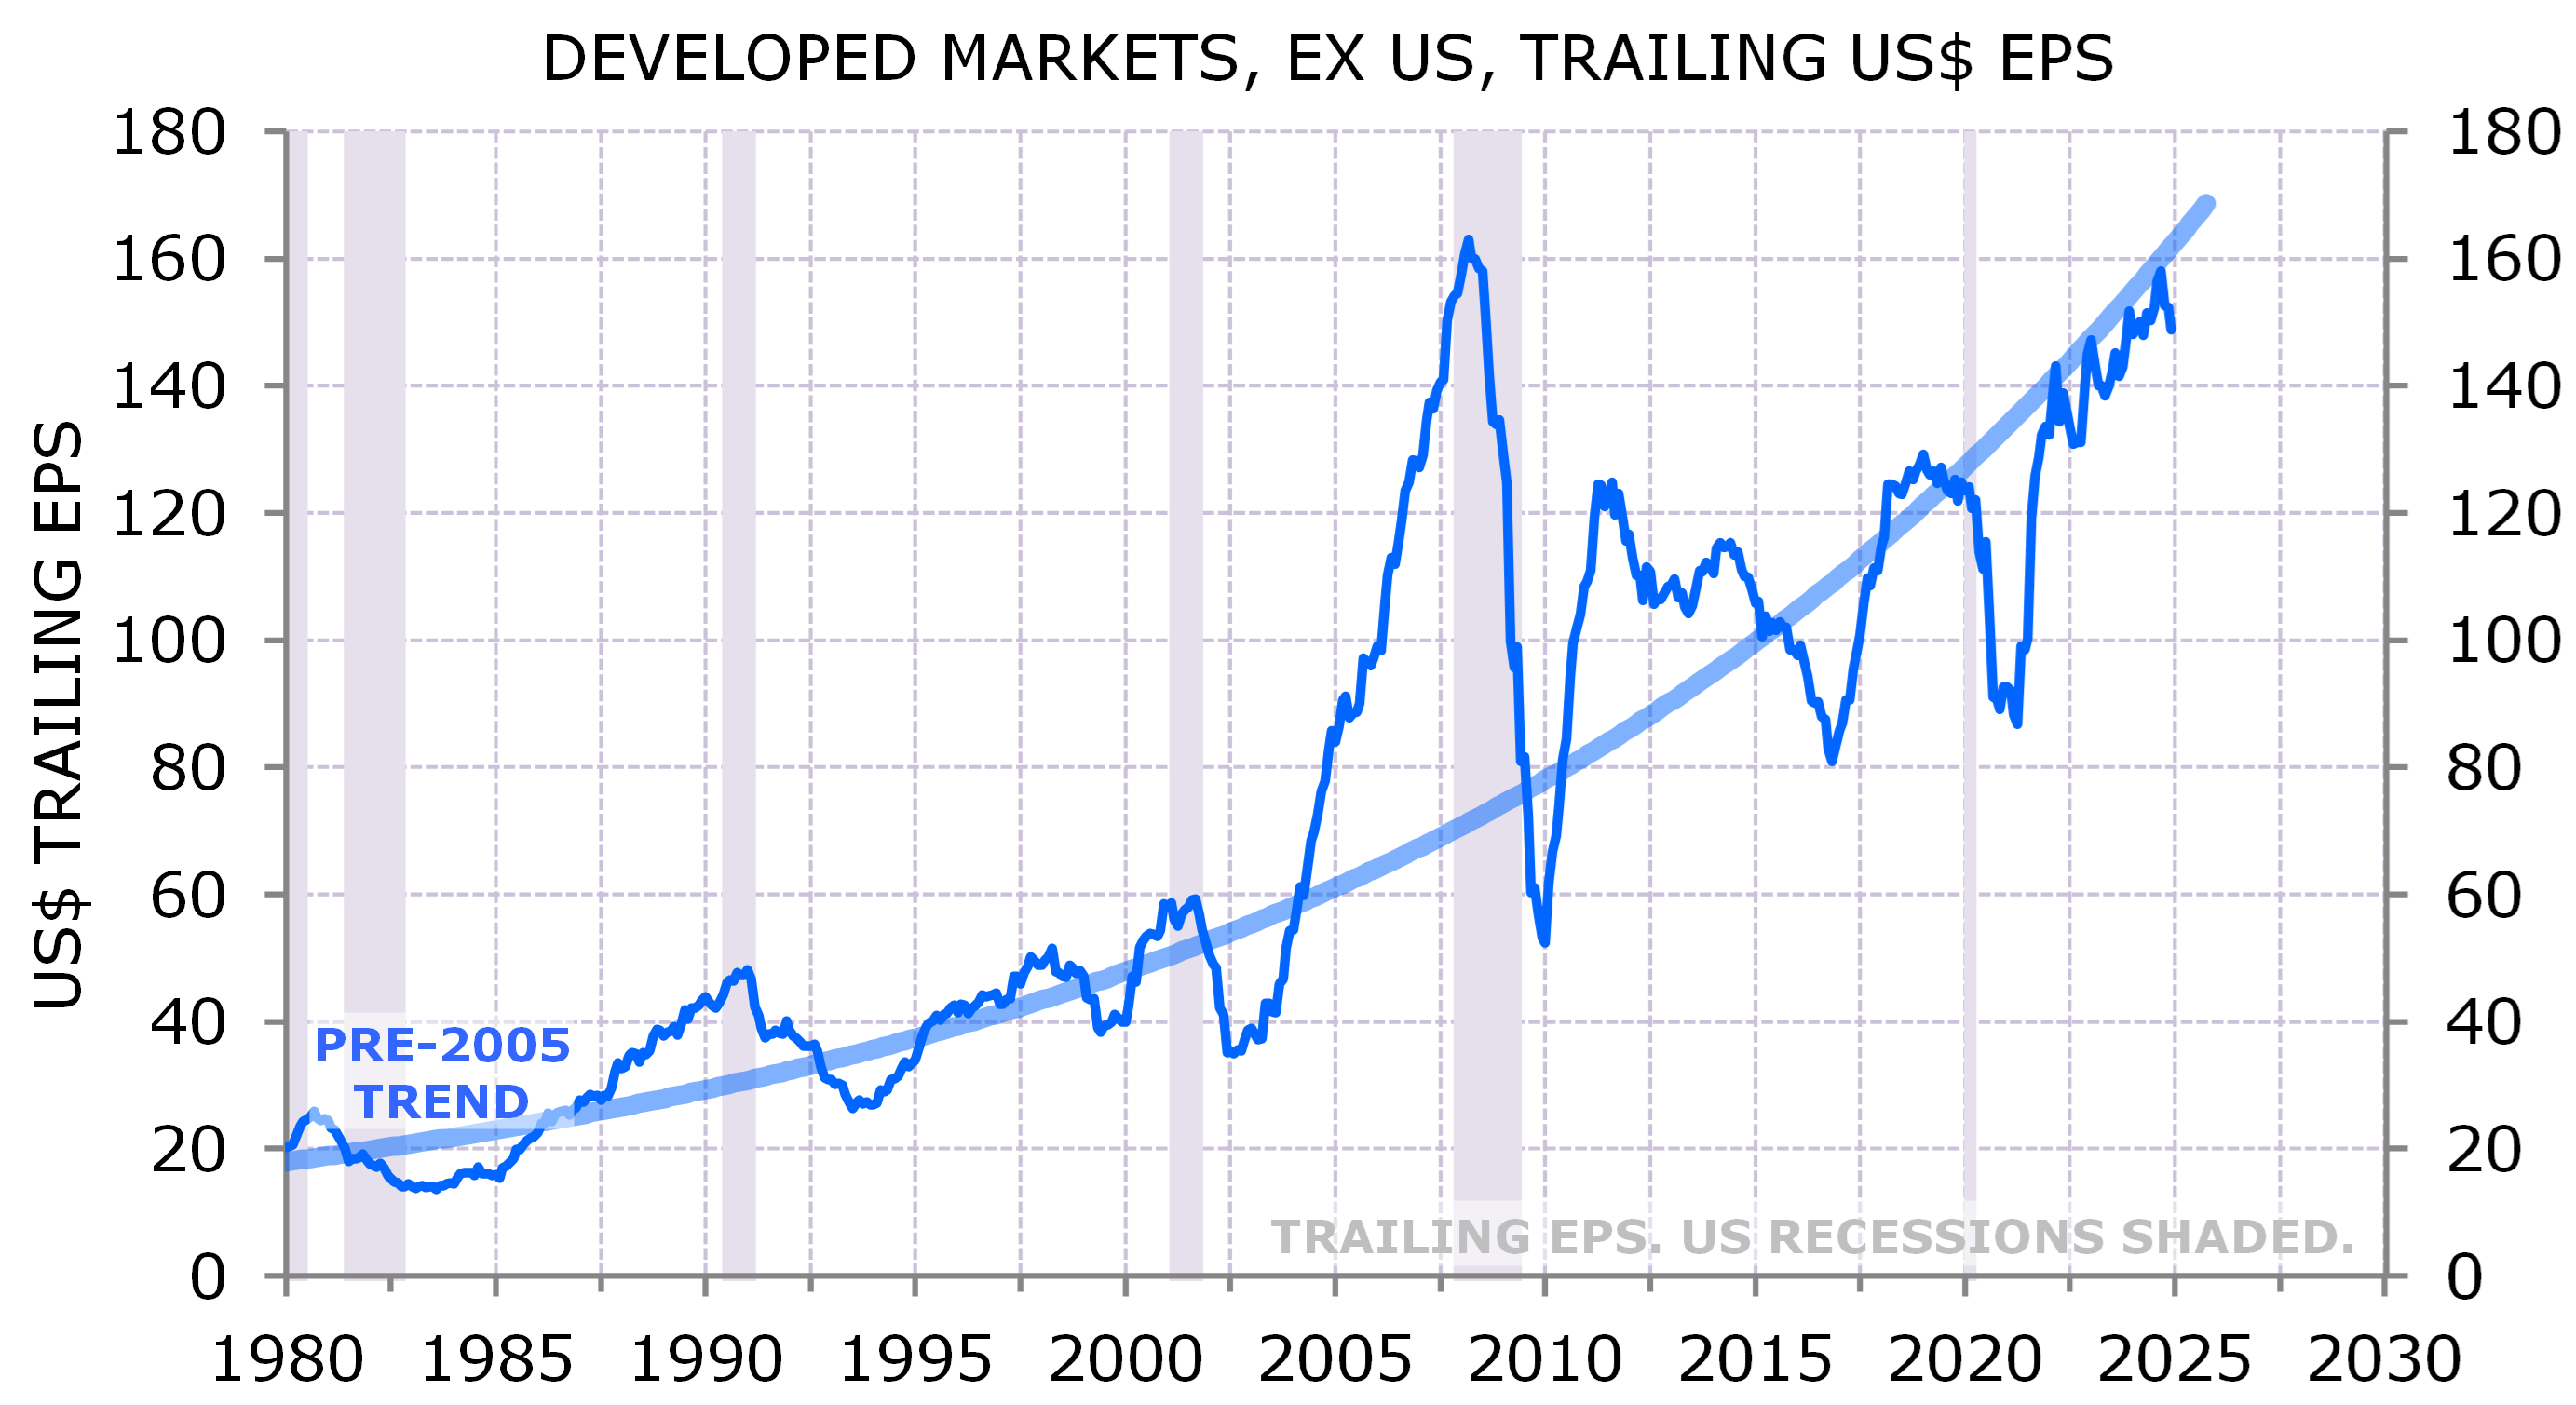
The post-GFC cycle saw unusually strong US EPS growth and unusually weak EPS growth outside the US. Why will that change? The principal reason why ex-US EPS has been so weak since the GFC is that earnings had ballooned to unsustainable levels before the GFC. EPS in US$ terms quadrupled between 2002 and 2008. That EPS bubble bursting kept EPS weak for several years. However, rest of world EPS is now back on its pre-bubble trend and has resumed normal growth through the past few years (Exhibit 6).

Exhibit 6: The rest of the world back on EPS growth trend
Source: MSCI, NBER; Minack Advisors

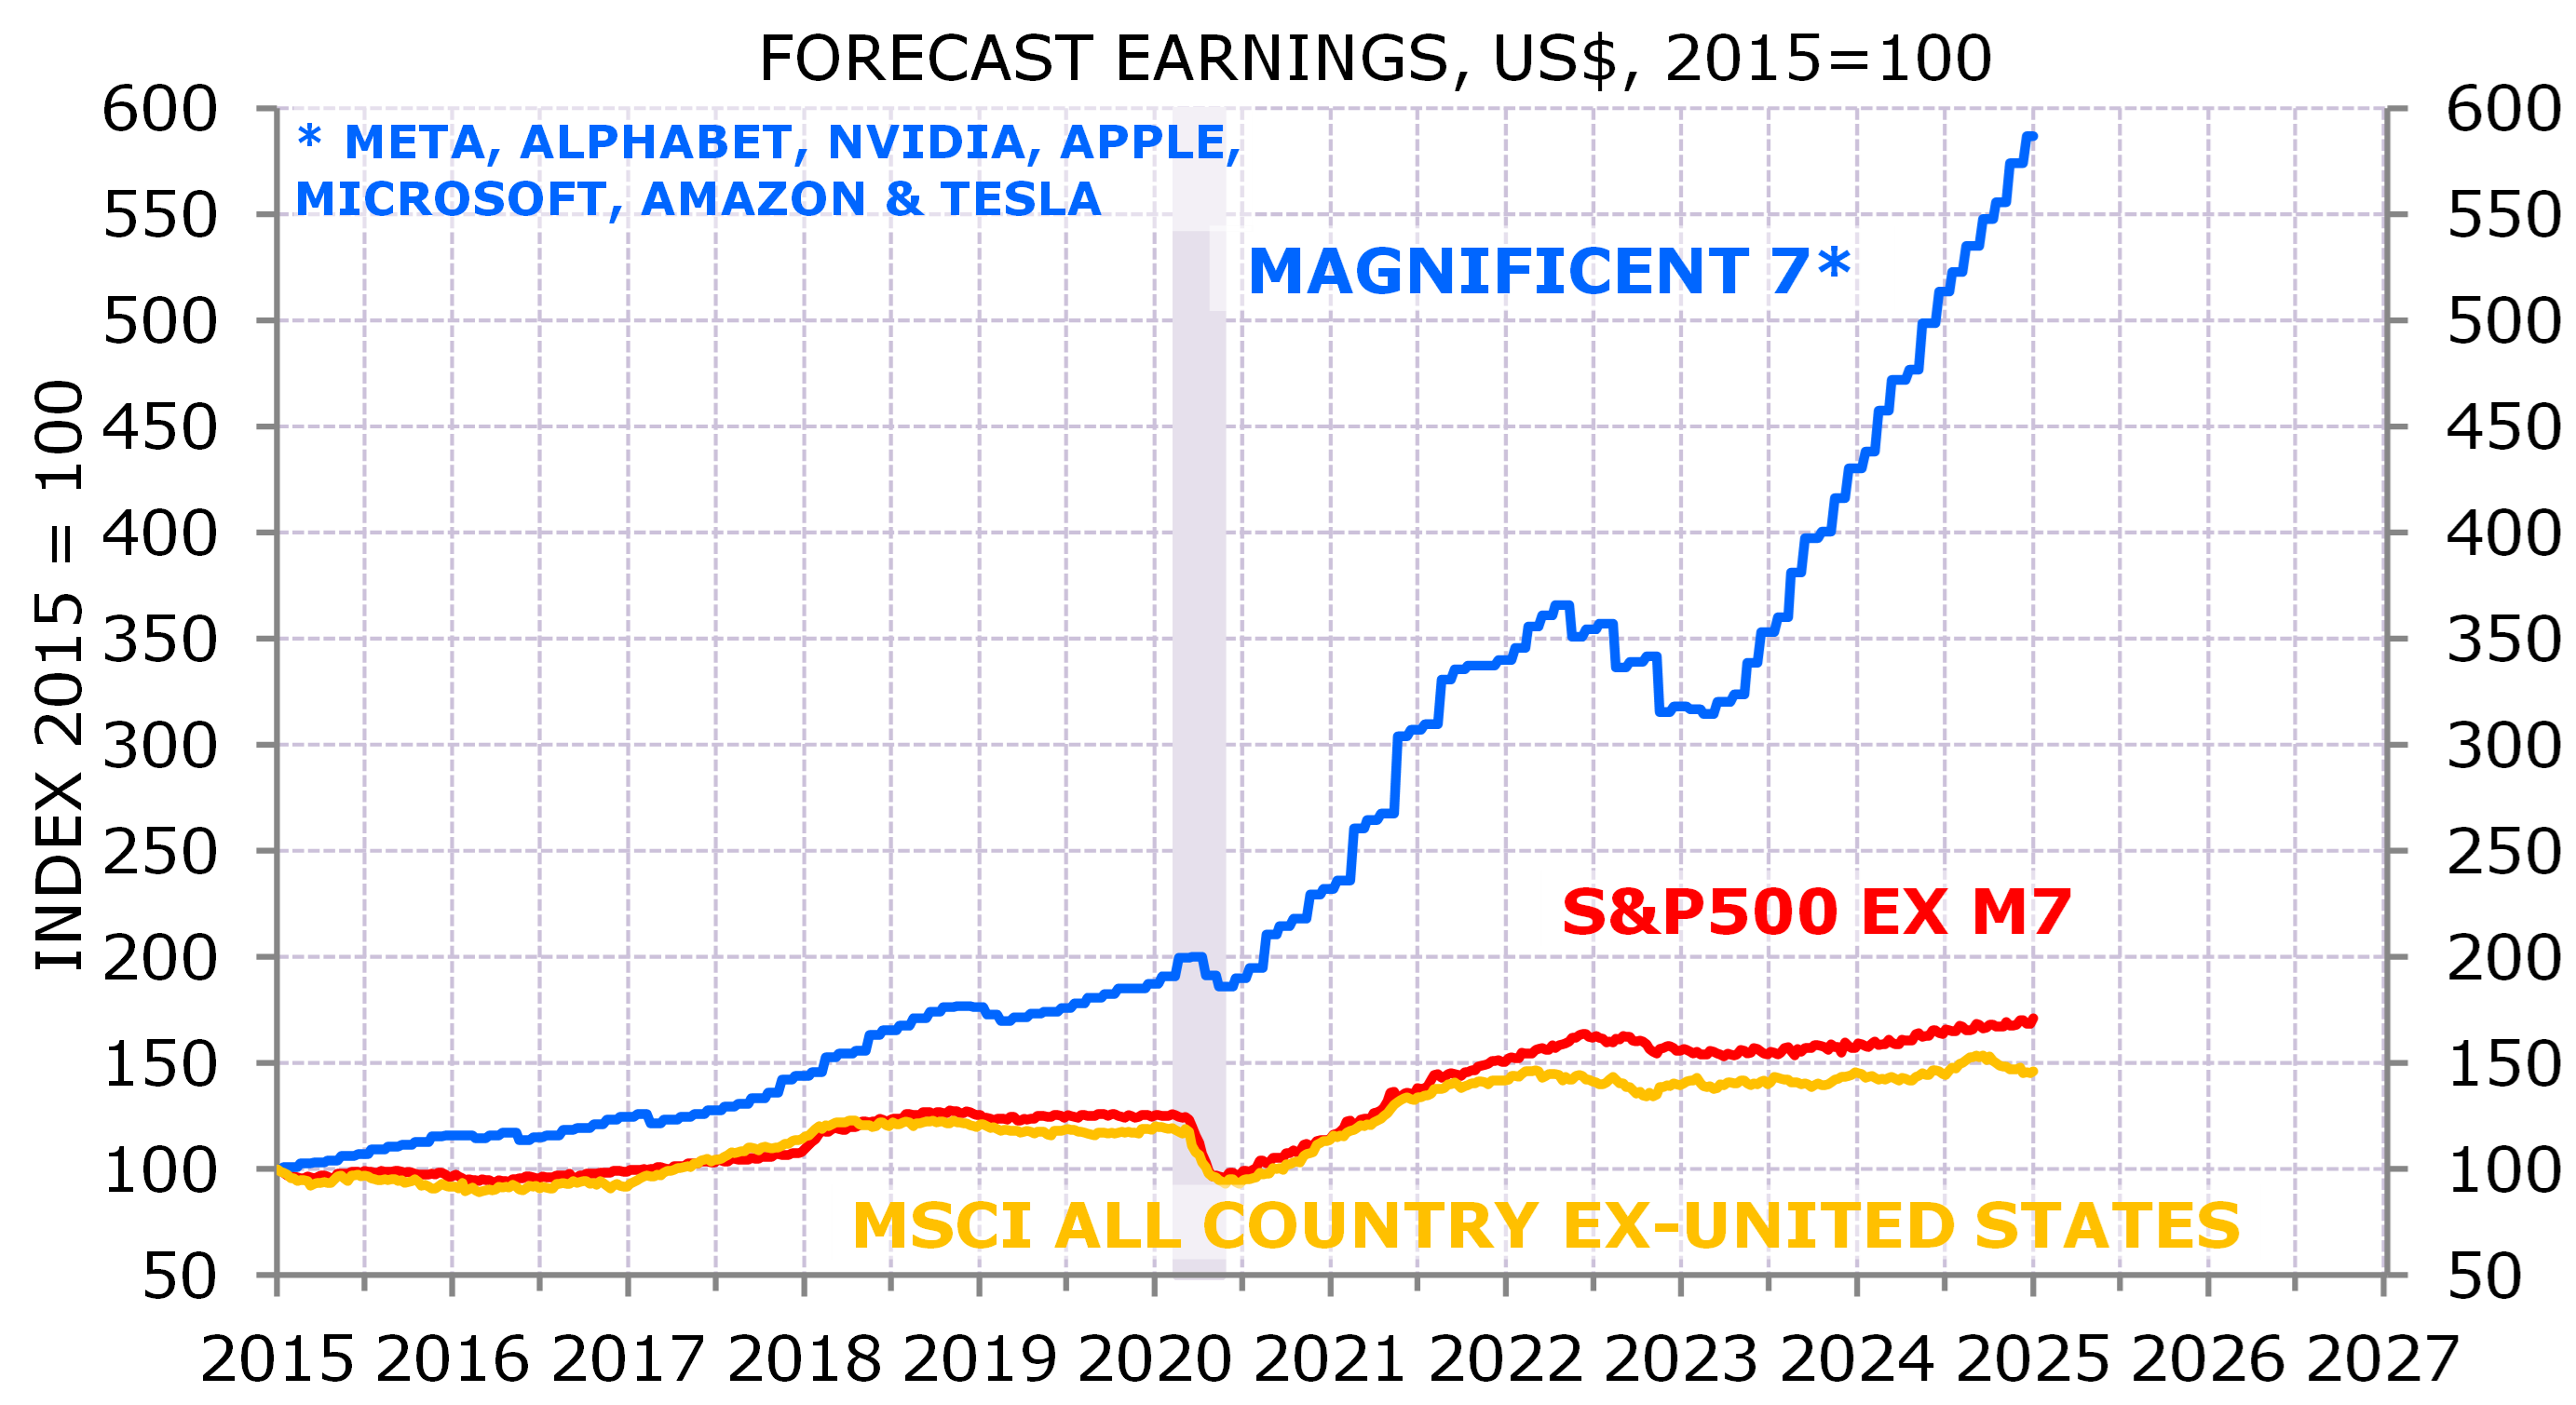
US EPS has grown at an above-average pace since the GFC: 4% real over the past decade versus a long run average of 1.75%. Most of that exceptional growth – and most of the recent US EPS out-performance versus other markets – is due to the Magnificent 7 (Exhibit 7). I don’t analyse single names, so I don’t have a strong view on how long the Magnificent 7 can maintain EPS growth at recent rates. At some stage the law of large numbers will have to kick in. But several clients have commented that 2025 will be the ‘show me the money’ year where investors will want companies to show the payoff for the massive investment in artificial intelligence. If the returns aren’t there, valuations could fall.

Exhibit 7: Mag 7 explains most of US EPS exceptionalism
Source: Bloomberg, IBES/DataStream, MSCI, NBER; Minack Advisors

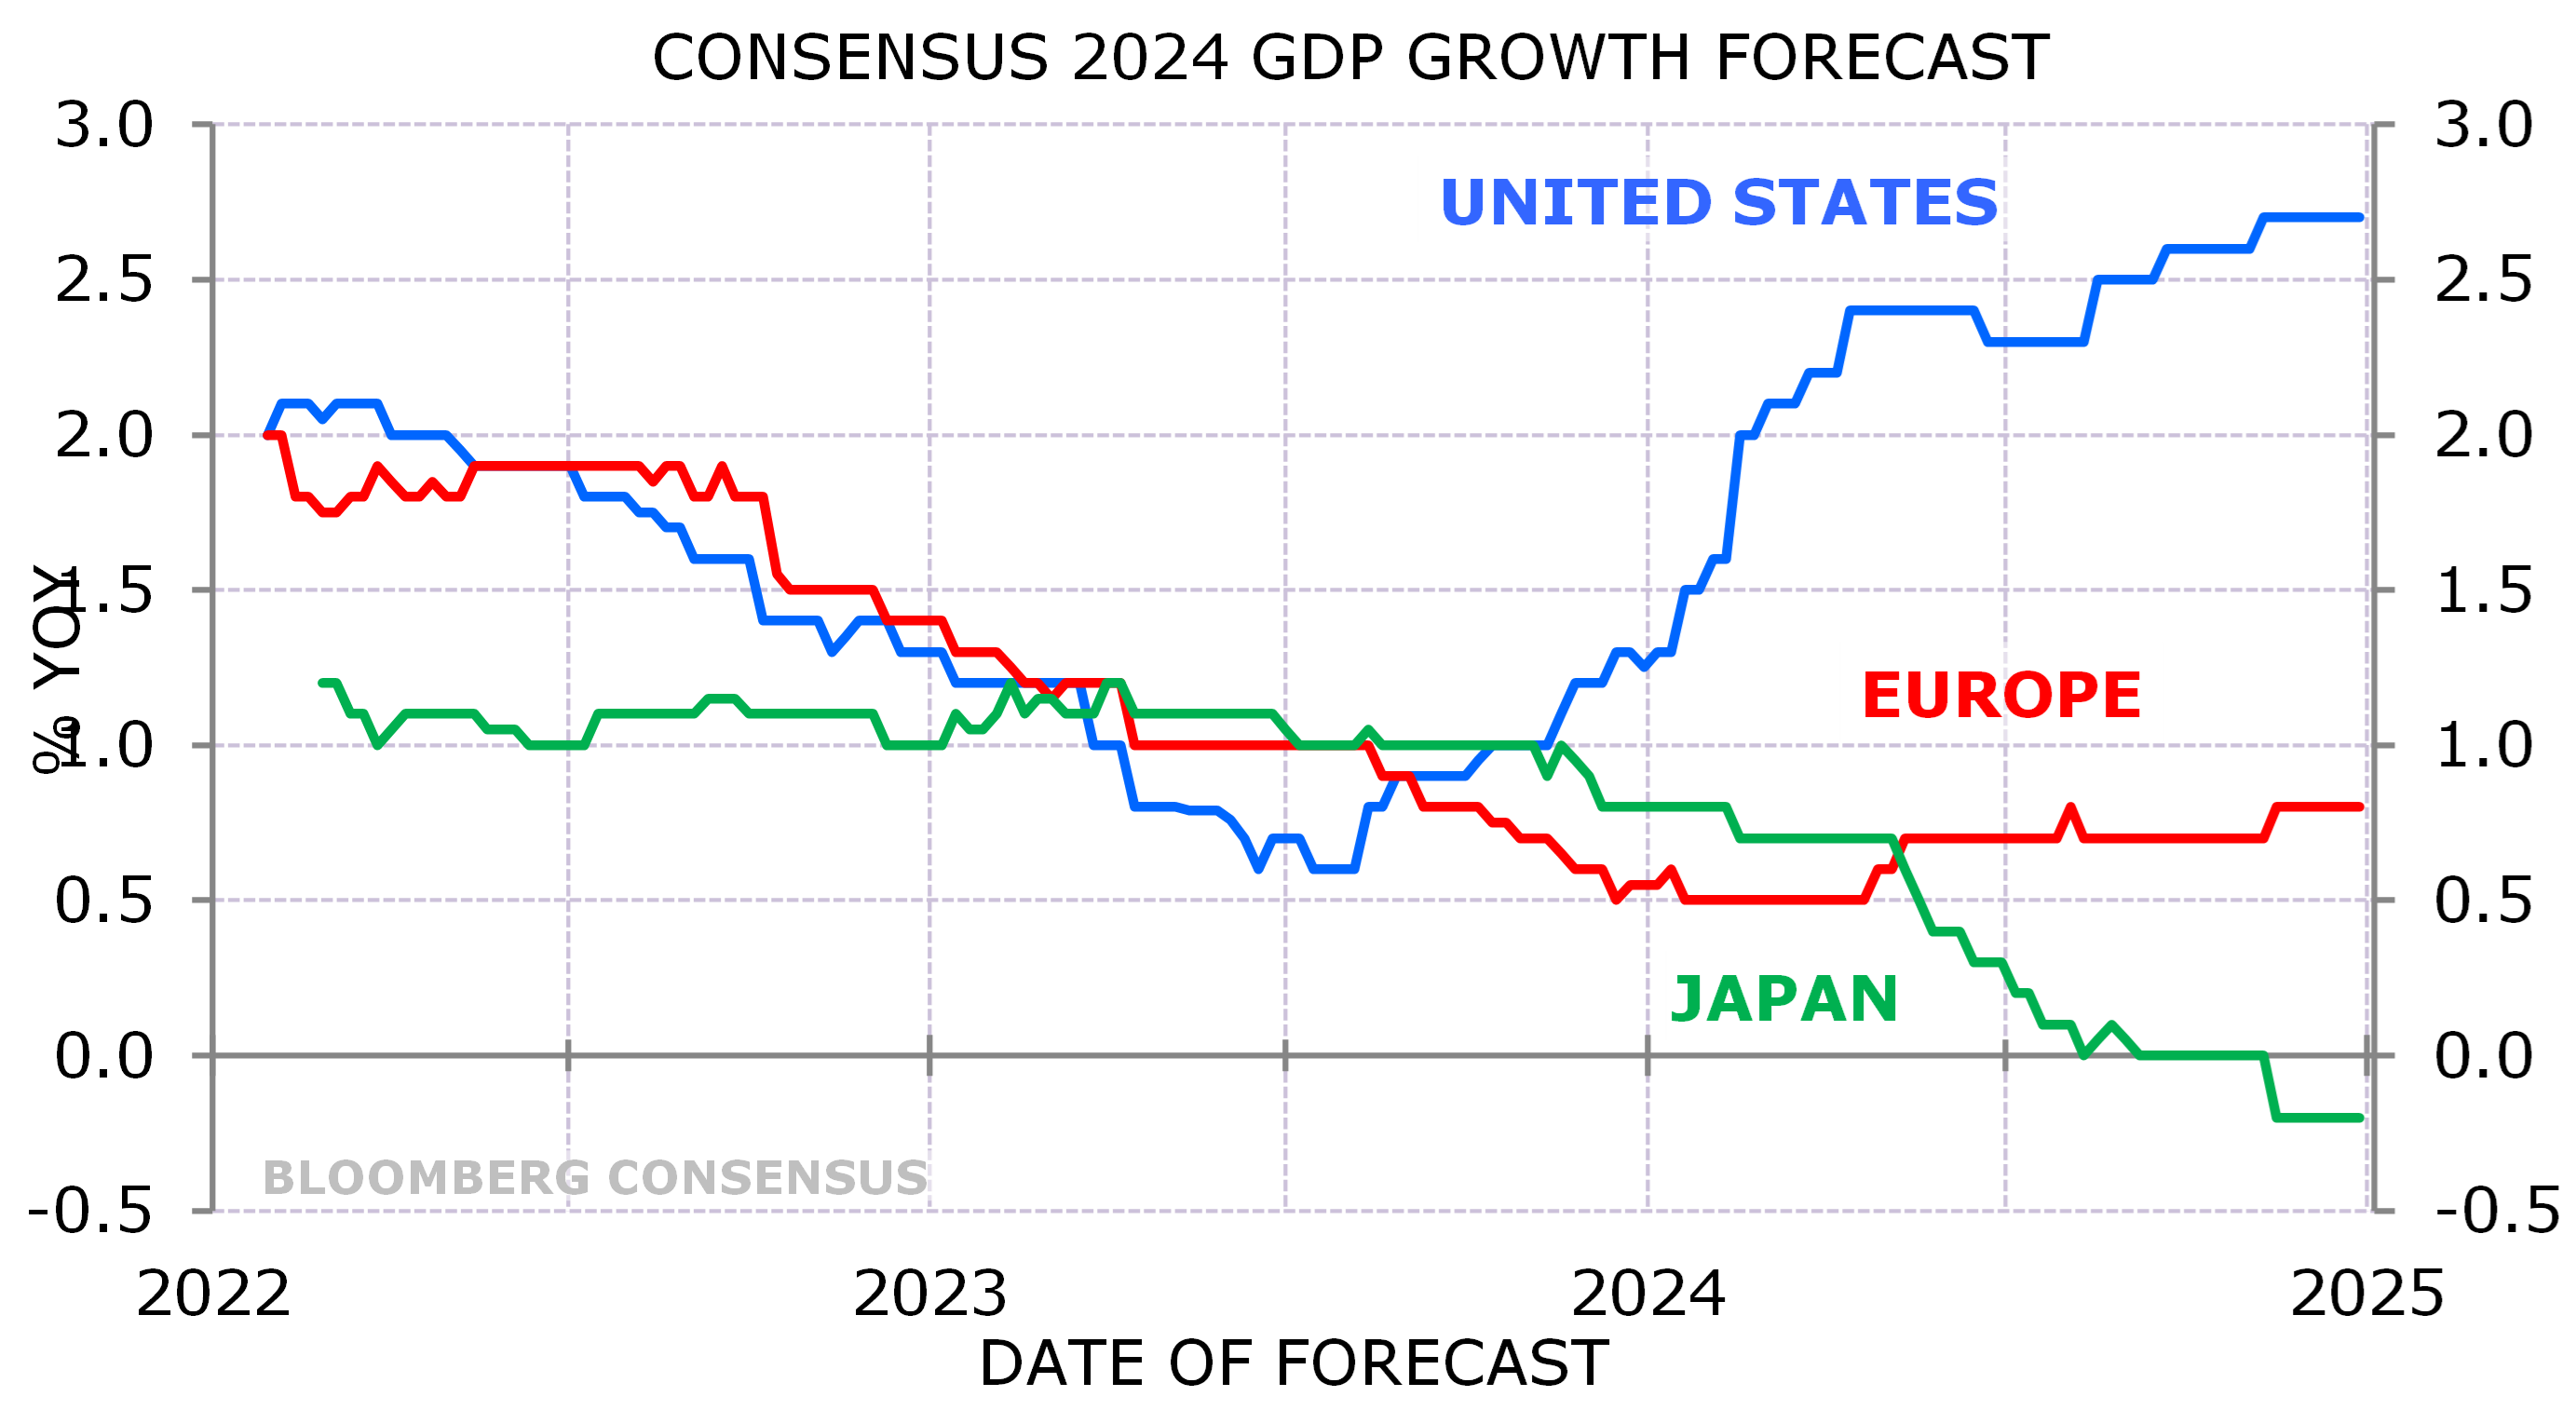
Much of the recent EPS out-performance of the S&P493 versus the rest of the world has been driven by diverging macro growth rates (Exhibit 8). However, I expect the growth gap between the US and the rest of the world to narrow in 2025.

Exhibit 8: This was not the year for RoW recovery
Source: Bloomberg, NBER; Minack Advisors

Mr Trump’s election has turbocharged US outperformance. While there may be a few sectors that benefit from specific policies, it’s not clear to me that Trump locks in sustained US equity outperformance. The cycle gap between the US and non-US markets should narrow next year. The prospect of higher long-end yields is a greater threat to the expensive US market. Mag 7 performance will be tested if AI underwhelms. And everyone is so bullish the US, who’s not already in?


Gerard Minack founded Minack Advisors in 2013 and has a wealth of experience as a macro strategist.

This article contains material based upon publicly available information, obtained from sources considered reliable, and is not soliciting any action based upon it. Opinions expressed are current as of the date of publication. All forecasts and statements about the future, even if presented as fact, should be treated as judgments, and neither Minack Advisors Pty Ltd nor its partners can be held responsible for any failure of those judgments to prove accurate. Minack Advisors Pty Ltd is regulated by ASIC, authorised representative number 443937.


  •   15 January 2025
  • 1
  •      
  •   

RELATED ARTICLES

Are the good times about to end?

UniSuper’s boss flags a potential correction ahead

2025: Another bullish year ahead for equities?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.