Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 257

The outlook for Australian banks

A good way to judge how companies are performing in Australia is to compare stockbroker price targets before and after the release of financial results. It's a straightforward measure and cuts out noise about one-offs and taxes, currency fluctuations, management ability and strategy execution.

Notable movements in share price targets

After cloud accountancy software provider Xero released its FY18 financial report in May 2018, price targets went up. When property listings platform REA Group provided an update on the March 2018 quarter, price targets went up. The same happened for News Corp, though that was largely REA-inspired. After Macquarie Group released their financial report last month, price targets jumped.

And the banks? Every one has recently seen price targets decline on the back of financial results, or, in the case of CBA, a quarterly trading update. Most commentators point at ‘cheap’ valuations for the banks (except Bendigo and Adelaide) given most are trading below consensus (and declining) price targets.

Banks are finding it difficult to participate in the broad-based market recovery, regardless of all the value calls, the fact that cheap-looking laggards have been regaining investor interest, and despite most banks paying above-market half-yearly dividends.

The IBISWorld view on banks

Clearly, something else is going on and it's not just about ongoing despicable embarrassments at the Royal Commission. Sector analysts at IBISWorld are widely known for their specialised sector research reports such as on retail spending and new trends in consumer electronics. They have weighed in on what lies ahead for the sector once thought of as the closest thing to ‘indestructible’ by Australian investors (but no longer).

On their assessment, Australian banks will be hamstrung with higher capital requirements, tighter regulation, and higher costs as a result of the public outrage over their misconduct in years past, and the regulatory and political scrutiny that follows as a result. While IBISWorld suggests higher costs will be partially passed on to clients, the analysts now forecast declining revenues for the next five years.

Another consequence of the Royal Commission should be tightened standards for lending to investors, consumers, and businesses, suggest the analysts. While this opens up a drive for increased market share by smaller competitors, including non-bank lenders, this will also have consequences for credit growth in general, which closely intertwines with economic momentum and house prices in Australia.

The UBS analysis of the sector

UBS's negative view on banks has consequences for the broader domestic economy with the house view fearful that tighter credit is likely to lead to weaker house prices. There will be a flow-on impact on household sentiment through a fading of the so-called wealth effect that stems from positive momentum for property prices.

No surprise then, that UBS thinks GDP growth forecasts by economists elsewhere are likely to prove too optimistic, including the 3% forecast maintained by the RBA for 2018. UBS suggests 2.75% is more likely, and this will keep interest rates on hold until the second half of 2019.

In a separate analysis, UBS economists suggest that tighter public scrutiny in Australia has the potential to spread to New Zealand. This could translate into yet more pressure for Australian banks who also dominate across the Tasman.

While further tightening of credit in New Zealand would add more downside risks for house prices and consumer spending there, and potential for bad debts to rise, an equally-intriguing observation can be made from the graph below, taken from that same UBS report on Australian banks in New Zealand.
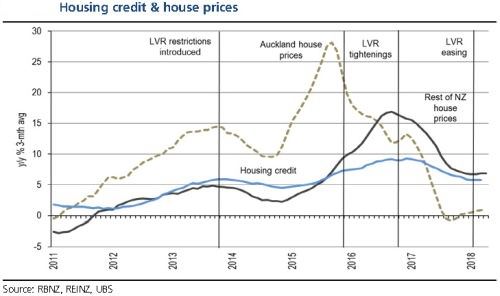
The graph shows the tightening by banks had an almost immediate impact on house prices where there was elevated momentum (Auckland), and that a softening in lending standards once house prices were falling takes a lot longer to then stabilise the market.

The JP Morgan perspective on banks

JP Morgan recently wrote that Australian banks had let their standards slip, as was also revealed at the Royal Commission. APRA had already instructed banks to set limits on new loans in high debt- and high loans-to-income categories, in industry parlance known as DTI and LTI loans. With aggregate household debt in Australia rising to 189% of disposable income, JP Morgan believes that banks are being forced into more conservative lending practices.

A big chunk of the positive momentum in house prices in recent years stemmed from investor-borrowers, and there appears to be a direct link to higher LTI loans with both sellers and buyers in this particular bracket enjoying high LTI mortgages.

JP Morgan is predicting credit growth slowing from 6% annualised to 4% over three years. This seems like a gradual, relatively small contraction, but the impact could be significant. Consider the following maths: High LTI loans represent around 10% of total volume in new loans, but because of their above-average size, JP Morgan believes these loans represent maybe 31% of all new lending in dollar terms. JP Morgan is not predicting a crash in house prices in Australia, but a noticeable slowdown in overall activity, which translates into lesser demand for credit. A crash requires forced sellers.

Related effects of a credit slowdown

The outlook for banks has not looked as clouded since the global financial system froze in 2008, and this is understandably turning the sector into one of the major laggards in the local share market. Investors holding shares in discretionary retailers should also better prepare for tougher times ahead. This is a slow going, long drawn out process and with little in the way of a sizeable increase in average wages, I'd be inclined to think the overall landscape for consumer spending will remain subdued for a lot longer than the optimists expect.


Rudi Filapek-Vandyck is an Editor at FNArena. FNArena’s service can be trialled for two weeks at www.fnarena.com. This article has been prepared for educational purposes and is not meant to be a substitute for tailored financial advice.


  •   6 June 2018
  • 2
  •      
  •   
2 Comments
Fundie
June 07, 2018

We should recognise that fully-franked dividends cover a decent fall in share price from these levels. By my calcuations, F/F dividends are ANZ 8.6%, BOQ 11.9%, CBA 8.9%, NAB 10.7%, WBC 9.8%.

Marvin Cathey
June 07, 2018

Mmmm... Not a terribly helpful analysis. Why doesn't he use his own words and say "Sell the banks get out now at any price."
Bank share prices have fallen substantially. Bank profit growth will be constrained for a period of time but online technology uptake, reduced staff numbers, reduced physical bricks and mortar branches will be an offset.
Safe reliable banks are a necessary central core to facility commerce. If banks are not sufficiently profitable they will go broke.
Following this to its logical conclusion could mean we don't have independent banks in the future but a single direct government owned and run "bank" controlling commerce. A quasi government department. Why not combine it with the ATO. And we all know what dealing with a government department is like. Ask the minister for Centrelink. "It takes 57 minutes before the phone is answered at Centrelink presently (THAT'S ON THE RARE OCCASIONS YOU CAN GET A PHONE LINE TO RING). The minister seems to think that was a good result as last year the wait was over an hour!!!
Some would argue that post Royal Commissions our banks could be so bound up with red tape that they become virtual government departments anyway.
So don't bash the bank to hard as we may end up with something far worse than we have now.


Leave a Comment:

RELATED ARTICLES

3 key risks: banks are too big to behave badly

The sorry tale of our big banks

The forgotten asset class set to outperform in 2022

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.