Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 454

The forgotten asset class set to outperform in 2022

Against a backdrop of economic and geopolitical uncertainty, rising inflation and expectations of a rate hike, Australian investors are searching for investments that can benefit from these evolving market conditions.

With credit spreads at attractive levels, now might be the opportune time to have exposure to hybrids and credit. With minimal returns on cash continuing to underpin strong demand for hybrid securities, we anticipate demand for yield to remain robust throughout 2022, resulting in strong returns over the year for this asset class.

The upside of rising interest rates

Rising inflation, above average GDP growth and the unwinding of quantitative easing (QE) in 2022 has seen financial markets reprice interest rate expectations.

The rising rate environment will push the outright return on hybrid securities higher, without having a material impact on spreads given the strong economic backdrop. Given most hybrids are floating rate, investors will benefit via higher income from these rising short-term rates.

Strong balance sheets you can bank on

Australian banks are the largest issuers of hybrids domestically and their balance sheets are in fantastic shape, with capital ratios at historical high levels. COVID-19 provided Australian banks with access to cheap funding via the Term Funding Facility (TFF), which provided them with a degree of funding certainty and lower funding costs.

Following the withdrawal of the TFF in 2021, new bank issuance is coming to market at attractive credit margins, providing the ideal environment for active credit managers to identify the most positive risk adjusted opportunities.

For instance, bank senior credit margins are significantly off their TFF lows, which is leading to an attractive re-pricing across all bank capital issuance (refer to Chart 1). Overvalued growth sectors are likely to lead an equity market sell off similar to 2000 – 02, but are unlikely to impact credit market returns.

Chart 1: Bank senior credit margins – Well-Off Their TFF 2021 lows
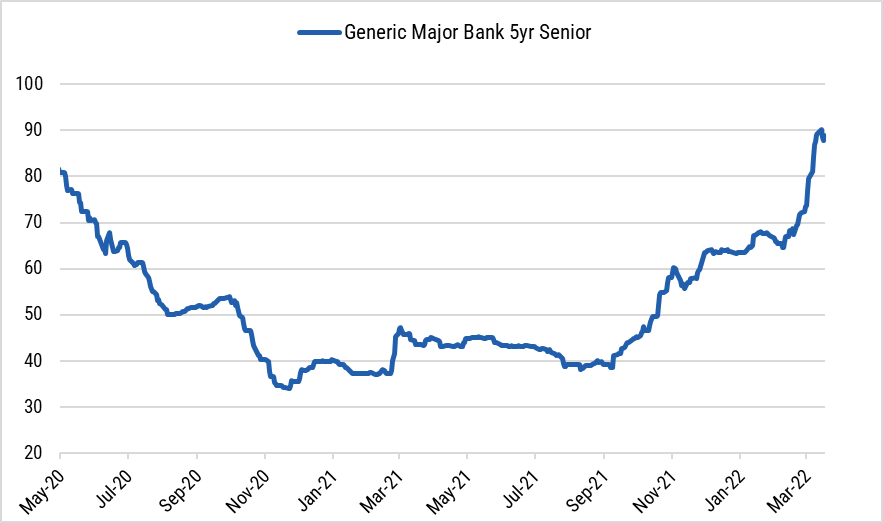
Source: YCM/NAB/BBG –March 18, 2022

Fully protected from higher interest rates with high carry protecting returns

The higher the carry (running yield of an investment), the greater the protection it offers investors from adverse movements in credit margins. The carry for the Yarra Enhanced Income Fund (“EIF”) is currently sitting at ~3.0% above cash.

Based on an average portfolio maturity of ~3 years, we’d need to see an extreme 1.0% move wider in credit margins to wipe-out the carry. However, given the robust economic backdrop in 2022, we expect credit margins to remain relatively stable throughout, adding to floating rate credit’s income generating credentials.

This benign outlook is in contrast to the capital losses currently being observed in traditional fixed income due to the reset in interest rates and real yields. Usually, a rise in real yields will impact the value of everything long interest rate duration, from traditional fixed income to most equities. That’s not the case with floating rate credit, since its short duration offers protection to portfolio valuations from rising interest rates. This is observable in EIF’s outperformance compared to traditional fixed income (Bloomberg Composite Index) since February 2020 (see Chart 2).

Chart 2: Floating rate credit with carry continues to outperform fixed rate with little carry
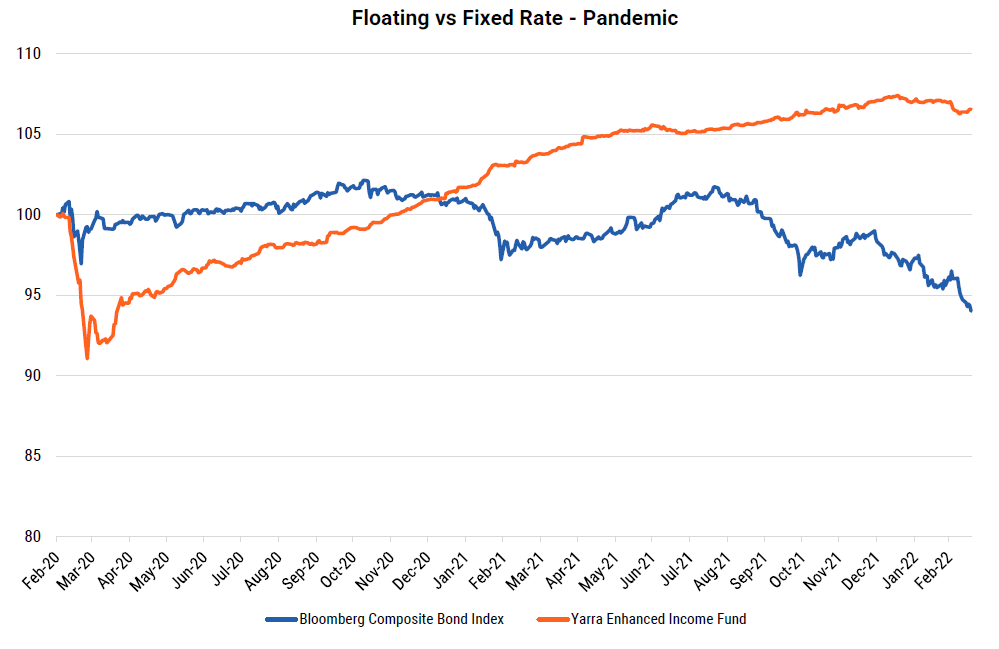
Source: Yarra Capital Management, Bloomberg. As of March 18, 2022

Making the grade

In a world that seems to be getting riskier by the minute, investment grade hybrids look to be a safe haven for investors. Here’s why:

  • Investment grade hybrids appear to be fairly priced in an environment appearing increasingly more expensive, especially if real yields rise or normalise in a post QE world.
  • Investment grade issuers remain well capitalised, making them more likely to be able to service their interest payments and repay debt.
  • Most Australian investment grade hybrids are floating rate securities, which tend to pay higher yields if prevailing rates go up because they are based on a variable interest rate, rather than fixed. Not only does this mean more income when rates rise, but there is also no loss of capital.


Roy Keenan is Co-Head of Australian Fixed Income at Yarra Capital Management.


  •   13 April 2022
  • 6
  •      
  •   
6 Comments
CC
April 13, 2022

Floating rate securities are definitely the way to go in the fixed income part of one's portfolio

William Allan Cross
April 17, 2022

Funny how the minute that hybrids start looking attractive the big end of town influences the regulator to make purchasing new issues almost impossible for the little end of town.

David paine
April 20, 2022

As a part of the "little end of town" I have been totally miffed over the last couple of years with the examples where we have been attacked. This change from late 2021 you mention for hybrid issues is appalling for us.

Alexander Smith
April 21, 2022

It would be interesting to learn of ASIC's reasoning (or lack thereof) in their decision to allow retail investors to pay through the nose for quality hybrids on the secondary market, but block the little guys from participating in new issuances of those same company hybrids without the brokerage charges and price increases for good quality securities.

Michael O'Rourke
April 22, 2022

It is fairly clear that ASIC is more focused on the uninformed consumer rather than the average retail investor, of whom they have very little knowledge. (ATO deals with SMSF's, and ASIC most likely doesn't understand how SMSF's work, as so many public "servants" access the very generous commonwealth super scheme).
The punitive approach adopted by ASIC in recent years to ensure compliance initially "glued up" establishing simple accounts and increased costs with no real benefit to investors. What caused the change on hybrids? What was the rationale? Are they worried there is a risk of systemic failure of our banking system? Surely Austrac know bank hybrids can be purchased on the ASX. Will the next step be that you have to be classified as wholesale to purchase shares which entail even more risk than hybrids?
Another commonwealth entity which seems to lack competence is Austrac. Why isn't their performance being questioned? Wasn't it "common knowledge" that high rollers in casinos might be an issue. Now years afterwards they are enquiring. The bottom line is that Austrac has not developed the fundamental tracking tools themselves but expect others should and happily impose costs on the wide range of investors for no real benefit. Crime is a problem but surely in these days of big data Austrac could do better and be held responsible.

Alan B
May 02, 2022

Domestic and overseas shares and ETFs that focus on fixed rate securities are all falling in price, some by >20% since 2021, meaning capital loss. Hybrids and floating note bonds are all priced up above their issue price meaning the yield is low. I'm attracted to floating notes, just not seeing value opportunities.


Leave a Comment:

RELATED ARTICLES

The case for staying the course in credit

The naysayers may be wrong again on the Big Four banks

Why bank hybrids are being priced at a premium

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.