Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 349

Shaken by stock market carnage? Forget everything

All I am reading and hearing all around is this. Volatility is your friend. Stick to the long term. Don’t touch your portfolio. Keep some cash. Invest that in a staggered manner. Recheck your asset allocation. Shuffle your stock portfolio. Don’t borrow to invest. Don’t speculate. Quickly search for new stock ideas. Stop watching news.

Well, let’s cut it all.

The markets are sneezing bad, and your portfolio may be in a sea of red on account of the big recent declines.
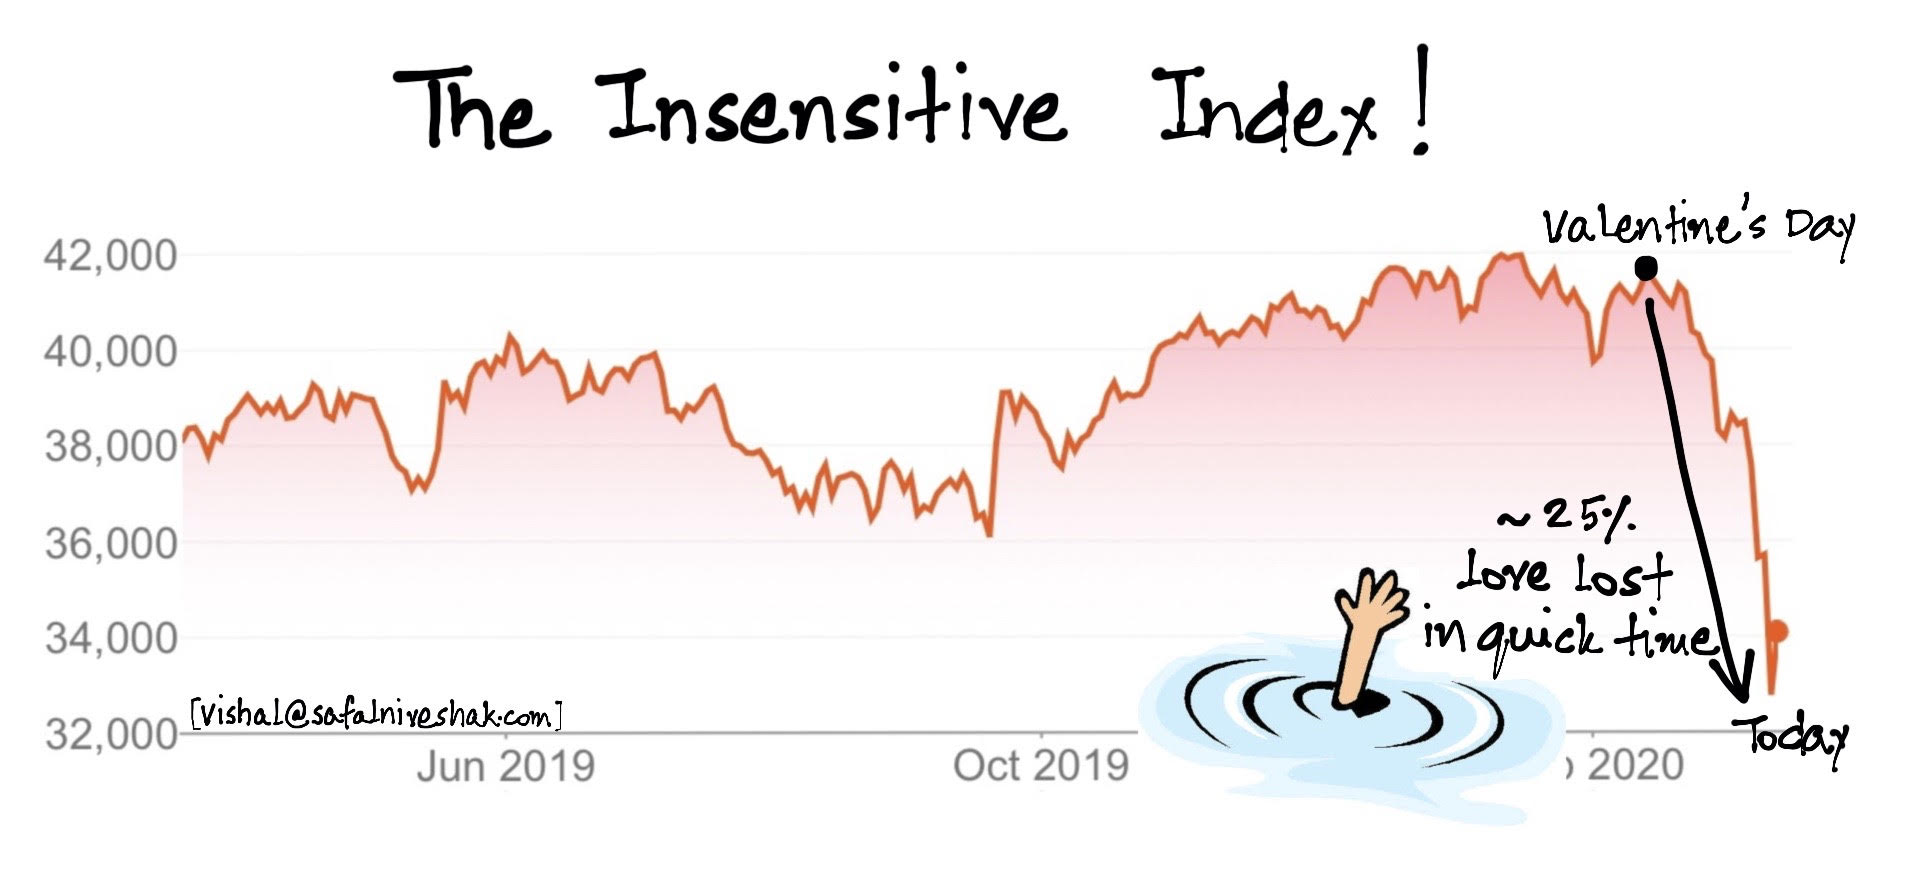
Amidst this, what can you do?

Rue your losses and hold on to them? Sell your winners so that you don’t lose your paper profits? Become greedy because others are fearful? Become fearful because others are fearful? By the way, who are these others anyways?

Things look so confusing out there. And so are all kinds of advice that is floating in the news and social media. Everyone is out there to remind you of how dumb you have been and how smart they are. Stop there!

Here’s something simpler, very soothing to the soul, and very effective too, that I advise you to do now. This is the exact same advice I’ve given to myself, so we are in the same boat.

So, what’s my advice?

Let bygones be bygones. Forget everything. Start afresh.

Nobody has any clue what is going to happen, short term or long term. After the dust (sorry, virus) settles, people who will get it right will simply be the ones whom luck chose to side with. They may appear on television and remind you how their prediction went right, without revealing which one, and how their skill shone through the crisis. But, believe me, those would just be the lucky ones.

Even you don’t have any clue of where all this is heading. All you can see now and act upon now is what has happened in the recent past and how you have done through it all. Your brain, like mine, is poisoned by a heady cocktail of anchoring bias, endowment bias, availability, hindsight bias, social proof, sunk cost, confirmation bias, loss aversion, etc.

How do you maintain sanity with such poison running through your mind?

Simple. Forget everything. Start afresh. But how do you go about it? Where do you start? What do you forget?

Here’s what to do.

Take a print of your current portfolio but just the names of stocks you own. Exclude your buy price and the current stock price. This is so that you forget at what price you bought a stock and whether that is up or down from that level till today.

This is another reminder that your cost price must not matter when you are deciding what to do with your stocks today. What matters is where the stock is today, and where the business and its intrinsic value may be 10 years down the line.

Anyways, coming back to your portfolio, take a re-look at your thesis on each stock, one by one, and objectively.

Ask this question for each stock you own: “If I did not own this stock already, and of what I know now about this business, management quality, competitive advantage, staying power, long term growth, and current valuation, would I buy it for the first time today?"

If the answer is yes, keep the stock. Period.

If the answer is no, sell the stock. Period.

Then run this question on other stocks in your watchlist, this time forgetting from where those stocks have fallen or risen from.

Ask this question for these new stocks – “Of what I know now about this business, management quality, competitive advantage, staying power, long term growth, and current valuation, would I buy this new stock for the first time today?

If the answer is yes, buy the stock. Period.

If the answer is no, skip the stock. Period.

Most biases that wreak havoc on our minds as investors are creation of what stock prices have done in recent times and whether we have earned or lost money on them or have seen others earning or losing money on them.

Performance of underlying businesses – good or bad – don’t cause us much trouble as their stock prices do.

So, if you wish to really clear your mind and get into a position of some sanity as things fall apart around you, the most potent tool in your arsenal is the idea of forgetting, better ignoring, what stock prices – of your portfolio companies and those in your watchlist – have done since the time you own them and especially in recent times.

Plus, don’t listen to anyone who would remind you how smart they are and how dumb you have been. Forget them too.

Just forget everything, also forgive yourself for any past mistakes, and start afresh.


Vishal Khandelwal is a writer, educator, investor, and Founder of SafalNiveshak.com. This article is for general information only and does not take into account any person’s individual financial situation.


  •   18 March 2020
  • 4
  •      
  •   

RELATED ARTICLES

Should investors brace for uncomfortably high inflation?

Why we’re not buying the market yet

What should you do next?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.