Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 229

Stock market winners 10 years on

It has been 10 years since the end of the 2003-2007 global China/credit boom, and it is time to check in on how stock markets have fared since then. The left chart ranks countries by their broad share price index growth over the past decade. Only 36 of the 62 main stock markets are ahead of their pre-GFC highs. The right chart shows average economic growth rates per country over the same period, in the same country order as the market performance, to demonstrate if economic growth relates to share price growth.
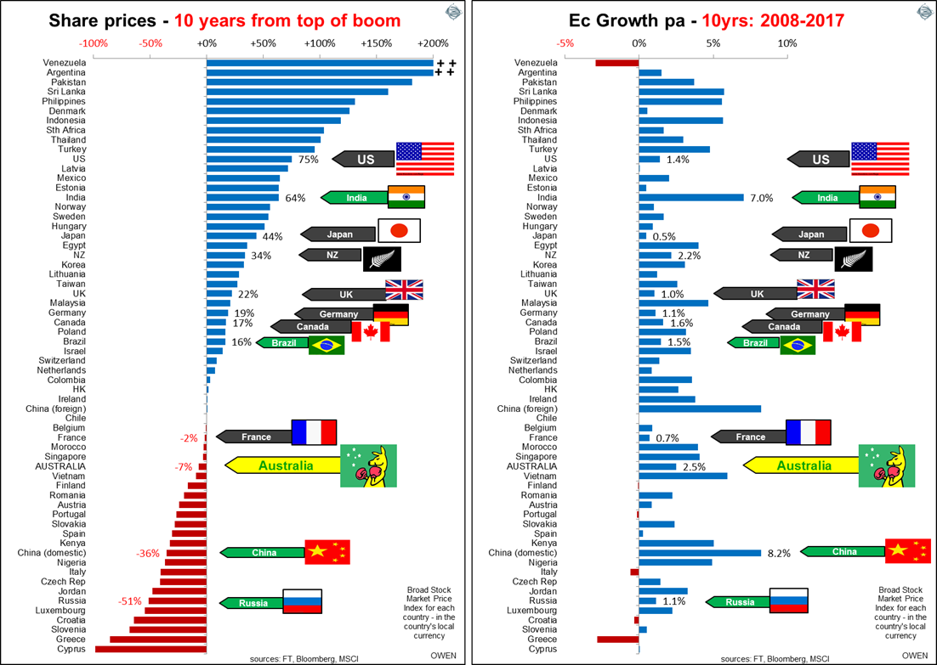
Among the ‘developed’ markets, Denmark won the gold medal in January 2013 for being the first stock market to surpass its pre-GFC peak, and it is now 126% ahead (i.e. more than double its pre-GFC peak). The silver medal went to the US in March 2013 and bronze went to the UK in May 2013. [See previous articles, Stock market Olympics, and the winners are and Australia can learn from gold medal winner, Denmark].

As usual there has been no statistical relationship between economic growth and share prices when measured across countries. Australia has been the so-called ‘miracle economy’ with the strongest long-term economic growth rate in the ‘developed’ world, and it did not even suffer an economic recession in the GFC, thanks to a deficit spending spree our grandchildren will be paying off. Yet the local stock market index (in price terms, not accumulation including dividends) is still behind its November 2007 high.

In contrast, the US, UK, Western Europe, Canada and even New Zealand suffered far lower economic growth rates in the GFC and over the past 10 years, but they have generated much stronger share prices than Australia. Denmark, the stand-out gold medallist stock market in the developed world, has had virtually no economic growth over the past 10 years. At the other end of the scale, China had the fastest economic growth rate over the past decade (and the largest aggregate growth in human history) but has had one of the worst stock markets.

Another common feature is that countries with the strongest stock markets often suffer political, economic or social turmoil and this was the case again - e.g. Argentina, Venezuela, Pakistan, Philippines, Turkey and Mexico.

There are many reasons for differences in share prices in different countries of course, but this quick snapshot is a useful reminder of the folly of focusing on economic growth as a pointer to share prices.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is general information that does not consider the circumstances of any individual.


  •   30 November 2017
  • 6
  •      
  •   
6 Comments
Mark Higgins
November 30, 2017

Think you need to factor in our high dividends - eg the all odds Accumulation Index - then we are ahead.

ashley
November 30, 2017

hi mark

Adding dividends (and even adding franking credits) doesn't get the ASX anywhere near the leaders. ASX total returns including divs only gets us +37% ahead of its 2007 high.
And adding franking credits as well only gets it to +62% above the 2007 high. That is still below the S&P500 PRICE index which is +66% ahead (before dividends), and it is still some 40% below the S&P500 total return index including US dividends.
(and Aust is also still behind other major markets like Japan, UK, Germany and even NZ on a total return basis)

cheers
ashley

Chris Jankowski
November 30, 2017

It looks to me that the results reported for the two top places - Venezuela and Argentina are completely bogus. Both of these countries had periods of uncontrolled and under reported high inflation. The simplistic comparison most likely ignores that.

By these standards the undisputed leader, had it been reported, would certainly be Zimbabwe.

ashley
November 30, 2017

hi Chris -
regarding inflation - i also measure each market after its domestic inflation.
In addition I also measure each in terms of AUD returns on both a hedged AUD basis and un-hedged AUD. So there are dozens of ways of measuring returns.
For the above story I used the domestic nominal returns in each country in the local currency of each country - in order to show what the stock market for each country did for local investors in that country - because most investors have a heavy 'home bias' and think primarily about their own market in their own currency when then think about shares.
So back to returns after inflation - Australia actually does considerably worse on real returns because our inflation rate is significantly higher than other developed world markets - eg Europe, US, UK and Japan.
Cheers
Ashley

Albert
January 28, 2018

True that GDP does not correlated with Stock returns. Markets rise and fall.

Some points to note :
1. Few of us would invest in countries like uninformed, poorly developed, small third world markets - so this is largely irrelevant in our investable universe.

2. We need to have a large investment in our locale of domicile to match risk and liability/needs. Yes, we can hedge currency but there is a cost to wear which comes off your long term return.

3. Given that we invest in largely open and efficient markets the long term returns will equalise i.e. investors will appropriately price high vs low growth stock markets resulting in rational returns for risk. Overseas have done well for now but this will change too.

Phil
January 28, 2018

Is 10 years really long enough for it to be statistically sound. The article uses the word statistical basis. It's one period and correlations can change depending on a number of other variables, not just GDP.


Leave a Comment:

RELATED ARTICLES

GFC and personal reflections, 10 years on

Podcast: What did you do during the GFC? Warning signs and lessons for investors

The ASX's 16-year drought: a rebuttal

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.