Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 88

Impact of QE on markets opposite of expected

October 2014 marks the end of the US Federal Reserve’s monetary policy it called ‘quantitative easing’ (QE) but the rest of us called plain old ‘money-printing’. The Fed’s aim was to create inflation by buying assets with newly printed money (instead of paying for them with cash raised by selling securities into the market) and crediting commercial banks’ reserve accounts in the hope that banks would increase lending to borrowers to invest and spend. A second aim was to depress the US dollar to help exporters (the theory being that money printing should devalue the currency because more paper money is chasing the same supply of assets).

There was much doom and gloom and even panic in the financial media about what QE might mean for markets. The resultant inflation or even hyper-inflation was supposed to be bad for share prices and bond prices, while the prices of inflation hedges like gold, oil and metals should soar. All this was supported by logic, theory, conventional ‘wisdom’ and the weight of opinion.

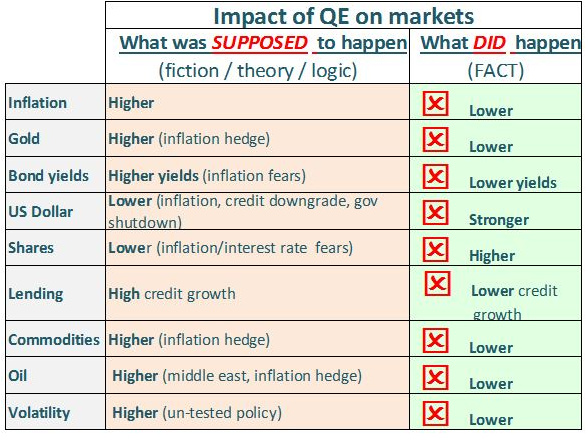
As it turns out, virtually all of the outcomes predicted by theory, logic and the shrill financial media were wrong. Driven by QE, markets did the opposite of what the conventional wisdom and weight of opinion expected. Prices of shares and bonds soared, the US dollar strengthened, and inflation and inflation hedges (gold, oil, metals) all fell.

The following diagram shows what was supposed to happen, and what did happen.
But US QE was not a failure. It prevented deflation in the US, which is far more debilitating than inflation. It also provided enough stimulus to bring US unemployment down from 10% to 6%. These benign outcomes inspired central banks in UK, Japan and now Europe to take similar action.

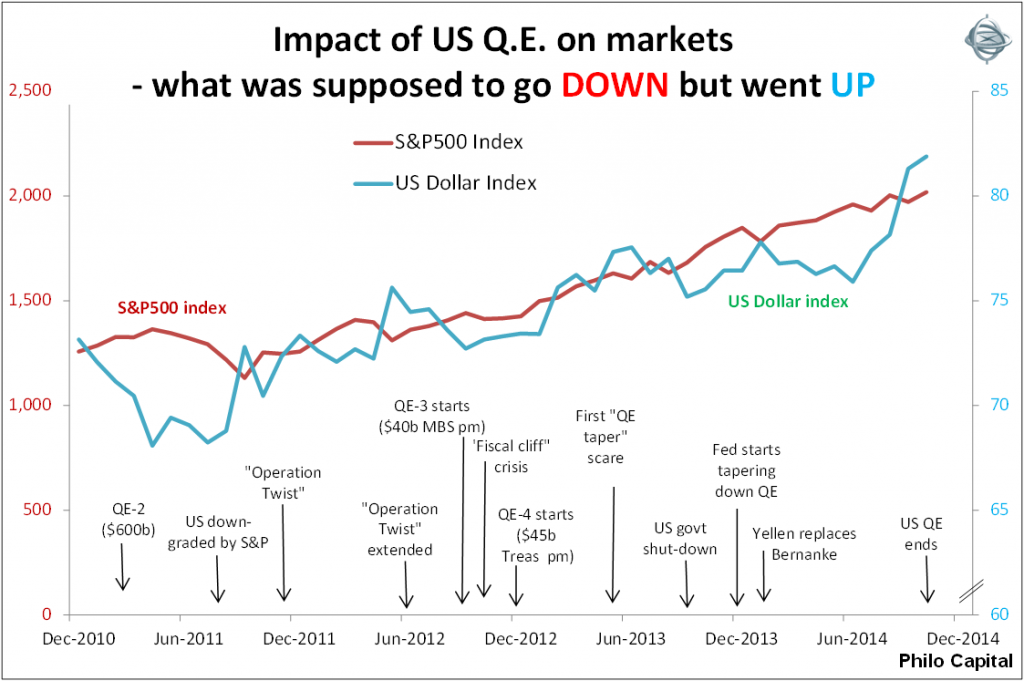
The following charts show the key events and impacts on markets. The first shows what was supposed to go down as a result of the massive central bank money-printing spree but went up instead.
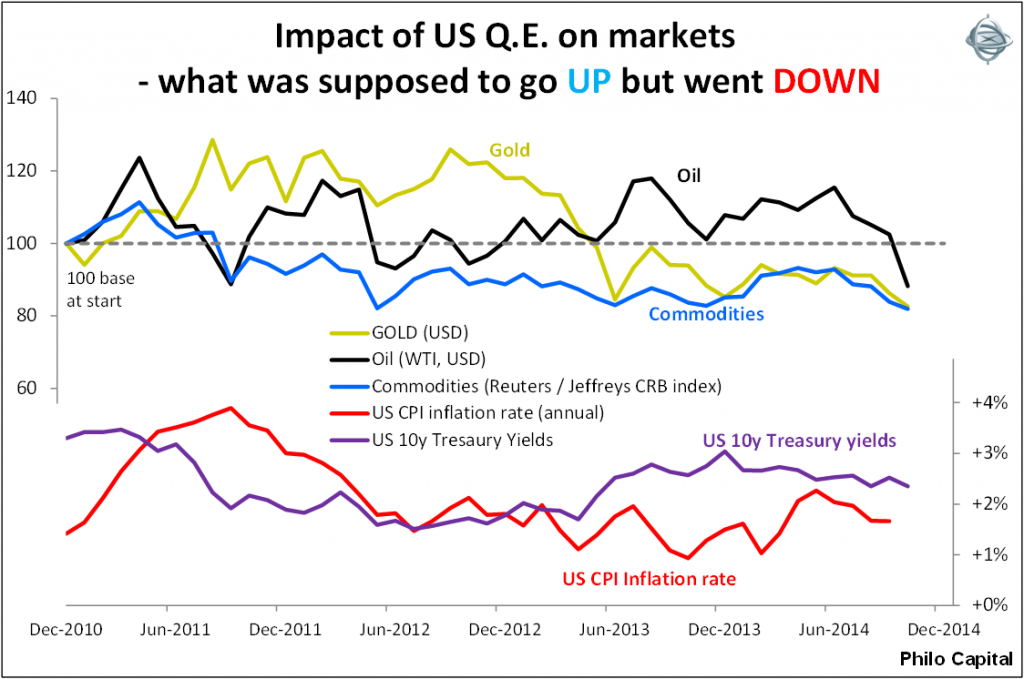
The second chart shows what was supposed to go up as a result of the money-printing but went down instead.
It has been a good reminder that markets do not work according to text-book theories, nor do they follow logic. In the real world markets are driven by humans who in turn are driven by raw emotions and often illogical knee-jerk reactions to events that they perceive to be relevant. Studying these dynamics is far more difficult, interesting and rewarding than studying theory!


Ashley Owen is Joint CEO of Philo Capital Advisers and a director and adviser to the Third Link Growth Fund. This article is for general educational purposes and is not personal financial advice.


  •   14 November 2014
  • 4
  •      
  •   
4 Comments
Kevin
November 14, 2014

Hi Ashley, I’m pleased you mentioned deflation, as you rightly point out, that was the key fear at the time. Whilst I’m certainly no expert, it seems to me if you view the results whilst looking through deflation glasses the results make more sense. US house prices had already deflated 30-50% depending on the state, so deflation was a real concern. In my view the QE money printing simply offset the deflationary pressures already in motion. This would explain why the popular financial media expectations did not eventuate (hyperinflation etc). As example, if bond yields are so low (due to Feds massive monthly purchases) there is almost no income derived then surely a logical expectation is investors will purchase income producing assets such as shares and the price for those shares will rise over time due demand. If the US economy was in a deflationary dive you would expect the US dollar to improve in value as it becomes worth more relative to other assets, especially given other countries were also actively depressing their currencies as well.

I’m not a fan of QE and as you say the jury is still out as to its longer term consequences, but I do think it worked as the Fed expected, it just wasn’t as the popular media expected.

ashley
November 15, 2014

Hi kevin
yes QE countered defaltionary forces. But falling house prices are not widely regarded as deflation , merely a correction from a bubble. Deflation forces came from huge excess capacity - human capacity (high unemployment), factory capacity, etc caused by the dramatic collapse in domestic and global demand.
But deflation was not a widely held fear. CPI inflation was running at 3% and 4%, the germans were running a scare campaign warning of 1923-style hyperinflation (they still are!), ATMs selling gold bars sprang up on the streets of Europe, and even the normally pro-inflation IMF advocated fiscal tightening.
The US also acted quickly to recapitalise banks but Europe is still in denial. Europe will be asleep for many years then it will just die of old age. The US has relatively good demographics (as has Australia) and this also helped in the recovery

Kevin
November 15, 2014

Yes I guess a US housing bubble collapse is a fair explanation and deflation by definition is prolonged negative CPI, but could you not also argue that the Feds QE pumped things up enough to counter what would otherwise have been prolonged negative CPI? I'd be interested in your view.

ashley
November 15, 2014

yes, deflation was the far more serious threat than inflation, although the inflation/gold bugs caught overwhelming bulk of public and media attention at the time. History will show that Bernanke was right and Greenspan wrong (although he was almost universally hailed as a god when he was in power).
Deflation should be a good thing - everybody likes paying lower prices! But if people expect lower prices next year they stop spending this year, and that stops production, investment and employment. It creates a negative spiral that requires a major shock (like an all-consuming war effort like WW2 followed by a baby boom and reconstruction boom) to break out of the spiral.
The other big difference between US and Europe is Europe's crippling extra layers of government and regulation, including and especially labour laws, welfare/pension entitlements and industry protection. It will take a lot more than money-printing by the ECB to get Europe out of its problems. So European QE (if it ever does occur it will be too late and too small) will be necessary but probably not sufficient to generate enough demand growth to restore full employment.
I don't make value judgements about whether policy actions like QE are good or bad, my main focus is on understanding impacts on investment markets and positioning portfolios to miminise losses and maximise gains.


Leave a Comment:

RELATED ARTICLES

Five reasons Australian rates unlikely to follow US

Clime time: Trump's US dollar assault is fuelling CBA's rise

Brace, brace, brace: The real issue behind the banking turmoil

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.