Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 405

It's not all about interest rates: give me a 1980s petshop galah!

The notion that the RBA ‘chooses to allow’ the ‘voluntary unemployment’ of several hundred thousand Australians is something that may come as a surprise to many. Yet that is precisely the charge levelled at the central bank in a tome from economist Ross Garnaut. He claims that such unemployment was a consequence of the RBA running monetary policy too tight after 2012.

Now Ross Garnaut is no slouch. He was a senior economic adviser to then PM Bob Hawke during the 1980s and has written extensively and thoughtfully on economic policy issues for decades.

However, the charge against the RBA is largely a specious one.

For one thing, the average monthly unemployment rate from February 1978 (when the current series was commenced) to the end of 2012 was 7.0%. From that point to the onset of the pandemic it was 5.6%.
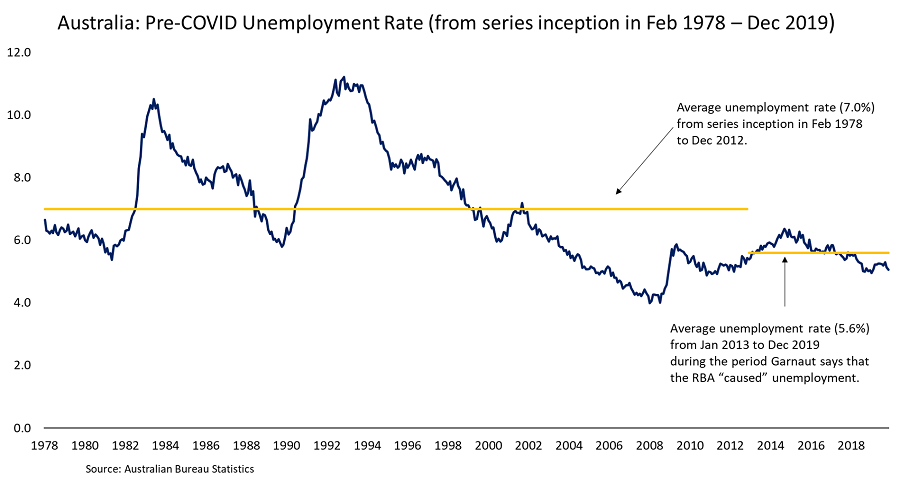
It might be interesting to find out who Garnaut puts in the frame for the even greater levels of ‘voluntary unemployment’ in the decades prior to 2012.

It's not only about monetary policy

Of course, hindsight is a wonderful thing, and the RBA may have run monetary policy a little too firmly after 2012. It is also probably true that the time has come to move on from inflation targeting as the overarching focus for monetary policy. Perhaps to one that explicitly embraces, among other things, an employment objective.

In the scheme of things, the RBA’s ‘culpability’ for unemployment levels is not deserved of the prominence that Garnaut and others give it. That prominence derives from an unbridled but misplaced faith in the efficacy of macro policy and a corresponding reluctance to consider structural measures that enhance the economy’s flexibility and adaptability.

The political wherewithal to consider such measures reached their apogee under the banner of ‘microeconomic reform’ during Paul Keating’s Treasurership.

By the late 1980s, as the then Treasurer put it, “every galah in the petshop was talking about microeconomic reform”. That agenda extended through the 1990s during his Prime Ministership and into the early stages of the Howard Government. (To be fair to Garnaut, he does canvass, albeit selectively, some measures of this nature.)

Where are the microeconomic reforms?

It was those type of microeconomic reforms, including measures to enhance labour market flexibility, that drove the ‘natural’ rate of unemployment lower, to the ‘4 point something’ now articulated by RBA Governor Lowe as a potential ‘natural’ rate, or perhaps even as low as the 3.5% Garnaut now posits.

But the current tacit refusal of both sides of politics not only to assign such ‘microeconomic reform’ measures to the ‘too hard’ basket, but in some cases reverse those reforms, looms as a bigger potential culprit in occasioning higher unemployment than any ‘failure’ to adequately fine-tune macro or monetary policy.

For the most part, however, every galah in the petshop now persists in talking about nothing else other than how an (easier) twist in monetary policy, including a turn to the ‘unconventional’, is a pivotal part of a panacea for our perceived economic ills.

But monetary policy is limited in what it can achieve and should be just one increasingly minor part of the overall policy armoury. Key global central bankers, including Governor Lowe, have been trying to tell markets, governments and academia this very fact for some time – apparently to little avail.

Meanwhile, historically high levels of monetary accommodation have unleashed a plethora of ‘unintended consequences’, such as asset bubbles and growing wealth inequality, excessive risk-taking and attendant financial stability concerns. Easy liquidity sets ‘moral hazard’ traps that debilitate economic performance by allowing ‘zombie’ companies to persist, ultimately delaying necessary economic adjustment and lowering the economy’s growth path by inhibiting its productivity, flexibility and dynamism.

That is not to say there is no role for macro policy in a post-pandemic environment. But an assessment of that role should include a revisiting of the objectives of monetary policy and, more importantly, a recognition of its limitations.

We need to use all arms of economic policy

Central banks, including the RBA, are not perfect. The galahs in the pet shop – gratuitously - remind us of this all too often. But central banks need support from, and need to support, other arms of economic policy.

So, I do wish - just occasionally - that those aged petshop galahs would sometimes advance an advocacy of the agenda that they pushed in the 1980s. An agenda that ultimately set up Australia for a globally unprecedented three-decade long expansion and one that has the best chance of navigating the economy safely to and through the post-pandemic world.


Stephen Miller is an Investment Strategy Consultant with GSFM, a sponsor of Firstlinks. He has previously worked in The Treasury and in the offoce of the then Treasurer, Paul Keating, from 1983-88. The views expressed are his own and do not consider the circumstances of any investor.


  •   28 April 2021
  • 1
  •      
  •   

RELATED ARTICLES

A tale of the inflation genie, the Fed and the RBA

US rate rises would challenge multi-asset diversified portfolios

Yikes! Three critical factors acting on inflation and rates

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The investing rule that explains the next market crash

What if investment success depends less on picking the right assets and more on understanding the decisions of other investors? A principle borrowed from game theory offers a different perspective on markets.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.