Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 30

Give this risk the credit it deserves

I find it ironic that the fixed interest risk that most people fear is market risk. The fact that when yields go up, bond prices fall seems to scare many investors.

It shouldn’t.

The risk that bond investors should be most concerned about is credit risk. Only a credit failure can result in the permanent loss of capital and, potentially, a significant negative hit to a portfolio’s total return.

Market risk does not produce a permanent loss of capital. When yields rise there is an initial fall in the mark to market capital value of bonds, but higher yields result in increasing returns over time. I’ve written about this over the years (including in past articles in Cuffelinks), so I won’t become sidetracked by it again now.

Rather, this article discusses what credit risk and credit ratings are. In part 2, I will turn to the question of how credit risk can be managed so that it doesn’t wipe you out.[1] The good news is that, although credit risk is the more serious investment risk in my view, it can also be managed so that the risks are well worth taking.

What is credit risk?

The credit quality of a borrower is the likelihood that they will fail to honour their obligations to make timely payment of interest and principal. The world is an uncertain place and no bond issuer – be they a company or a government – has a 100% guarantee of never failing to pay.

There are a lot of factors that determine a bond issuer’s credit quality. There are financial factors, such as the amount of leverage an issuer has on its balance sheet. Issuers with low leverage have a stronger capacity to meet their debt obligations than highly leveraged issuers with low interest cover ratios.

The management strategy of the issuer is important. For example, strong risk management policies reduce credit risk, as does a clear and robust governance framework.

Finally, the industry in which a business operates is an influence on credit quality. Some industries are relatively stable, while others are volatile; some have a small number of well-established participants, while others are much more open to new start-ups taking market share from existing players.

What are credit ratings?

One of the most commonly used tools in credit risk analysis is credit ratings. Most people have heard of ratings, even if only when our politicians talk proudly of how the government still has a ‘triple A’ rating.

There are many different ratings scales that can be used, but the table below provides an overview of the ratings framework used by most agencies and credit analysts. In this framework, AAA ratings are assigned to borrowers with an ‘extremely strong’ capacity to pay. As the capacity diminishes the rating moves to AA, then A, then into the B’s.
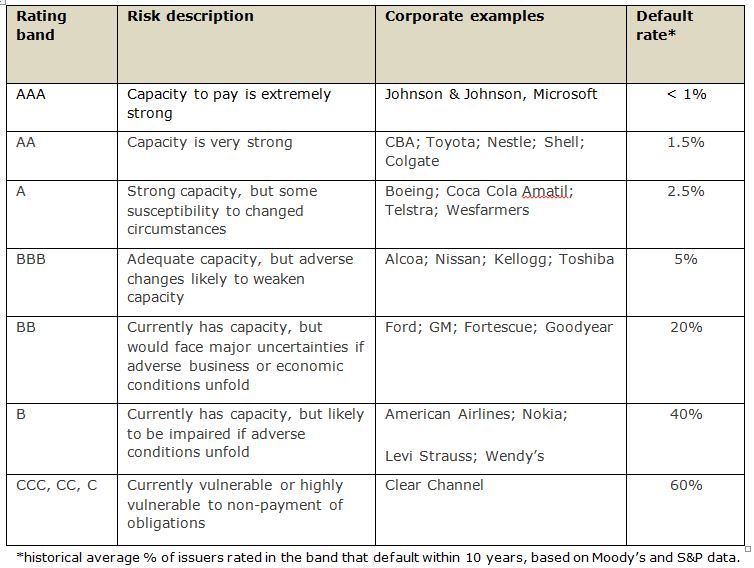
It’s important to understand that credit ratings are subjective opinions about an issuer’s credit quality. They are an analyst’s view, after considering the sort of factors mentioned above, of the issuer. Different analysts can have different views and there is no absolute right or wrong rating.

Also, ratings aren’t set in stone. As economic and business conditions unfold, some issuers improve and may receive a credit upgrade, while others deteriorate and may be downgraded. In recent years, Wesfarmers has moved from BBB to AA, while Nokia has been downgraded from BB to B.

As a guide to the likelihood of default, ratings are more of a relative guide than an absolute probability. For one thing, the average default rates shown in the table above mask a great degree of variance year to year. Years like 2008 and 2009 saw above average defaults across the spectrum of ratings, while in many years there are very few.

What are credit ratings not?

Finally, ratings are not an indication of the probability of losing capital if there is a default. Some debt investments have a high probability of default, but are secured against tangible and liquid assets that can be sold so that investors recover some of their capital. Others have a strong credit risk rating, but if a default occurs the recovery rate may be quite low.

It’s also important to appreciate one thing they are not. Ratings are not investment recommendations. They are an input, but don’t provide sufficient information to make a decision about whether to invest or not. This works both ways. AAA rated bonds are safe, but may be poor investments if they are paying a very low yield or if the recovery rate if there is a default is very low. On the other hand, while the credit risk of BB and B rated bonds (sometimes unhelpfully called ‘junk bonds’) is high, they are often excellent investments because of their high yields and reasonable recovery rates if there is a default.

The returns you make from investing in fixed interest are a combination of the interest you receive and capital losses from defaults. A high-yielding portfolio may provide an investor with as much as 3 or 4% above low risk portfolios like cash or term deposits. But if you experience a default or two you can easily lose more than 3 or 4%. This can wipe out the extra income you had hoped to receive.

Part 2 will address strategies for managing credit risk effectively.


Warren Bird was Co-Head of Global Fixed Interest and Credit at Colonial First State Global Asset Management until February 2013. His roles now include consulting, serving as an External Member of the GESB Board Investment Committee and writing on fixed interest, including for KangaNews.


[1] Recommended reading for those interested in delving deeper includes the fulsome information provided by Standard & Poor’s on their website, http://www.understandingratings.com/ or the overview found at the Australia Ratings’ website  http://australiaratings.com/corporateratingmethodology


  •   6 September 2013
  • 2
  •      
  •   
2 Comments
Diversify
September 06, 2013

Thanks Warren,

I find the fear people have on bond yields rising a little surprising, and agree that credit risk is significantly a greater danger.

If you have 20% of your portfolio in government bonds (assume zero credit risk which I accept may not be as safe an assumption as it was a few years ago) with a 5 year duration and yields rise 2%, the value of your bonds will drop 10%. This is an impact of 2% on your total portfolio, assuming the rest of the assets don't change in value. A rise in yields is probably indicative of growth coming, so equities could rally and offset any bond losses.

This would be a huge move in bond prices if this was to occur and would probably happen over 6 months. No doubt every investor long equities would hit the press to talk about the bloodbath in bonds and why punters should get on board the "great rotation" into equities.

Yet equities, typically making up 50% or more of a portfolio, frequently have this volatility and a 2% fall in the index can occur in a single day.

Warren Bird
September 08, 2013

Thanks for the comments, "Diversify"

I would not assume 'zero' credit risk on anything. All you can say is that the Australian Government is currently rated AAA, and attach to that the meaning that is given in the table - viz that they have the highest credit quality and an extremely strong to capacity to pay back debts. In an equation this is practically the same as putting in a zero for the credit risk, but psychologically it keeps the truth of what a credit risk rating really means to the forefront of your thinking. And it keeps you alert to watch for things like trends in the government's finances.

With government credit risk it really is important to understand that the rating is based on both the financial capacity to pay and the willingness to pay. When one of the ratings agencies downgraded the US to AA+ from AAA a couple of years back, it was not because that agency thought the US economy had reduced taxing capacity. It was because of the impasse in Congress that had put on the table a default by the US for technical reasons. Although few would doubt that every individual in the US Congress would want the government to honour its obligations, the political process was constraining those individuals to behave within the congress in a way that took the US to the brink of a default on an interest payment. The 'system' in the US is willing to consider a default, for political purposes. That's why the US isn't AAA in everyone's eyes.


Leave a Comment:

RELATED ARTICLES

Getting the most from your age pension

'FOMO' is driving residential property prices, not yields

Expect disappointment as values become stretched

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.