Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 361

Why are recessions usually good for share prices?

The Australian economy contracted by -0.3% in the March 2020 quarter and the June quarter will see a much larger fall. Australia is now in its first economic recession since Paul Keating’s ‘recession we had to have’ in 1990-1991. Perhaps surprisingly, economic recessions have generally been good for share prices in Australia, and the stock market rose on the news of the March 2020 number.

There is widespread acceptance that the government-ordered shutdowns of activities created instant recessions and unemployment for tens of millions of workers around the world. The debate is now about how deep and how long the recessions or depressions will be.

Recession versus depression

There has not been an economic ‘depression’ since the 1930s. It was caused by collapses in commodities prices and incomes, excessive levels of debt, rising protectionism and bursting of speculative bubbles. The Australian economy contracted by -19% and lasted two years, and the US economy contracted by -33% and lasted three years. In the 1890s depression, the Australian economy contracted by -13% and lasted four years, and US economy contracted by -8% and lasted two years.

By comparison, the 2008-2009 GFC was very mild. The US economy contracted by -4% and lasted six quarters, while Australia’s economy contracted by only -0.5% and lasted for just one quarter. Yet share markets fell by more than 50%. The next most recent ‘big recession’ was in 1990-1991 which was also mild by comparison with depressions.

It is notable that the current recession may have been triggered by an unforeseeable set of events (government shutdowns to contain a virus spread) but it is also accompanied by similar underlying pre-conditions as previous deep depressions, and as well as several mere ‘recessions’. The common culprits are familiar:

  • collapses in commodities prices and incomes
  • contractions in credit availability
  • excessive levels of debt
  • rising protectionism
  • potentially, the bursting of the QE-inspired asset price bubbles.

Governments have learned how to spend

This time is different. The GFC taught governments how to deficit spend and it taught central banks how to create artificial money to buy bonds from governments, companies, mortgage borrowers, car borrowers and even credit card borrowers. These ultra-loose monetary and fiscal policies are now embraced by left and right governments almost everywhere, even in Germany.

The problem is that, even after the hasty unleashing of trillions of dollars in government and central bank stimulus and support measures this time, economists are still talking about economic contractions in the order of 5-10%. This is several times worse than the GFC and the other mild contractions, and unemployment levels are heading for 20%.

It seems we are still facing contractions in overall economic activity and unemployment levels in the same league as the big depressions of the 1930s and 1890s. What the stimulus might do this time is shorten the contractions, but they are unlikely to lessen or shorten the unemployment pain.

All this talk of economic ‘recessions’ and ‘depressions’ can be depressing, but that is where the good news starts for investors.

The fear is that, since the economic contractions are only just starting now and may last for several quarters, then perhaps the February-March 2020 share market fall may not be the end of the overall share sell-off.

The good news is that while share market crashes and economic recessions and depressions are in most cases related, share prices generally fall before economic contractions start and then start rebounding while economies are still contracting.

Australian share prices in recessions and depressions

Share price falls generally precede economic recessions and share prices in Australia have actually risen during the vast majority of economic recessions. Here are the facts.

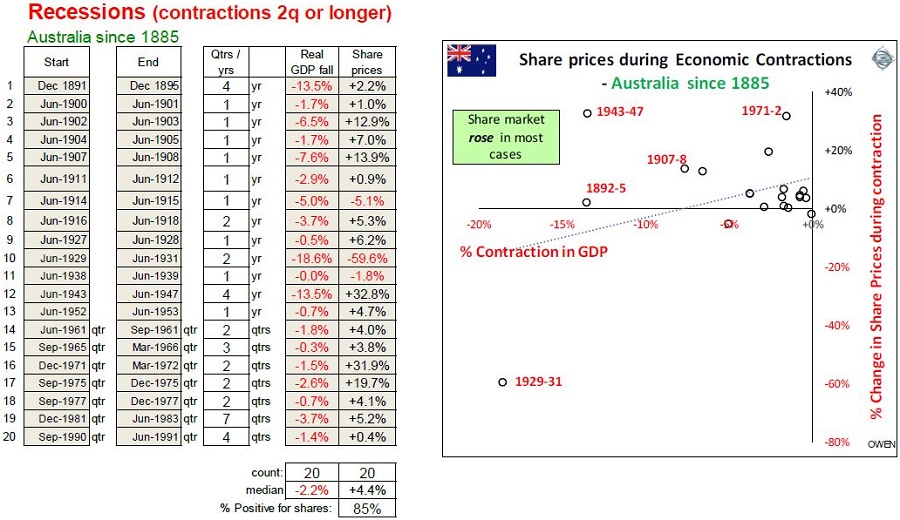
Australia has experienced 20 economic ‘recessions’ (including two ‘depressions’) since the 1880s. These are summarised below. The table sets out the dates and length of each economic contraction and what share prices did in during each period of economic contraction. The chart on the right shows the inverse (negative) relationship between economic growth and share prices.
In summary:

  • Share prices rose during 17 (85%) of the 20 economic recessions in Australia in the past 150 years.
  • Share prices rose during each of Australia’s last nine recessions.
  • The last time a recession was accompanied by falling share prices was the 1938-39 recession (share prices fell by only -1.8%).
  • Share prices rose in each of the recent well-known recent recessions – including: Keating’s 1990-91 ‘recession we had to have’, the long 1981-3 recession, the 1975 post-Whitlam dismissal recession, and the 1971-72 oil crisis recession.

The hard part for investors

Although shares prices often fell heavily at around the same time as the economic crises, in almost all cases, the share market fell before the economic contractions and then started to rebound during the contractions. As a result, most our big share market crashes were not actually during economic ‘recessions’ – not the 55% share crash in the GFC, the 50% crash in 1987, the 60% crash in 1973-4, the 39% mining crash in 1970-71, the 40% fall in 1981-82, nor most of the other big falls.

Conversely, some of the best years for Australian shares have been when the economy was contracting or still weak (albeit after big share falls earlier). For example: 1983, which was the best year ever for Australian shares (up +60%), during the 1981-1983 recession.

The hard part for investors is having the courage to buy shares when the economy is still contracting and the media headlines are full of doom and gloom about a cascade of corporate collapses, bankruptcies, and rising unemployment.

And, of course, deciding if this time really is different.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is for general information purposes only and does not consider the circumstances of any individual.


  •   10 June 2020
  • 10
  •      
  •   
10 Comments
Tom
June 11, 2020

Many commentators advise not to attempt to "time the market". Really? I've traded through all of the last 4 recessions, with considerable success. My guidelines for picking the bottom during/before a recession are: 1)wait for the 2nd selloff (it started today), 2) wait for the VIX to settle down and 3) wait until the market is down at least 50%. And if your not already cashed up, today might be your best opportunity for many years. Great article Ashley.

Martin
June 11, 2020

Hey Tom,

Interesting approach. How do you know if the market will drop > 50%? We're definitely due for a pullback, which may or may not have started today, but we don't know that the market will drop lower than March 23. (My personal belief is that it won't).

Which four recessions are you referring to?

Tom
June 13, 2020

Hi Martin, Q :How do I know if the market will drop 50%??
A : I don't know if it will, but if it does, that my signal.
Q: which recessions?
A : 75,81,91 & 07 (ok, granted 07 wasn't an official recession in Australia)
Interesting that you see Mar 23 as the bottom. Run a 10 year monthly XJO chart and see if it changes your opinion.

SMSF Trustee
June 11, 2020

Wow, Tom, you've hit the secret for success right there, haven't you? Still, now that your trading secret's out of the bag, everyone will do it and it won't work any more. Should have kept quiet with your amazing investment process that's so clearly better than any professional firm has ever come up with - you've blown it now, mate.

Chris
June 15, 2020

If it really WAS that easy, everyone would be doing it.

ashley owen
June 14, 2020

hi Tom,
Best of luck with it! If you have indeed traded through the last 4 recessions in Aust then that takes you back to pre-1975 so you are older and wiser than me. The VIX signal is the reverse - best buying is always when volatility is highest. A good guide is : low volatility reflects market over-optimism / complacency in booms (puts are under-priced and good value); but high volatility reflects over-pessimism / fear after sell-offs - which is best time to buy (puts are over-priced but calls are under-priced). But aside from the timing problems, the other main lesson is to have the cash and courage when it is time to buy (when the herd is selling out in despair at the bottom).
cheers
ashley

Fred
June 15, 2020

In 2008 it must be remembered that Australia in fact did not go into recession

Warren Bird
June 15, 2020

Fred, the article says that.

the point of all this to me is that the stock market is a place where risk is assessed and priced. In each of the situations where the market has fallen, there was at least a risk of a severe economic - and therefore company profit - downturn. The GFC was a case in point. The risk was very, very real as the financial system was on the brink of collapse. The other thing to 'remember' about 2008 is that the banks stopped wanting to deal with each other! And that a lot of ordinary folk were getting ready to withdraw all their savings from the banks. This meant that all businesses, listed or not, were at risk of not having the liquidity needed to pay suppliers or employees, because of the freezing of the credit markets.

Hence the 50% + fall in shares! A perfectly rational response.

Of course, this is also why the Government stepped in to guarantee the banks, and also why the RBA cut rates very aggressively and fiscal stimulus was introduced. Also rational responses to the risk. China's stimulus, in response to the same risks, assisted Australia enormously.

thus, we didn't go into recession, it's true, but boy was it a near thing.

Hop Duong
June 15, 2020

Ashley. Great stuff. Thank you.
Indeed, "this time is different", all 5 common culprits are not there at all. Prices? not collapsing; Credits? QE a'plenty; Debt?, interest rate is zero; Protectionism? we are in the time of globalization and just-in-time supply chain; Asset price bubble? not yet but maybe, watching unemployment right now. And yet, one "bottom" has already happened. All this makes "this time" so much more challenging and fun. Self serving advice "Time in the market" is truly thrashed. Kind Regards.

Peter S
May 04, 2022

Whats the difference between a recession and a depression? A recession is when you know someone out of work, a depression is when you are out of work yourself. Ive been self employed in the building industry since 1975 I have seen booms and busts but not a biggie since 1990, if we get a serious recession in the next 2 years I hope your investments are sound because you might be bailing out your kids/grandkids. The amount of household debt is massive. Stand by for mortgagee sales. I just hope the Govt and RBA dont bail the reckless banks out again as in 2008.


Leave a Comment:

RELATED ARTICLES

Recessions are usually good for sharemarkets

Most Australians live better than the Rockefellers

Are we in a recession?

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.