This is an edited transcript of an interview between Firstlinks' James Gruber and David Tait, CEO of the World Gold Council in Sydney.
James Gruber: Gold has been one of the best performing assets over the past few years – what’s the outlook from here, in your view?
David Tait: I'm often asked this question and the way I've chosen to answer it is rather than come over as overtly bullish, I say I cannot at the moment envisage a situation where it can go down, given the circumstances - except for one circumstance.
So let me briefly explain it to you. There are various aspects that are driving it higher. Firstly, the ‘the lady bird book of economics crowd’, interest rates and the dollar, that I think have largely been discounted over the last year or so. You've got the central banking crowd who have been buying gold hand over fist. Largely speaking, the developing central banks have been doing this. They've been doing it for very personal diversification reasons and portfolio management reasons. They've been doing it for exit the dollar reasons. They’ve been doing it because they're worried about geopolitics. There are 1,000 different reasons why they've been doing it, and I think that's going to continue.
There is a collection of three things in Asia that I think are going to continue to drive gold higher. Firstly, it's the money flowing from the older generation to younger generation in Japan at a time when fund managers are becoming younger. At the same time as they're inheriting a ton of money, they have great electronic penetration. And this comes at a time when Japan has experienced inflation for the very first time. So I think there's an opportunity there for the younger generation to buy gold.
At the beginning of this year China deregulated its insurance market. We were responsible for that, I'm very proud to say. It took nine years to get them to do it, but eventually they allowed 10 insurance companies to invest 1% of their assets in gold on the route to 15% and that market is US$5 trillion. So you can do the math. However, I forgot to mention the Japanese one is a $5 trillion market too.
And the last one is this growth of the ETF industry in India, which has come from nothing to more than 20 ETFs over a couple of years. It's a low AUM (assets under management) at the moment, only 70 tonnes. And we're doing a lot of work to try and redirect the younger generation to give them a gold alternative, which is an electronic core, functioning thing they can have on their phone.
So those three buckets combined with the most major one, which is the sovereign debt crisis throughout the world. I've been bleating on about it for years, but I do think back in April when there was a threat to the trust in the United States, this shifted the entire yield curve wholeheartedly up in one go, as opposed to steepening and lowering it like inflation does. If that yield curve [as a whole, both short and long end] stays higher, what happens is we won't be able to finance any debt, because the short end and the long end of the yield curve are both higher, and that's when the mathematics runs away. That is something none of us want to live through because you end up in a situation of every country around the table forgiving each other on that debt.
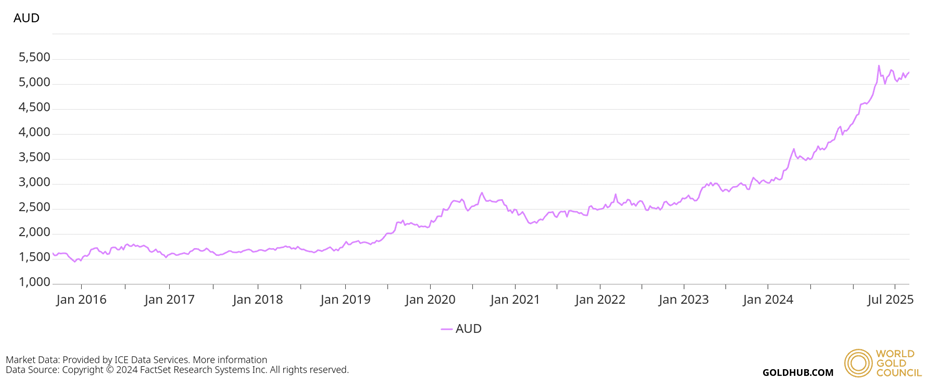
Gold prices (AUD/ounce)
JG: What's that risk to gold that you spoke of at the beginning?
DT: The main risk in terms of downside for gold is that if President Trump, having ladled more debt on the American existing debt, manages to pull off high non-inflationary growth, which is not really expected.
Remember, the tariffs allegedly are only going to raise prices in a one-off manner, not change the rate of inflation. If he manages, through that massive injection of sugar into that economy, he spurs growth to a high enough level that he can pay off his current account 6-9% deficit, and it looks real at the same time that he's cutting the deficit, that would be the moment that I would say would be the top of the gold market.
But probability adjusted I doubt he will succeed, but stranger things have happened, and frankly, I don't know a luckier person on this earth than that man.
JG: Central banks had been big buyers of gold in 2023-2024 driving demand for the yellow metal – has that continued this year?
DT: We're unsure at this moment whether we're going to get to 1,000 tonnes this year. That's not to say we won't, but it's not quite as clear as it was before. We're seeing different central banks showing up, and central banks who have historically been buying gold like mad, stepping back a little bit. So, in aggregate, we can't tell.
But our survey of the central banks suggests 47% of them are going to add gold this year, which is the highest number ever. But I can't extrapolate from that what the number [of tonnes] will be, but it should be very significant.
JG: A few months ago, there were lines of people outside shops selling gold here in Sydney – something I hadn’t seen before. Have you also seen growing interest from individual investors in gold?
DT: Definitely through Asia. Just to go to a China gold shop or an Indian gold shop.
During this portion of the rally, we haven't seen any typical recycling of [people selling] their gold at high prices. Now that that could simply be because they've seen such consistent price rises and they don't see this as the end.
An amusing story is about Costco in the States [US], where people are rocking up in their pickup trucks and buying gold over the counter.
JG: While gold has done well, gold miners have lagged. I suspect that it might be because gold miners burnt the trust of investors during the 2010-2012 boom when they overspent on acquisitions and incinerated capital. Do you think that’s right?
DT: Officially, I’m not supposed to be able to comment on mining stocks. But my personal opinion is that you are right on that.
I've got this sense that there has been less of this frenzy to go spend the money than we've seen in the past, which I think bodes well.
JG: Nowadays, investors often compare gold to bitcoin – what are the pros and cons of each?
DT: The best way to describe this is to start slightly backward.
I do think Bitcoin is a speculative investment. I do think at some point, though, it will become something that you hold as a store of value, if it can survive. And I've got no real personal opinion if it can survive. Maybe it can; maybe it can't.
But I do believe that if you choose to hold Bitcoin, you're compelled to hold gold as a diversifier within your portfolio.
The moment you add Bitcoin, you have the big problem, because it performs the same as, or positively correlates with, other risk assets, like equities. Your portfolio risk is multiplied. Hence it makes sense to hold gold against it as a diversifier, as gold is negatively correlated to other risk assets.
The vast majority of Bitcoin is held by a very small number of people. And I think gold, which is supported by one of the most liquid markets in the world, is its antithesis.
JG: The World Gold Council has been on a mission to modernise the gold market through blockchain technology and tokenisaton. Can you tell us more about this?
DT: Well, this came from my previous career because I closed down gold and commodities trading globally at Credit Suisse. And I did that because I had to. I wasn't able to get a return on the capital I allocated to the business, so I took the capital, put it somewhere else. I didn't understand why gold was so “capital expensive”. I just knew what I had to do – move the capital to a place where it returned better. I didn't understand why I wasn't getting the return.
Five years later, I'm in this role trying to figure that out this actual reason, and basically it boils down to trust. So, to solve the trust issue in gold, we created a database (Gold Bar Integrity) for responsibly sourced gold so you can check to see if your gold is what it says it is and has come from a responsible source.
The second thing was to try and standardise all the shapes and sizes of gold that are out there. So how do I standardise it? Essentially, we’re doing three things. We are digitalising the ecosystem in London, to the extent that by the end of this year, you will see gold transferred amongst banks as digital gold collateral for the very first time. And we've got all the banks working together on that, JP Morgan, HSBC, Goldman, etc. That's a huge infrastructure project.
The second thing that is running concurrently is the development of a mechanism by which you translate all these shapes and sizes into a standard digital format or SGU. It's really simple. You land on, let's say, one gram of 999 gold as the standard gold unit (SGU), and for instance you convert your kilo bar into 1,000 standard units. Simple. You convert it through an algorithm. You convert a 396.5 ounce London Good Delivery Bar using the same algorithm into these identical digital units. You convert all the gold in a database into those digital units. You do not lever the gold; critically it's one to one conversion and can be reversed and redeemed at any time. Importantly, this digital unit is not the trading item. Instead you create a pool of digital gold that you can back many other financial instruments into. So gold becomes trusted.
The reason for doing this was the reason I was actually employed, which was try and bring the institutional asset management world to the gold market because once you've created that digital pool, you have full transparency, instant delivery vs payment, clear price formation, the ability to surveille the markets as well as the ability to lower the capital burden, gold can attract a new generation of investors.
All the reasons why I closed down the Credit Suisse business are reduced, if not eliminated completely. So the asset managers of the future can allocate their money to gold as easily and as cheaply as they can to US dollar swaps or Treasuries as an example.
David Tait is CEO of the World Gold Council, a sponsor of Firstlinks. This article is for general informational and educational purposes only and does not amount to direct or indirect investment advice or assistance. You should consult with your professional advisers regarding any such product or service, take into account your individual financial needs and circumstances and carefully consider the risks associated with any investment decision.
For more articles and papers from World Gold Council, please click here.