Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 518

5 assets to protect you against a possible recession

As investors continue to grapple with higher rates, sticky inflation and market volatility, a defensively positioned portfolio could help to protect investors from macroeconomic and market risks.

Despite central banks around the world hiking rates at the most aggressive pace in recent times they are not even close to reaching their respective inflation target bands. As rates continue to rise so too does the risk of recession. Europe and New Zealand have already entered recessionary territory, and other countries may soon follow suit.

It’s not all doom and gloom, however. At some point during this year, we should see interest rates reaching their peak and inflation begin to subside. It’s going to take some time for inflation to fall back to the more stable 2-3% range. This will assist mortgage holders, renters, businesses, and the average Australian consumer with the cost of living.

Yet investors are contending with the unfortunate fact that historically, 75% of rate hike cycles in the US have resulted in a recession in the country since 1955.

US Federal Fund effective rate versus recession periods
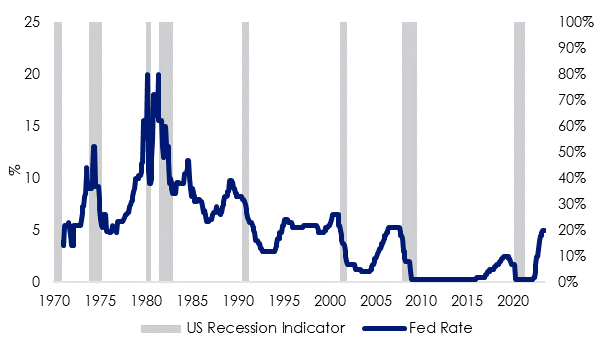
Source: Board of Governors of the Federal Reserve System (US)

Macroeconomic indicators suggest that the US is in the last stage of the economic cycle with a recession likely by the end of 2023. The US government bond yields between the 2 and 10 year are inverted, and manufacturing activity is contracting. Yield inversion has historically been a leading indicator for a recession in the next 6 to 18 months. ISM Manufacturing PMI below 50 highlights that activity is contracting.

US ISM Manufacturing Index
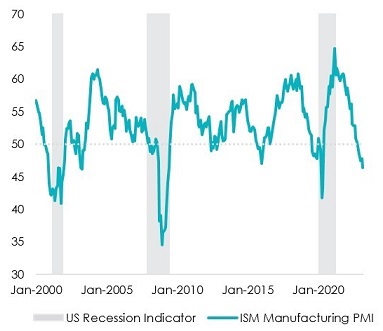
Source: ISM

10yr less 2yr US government bond yield
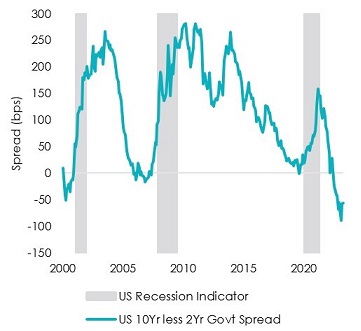
Source: Bloomberg

And while the US has a potentially higher chance of entering a recession this year than Australia, it will be important to watch the key local economic data prints such as CPI, GDP and unemployment numbers as they provide an overall picture of the state of the economy. 

As Portfolio Managers we are often asked what type of defensive assets should be held during this period of the economic cycle. While there is no infallible answer, the tried and tested assets listed below should be considered as part of a defensive allocation for an investment portfolio:

1. Gold: is one of the oldest defensive assets and physical gold has a low correlation to other asset classes such as equities, bonds or property.  Currently there are several factors converging which could see the gold price reach an all-time high. The gold price is currently testing the base of its recent up trend at around $1,950 USD per ounce, and with the continued recessionary pressures and geopolitical risks there is every chance that gold will push above $2,000 again towards $2,075.  We think there is more chance of upside than downside currently and there has also been strong central bank buying of late helping to stabilise the price.

2. Short term US treasuries: are often described as one of the major almost risk-free asset classes, and they are now yielding about 5.2%.  We know that the US is still the leading global economy despite the economic headwinds it faces, the US should maintain this commanding position for years to come.  Many finance calculations and risk models require a base calculation for the risk and US treasuries are commonly used to represent the low-risk option.  As rates continue to rise, a short-term US Treasuries exposure can provide a reasonable hedge to markets.

3. Floating rate bonds: this type of bond adjusts its coupon based on an underlying interest rate, if interest rates go up the coupon on the bond also increases.  This minimises the risk of losing capital as interest rates go up.  In a fixed rate bond if interest rates go up the value of the bond goes down and hence the investor could lose part of their investment.  There are multiple floating rate options in Australia that are yielding 4.5% to 5.5% currently.

4. Global infrastructure: assets like electricity, water or gas companies, rail lines, pipelines, airports, toll roads, telecommunication towers are the backbone of modern society.  In the current inflationary environment many infrastructure companies can adjust their pricing to keep pace with inflation.  There is vast spending taking place by governments within infrastructure projects especially with ageing utilities and changing population needs. A recent report by consultancy firm McKinsey estimated that the developed world needs to spend $70 trillion by 2035 to maintain its ageing infrastructure.  Infrastructure also has a low correlation to other asset classes so can act as a portfolio diversifier while at the same time paying a reasonable yield.

5. Quality companies: Adjusting investments through a downturn is difficult as picking the top and bottom of the market is nearly impossible.  The focus should be on having the right asset mix, and in that respect, a focus on quality companies has proven to be one of the better options.  These are companies that have a high return on equity, stable year on year earnings growth and low debt.  Companies with these traits tend to fall less in a downturn and bounce back faster in a recovery.

We’ve obviously focused on defensive assets but there is often a bias to short term investment horizons rather than longer term.  The current economic cycle will play out over the next few years, but anyone investing for retirement, or over the longer term needs to be aware that by the time their investments are realised, the cycle will have changed.

At the start of 2023 there was a fair amount of negative talk about the global sharemarket and many investors pulled money out fearing short-term market declines.  However, the NASDAQ and S&P500 are up 30% and 15% respectively year to date. Anyone sitting on cash would have missed out on this upswing.

There are many ways to implement the defensive strategies listed above, ETF’s however offer an easy way to diversify your investments in a single trade. 


Jamie Hannah is Deputy Head of Investments & Capital Markets at VanEck Investments Limited, a sponsor of Firstlinks. This is general information only and does not take into account any person’s financial objectives, situation or needs. Any views expressed are opinions of the author at the time of writing and is not a recommendation to act.

For more articles and papers from VanEck, click here.


  •   19 July 2023
  • 2
  •      
  •   
2 Comments
Steve Dodds
July 20, 2023

I'm curious about the recommendation of floating rate bonds as a defensive measure in a potential upcoming recession.

I can see their appeal in the current environment of rising rates, especially compared to the predictable but nasty returns from traditional bonds.

Presumably, however, if a recession does occur then interest rates will start to fall. This good news for those who manage to time the purchase of traditional bonds close to the peak as they should see capital gains.

But what happens to those whose defensive strategy includes floating rate bonds? Obviously the yield will fall as interest rates decline, but will there be capital losses as well?

In other words do floating rate bonds act inversely to fixed rate bonds, or more like cash?

Russel Chesler
July 21, 2023

Hi Steve. I'll jump in here as Jamie is on parental leave at present.

As the coupon paid on floating rate notes (FRNs) resets every three months based on three month BBSW, changes in interest rates have a negligible effect on the market value of FRNs. Changes in credit spreads do have an effect on market values. If we look at how FRNs performed in previous market crises, they only fell by small amounts in the GFC and more recently.

Credit spreads on Australian FRNs are currently above March 2020 levels. In our opinion credit spreads at these levels are already building in a slowdown in the Australian economy.

In terms of your last statement, “In other words do floating rate bonds act inversely to fixed rate bonds, or more like cash?”, FRNs do not work inversely to fixed rate bonds. In summary there can be market value losses on FRNs but based on history these have been limited, making FRNs a defensive asset.


Leave a Comment:

RELATED ARTICLES

A closer look at defensive assets for turbulent times

Is more trouble coming for the 60/40 portfolio?

Investors remain remarkably defensive during bull market

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.