Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 375

Have stock markets become a giant Ponzi scheme?

The past few months have exacerbated a trend we have been following with concern for some time now – the ever-increasing disconnect between financial markets and the real economy.

The COVID-19 outbreak has triggered a huge expansion of government balance sheets which in turn has enabled market darlings to reach dizzying valuation heights, to the point where financial markets might best be described as Ponzi borrowing.

This type of financial instability is not new, but when combined with the impact of a health crisis, it is particularly troubling.

Financial instability moves

Distinguished economist Hyman Minsky developed the financial instability hypothesis in the 1970s, which argued that capitalism moves between periods of financial stability to instability, with periods of stability leading to overconfidence by borrowers and lenders and encouraging excessive borrowing. This in turn increases volatility and ultimately triggers a crisis.

At the moment, Minsky’s hypothesis seems particularly relevant. The proportion of zombie companies (companies that are able to service, but not pay off, their debt) is growing, while productivity is declining, and economic growth is illusory. And if significant proportions of lending are based exclusively on an expectation of rising asset values, the result is Ponzi finance.

Worryingly, this trend shows no sign of having peaked. Indeed, the significant and long-term implications of COVID-19, and the decisive steps taken by governments and central banks around the world in response, have accelerated the pressure on stability.

At the same time, it has justified extraordinary monetary and fiscal stimulus actions that would usually be seen as overstepping mandates, and the scale of this overstepping will only increase as the system becomes increasingly unstable.

But having cried wolf too often, no-one now takes seriously the prospect of central bank balance sheet reduction or an end to monetary support.

Valuation-based investment

The disconnect between the financial system and the real economy has seen many investors lose faith in the concept of mean reversion and the strategy of valuation-based investment. Instead, the rewards seem to have flowed to those who seek ‘quality’ and ‘growth’, though perceptions of ‘quality’ seem to exhibit a high degree of subjectivity. In some ways, it can be described as chasing high multiples for market darlings and loss-making businesses that are supported by government largesse.

Exacerbating this trend is the recent growth in index investing which has constantly rewarded share price winners and punished losers without regard to fundamentals.

At Schroders, we continue to subscribe to the belief that mean reversion (at some point), and investment in real economy businesses which have not been inflated by easy money, will be rewarded, although there is no doubt that following this investment approach now has been tougher than ever.

Nonetheless, to us it seems inarguable that growth is an input to be used when valuing a business, not just an attribute to be sought at any price. On this basis, valuations of companies predicted to have attractive growth prospects have escalated far beyond realistic levels. As shown below, the top quartile Price/Earning (P/E) companies in the ASX200 have a P/E of 42 versus only 12 for the bottom quartile, a remarkable value dispersion for Australia's top companies. 
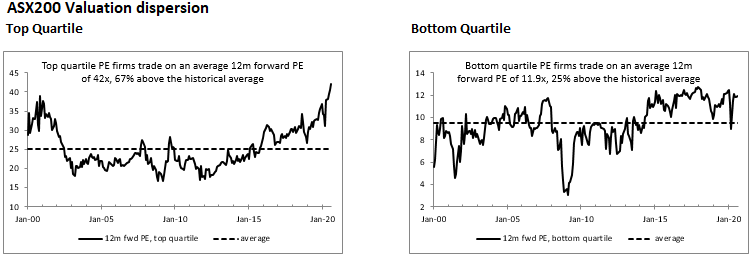
Perhaps even more worrying, they have maintained these valuations even as markets start to cool down.

Despite the fact that the global economy is presenting few growth prospects, we are seeing profit forecasts that would be unconvincing in a booming economy, let alone one that is being hit hard by a global pandemic.

Global financial casino

We continue to believe that fundamental value creation happens slowly, and that our role is to protect our investors’ hard-earned capital against the excesses of global financial markets – or perhaps what we could call the global financial casino. We remind investors that history has shown, time and again, that all bubbles burst and that growth cannot continue into perpetuity.

At the same time, we acknowledge that there will be no rapid exit from the global financial casino.

It seems more than likely that the current policies aimed at supporting the supremacy of the financial system over the real economy will continue, with a global financial casino running alongside a real economy that is increasingly fuelled by debt-funded government support.

For investors, the challenge is to identify which investment strategy is best suited to this environment.

On one hand, investors could simply abandon any realistic attempts to value companies and instead simply chase the hot streaks. But this type of herd behaviour is not ‘investment’. The share price alone is creating the appeal, not underlying value creation.

Another option is to rely on considered and realistic views of valuation, grounded in the low-growth and high-risk environment investors face. But to take this approach, investors must accept that fundamental value creation happens slowly and does not result in 200% share price gains in a quarter.

In a year when ‘social distancing’ has entered the lexicon, we continue to believe that staying away from the herd, by chasing growth with nothing to support it, is still the best path to take.


Martin Conlon is Head of Australian Equities at Schroders. This article contains general information only and does not take into account your personal objectives, financial situation or needs. These matters should be considered before acting on the information provided.


  •   16 September 2020
  • 6
  •      
  •   
6 Comments
George
September 16, 2020

But "the market can remain irrational longer than I can remain solvent".

ron
September 16, 2020

well said george- but just one sentence more. " corporate fund management can wait indefinitely for value investment strategies to pay off but i have a finite life span "

Mobcat
September 17, 2020

I can see Armageddon as a the market slowly decends into capitulation and the festering sore of debt burden all countries have entered into due to Covid.
The only answer is speculation for successful trading atm everyone needs mega returns or shut the door it’s game over for trading with small balls.

Ian
September 19, 2020

All this is predicated on the stock market being considered a reasonable facility to manage capital, but it has long since stopped being that. The level of a stock market indices today is irrelevant as an indicator of value or the state of the economy. with short selling , machine trading and rampant speculation, the price paid for most shares bears no real relationship with a company's value, but is the merely a snapshot of the last speculative trade on the day. Who knows whether that trade crystalised a gain from an uptick in price due to an unreliable announcement in the news.? We need to stop calling day traders investors, and recognise that the majority of stock market movement is generated by traders who aren't particularly concerned with the actual value of a company, only share price volitility, which they are happy to exacerbate.

glenn
September 20, 2020

....and corporate fund managers still generate fee income for themselves even if they're performing worse than the market, so should we buy fund managers????

mark
September 23, 2020

Is mean reversion a self fulfilling prophecy?


Leave a Comment:

RELATED ARTICLES

US rate rises would challenge multi-asset diversified portfolios

A tale of the inflation genie, the Fed and the RBA

It's not all about interest rates: give me a 1980s petshop galah!

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.