Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 557

The copper bull market may have years to run

Copper has been used by humans over for well over 10,000 years. More than ever, this ancient metal is a key driver behind humanity’s technological progress, from AI to net zero.

However, demand for this often-underappreciated metal is outstripping supply, driving up prices and potentially hampering the pace of development. Copper is at the heart of electricity, and high conductivity and light weight make it an indispensable material in electric wiring and grids, accounting for approximately 90% of global copper usage.

AI and renewable energy have physical requirements and need infrastructure such as data centers to house and process the vast amount of data and wind turbines and electric vehicle (EV) batteries to meet sustainability targets. Electricity and copper are critical inputs into both these stories and will drive incremental structural demand in the coming years.

Figure 1: Heading for a significant copper shortage (Figures do not yet include AI effects)
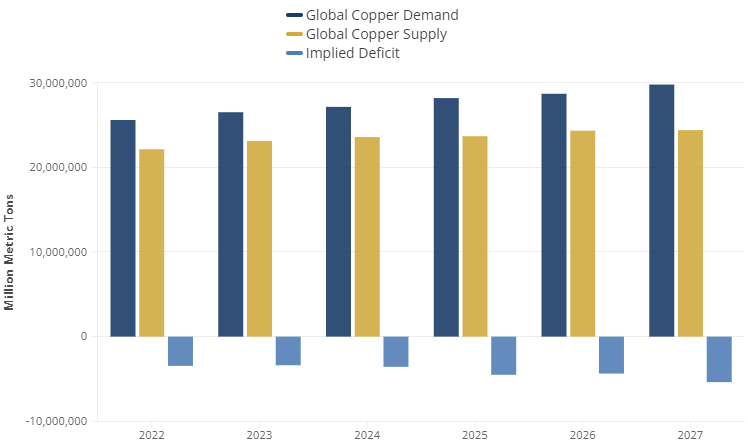
Source: BloombergNEF

Data centers are a crucial component of the rapid diffusion of AI technologies and the power markets will see demand rocket as more data centers are built to support AI. A traditional rack in a data center typically needs between 10-15kW of power. Compare this to the 40-60kW of power needed for AI-ready racks with energy intensive GPUs (Graphics Processing Units) – this represents between 4-6x more power and cooling usage.

For a sense of scale – in 2022, just in the US, data centers consumed 17GW of energy. It is estimated that by the end of the decade, data centers power needs will double to 35GW. When viewing this growth, keep in mind:

  1. data center buildout estimates from AI penetration are early stage and likely underestimates ultimate demand. Blackstone’s COO John Gray on a recent earnings call said he expects that tech companies will invest $1 trillion over the next five years in AI and this is mostly directed towards data centers.
  2. this incremental power demand will likely draw from clean energy technologies as much as traditional power sources. Even clean energy is a massive copper user.

What does this mean for copper demand?

While the physical market implications are still at an early stage for the global copper markets, the outlook provides strong secular tailwinds to demand. It is estimated that it takes close to 65,000 tonnes of copper per every GW of applied power. AI and data center usage for copper lies within two major areas:

  1. actual components into data center such as power distribution, grounding and interconnections and
  2. the generation of incremental electricity to power and cool the data center.

The actual copper usage will not be static as fibre is a more efficient form of connections, but more processing intensity will demand more copper usage.

If we assume that between 3-5GW of data center applied power are built every year in the US (and the AI race is hardly US only) – the potential incremental copper demand just from the US data center buildout could range between 0.5-1.5% of global copper demand. Although this might seem insignificant, even a 1% shortage could plunge the market into a significant deficit.

Renewable energies fuel copper use

Looking beyond copper applications in data centers, the need for more power will also drive incremental generation from clean energy, potentially in the form of distributed grids (think solar panels and wind turbines). Consider that it takes between 4-5 tonnes of copper to build an onshore wind turbine or solar panel to generate 1-3MW of power.

Add to that the increased roll-out of electric vehicle (EVs) batteries and the push for sustainability has an unintended consequence of eating up a finite resource. A traditional internal combustion engine vehicle uses a fraction of the copper contained in an EV – 48 pounds for a combustion engine vs 183 pounds for an electric vehicle battery. A hybrid car contains 88 pounds of copper.

As the world endeavours to achieve net-zero emissions over the next three decades, copper demand is anticipated to grow five to six-fold. However, this surge might be challenging to meet given current supply constraints.

Constraints in copper mining

Copper supply has been further strained by operational and political instability in regions where it is mined, including Congo, Kazakhstan, Mongolia, and Latin America. Over the past year, an estimated 3-5% of global supply has been disrupted due to these factors.

Moreover, copper's supply response is notoriously slow. A typical copper mine takes about 10-15 years to explore, develop and bring online. There are no quick fixes like shale wells in the oil industry, which can be operational in mere days.

As a result of these factors, the copper market is barrelling towards a significant deficit and a price surge over the next few decades that investors should not discount when looking at the potential for AI and renewable energy.


Albert Chu is a portfolio manager at Man GLG, a fund manager partner of GSFM, a Firstlinks sponsor. The information included in this article is provided for informational purposes only.

For more articles and papers from GSFM and partners, click here.


  •   24 April 2024
  • 6
  •      
  •   
6 Comments
John Peters
April 25, 2024

It's the ultimate negative feedback loop - more demand for AI = greater copper supply shortage = higher copper price = limited inputs for further AI growth.

Given how long it takes to get copper supply to market, it's hard to see how this ends well. I note that the Freeport McMoran Ceo came out the other day and said he'd never been more enthusiastic about the copper outlook.

John Peters
April 26, 2024

Is this the old CBA Chief Economist that uses my name (ha ha).

As a Managing Director of a second board (UK) mining company, Strategic Minerals plc, we have been across this future demand and supply imbalance and have been developing mining opportunites that have this and critical minerals Tin and Tungsten.

It is interesting to note that the South Australian government has stated that it has a target to be to be third largest Copper supplier in the world. The Gawler Craton provides a rich structure from which to achieve such a goal.No wonder BHP (Olympic Dam) took out Oz Minerals (Prominent Hill and Carapetina) who had the only other sizeable operating copper mines in South Australai.

Tim
April 26, 2024

BHP looking to acquire Anglo American now too.

Paul
April 26, 2024

There are other metals that conduct electricity.

Stan
April 26, 2024

ALL metals conduct electricty,some better than others.The best are gold,silver copper and aluminium which is why the last two are used for all large scale applications.

Brian
April 26, 2024

None that have the widespread attractions of copper.
In its own class.
Unless you know something that BHP has overlooked.....


Leave a Comment:

RELATED ARTICLES

Will AI destroy investor capital?

The surprising beneficiaries of the AI boom

Datacenters are the new shale oil

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.