Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 313

Insane prices as private equity quits market

Recently, sitting at lunch among reputable, intelligent and enormously-successful fund managers, there was one thing we all agreed on. Prices for many listed and unlisted companies have reached insane levels.

I listed the worst offenders:

  • Wisetech, on the same market cap as Qantas of $8.5 billion but earning 2% of Qantas’s revenue.
  • At 60 times earnings, Appen must have the smartest AI shareholders in the world because Appen’s US-based and private equity-owned competitor, Lionbridge, wants to list here too.
  • The printed circuit board (PCB) software designer, Altium, is on a PE of 57 times, putting it on the same market cap as JB Hi-Fi, Metcash or Air New Zealand. But while the latter three each earn revenue of between $4 billion and $14 billion, Altium earns $177 million.
  • After 12 years of operations, Xero has finally achieved cashflow break-even. In 2021 it is expected to earn a little over $20 million in profit too. It just has to be worth over $8.5 billion or 370 times forecast profits!

This will end badly, but when?

At that table, a lot of fundie experience with stock market corrections agreed that this ends badly. What we could not agree on, however, was how it ends, nor when.

But perhaps that latter question has an answer and in this article I’ll highlight a possible stumbling block for a continuation of heady valuations of profitless tech companies.

The calendar year 2019 is shaping up to be the busiest for new tech stock listings since 2000. I was working at Merrill Lynch in 1999 when analysts were concocting new ratios to justify billion dollar market valuations for companies (nay ‘projects’) with no revenue. Analysts told investors that the ability of these companies to transform e-commerce, for example, meant that almost ‘any price’ should be paid to acquire a piece of the action.

So far this year, 25 tech companies have IPO’d in the US raising US$19 billion. At the time of writing, the average gain on listing has been 34% according to Dealogic. The picture was a little different in 1999, when the first day gain for IPOs on the Nasdaq was closer to 90%. Perhaps conditions aren’t as crazy now.

But does that really matter? That would be like suggesting one patient in the asylum is slightly less insane than another. Neither of them should fly a passenger jet nor should they be put near an equity portfolio.

Most new listings are questionable quality

Of the 25 companies that have IPO’d this year, less than half can be classed as ‘major tech companies’. They are: Beyond Meat, which is up over 500% since listing, Zoom Video (+170%), PagerDuty (+120%), CrowdStrike (+110%), Pinterest (+45%), Chewy (+47%), Fiverr (+30%), Slack (+27%), Fastly (+10%) and Uber and Lyft (both negative).

Share price performance, however, doesn’t really matter. It cannot tell you what will happen next.

Aneet Chachra, is a Portfolio Manager at Janus Henderson Group. Chachra studied the history of 220 US technology IPOs from January 1, 2010 to March 31, 2018, focussing only on those with a 12-month trading history. Chachra observed:

“Statistically, if you can get into a tech IPO at the deal price, you are going to do well.”

Presumably he was referring to the final funding round deal price before IPO. Pitchbook’s 2018 study reaches a similar conclusion. Pre-IPO investors do better from the IPO ‘step-up’ than investors who buy on the first day of public trading.

This makes sense. PE investors will want to price their IPO so that all existing shareholders make money at the time of listing, and they will time the IPO to give their investors the best chance of achieving that outcome. In a 10-year bull market fueled by historically low rates that caused investors to spurn cash and migrate to anything and everything that might go up, including private equity, the study’s findings should not be surprising.

Two glaring issues for investors

The first is that if 10 years of declining interest rates has encouraged or forced high-net-worth and ultra-high-net worth investors to buy private equity and invest pre-IPO, who will be left to buy these stocks after they list?

Chachra’s and Pitchbook’s findings may reflect the fact that the exponential growth in the number of private equity firms globally since 2009 has attracted most of the money of high-net-worth investors leaving only ‘Mom & Pop’ investors to pick up the scraps.

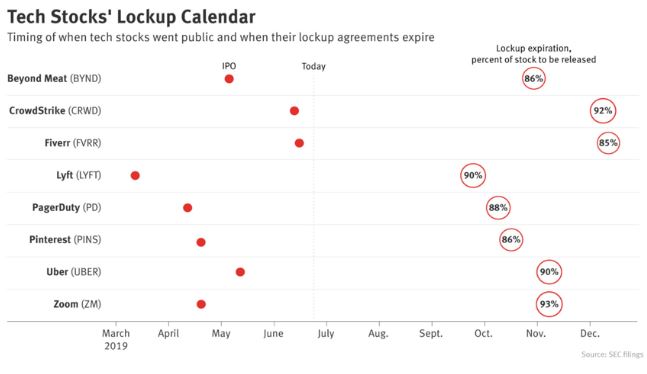
Second, of the largest tech stocks that have listed this year, only 10% to 15% of their scrip has been available to trade. A 180-day lock up (escrow) period for founders and backers means 85-90% of scrip is still waiting to be sold.

This overhang could easily become selling pressure if PE investors who have been locked in for a decade, such as with Uber, decide they want out. It’s the marginal seller that determines the price for everyone. If the Uber investors who bought in 2010 at much lower prices decide they want to sell, their trading will impact the market capitalisation for everyone.

And this transmission mechanism is perhaps another explanation for the poor post-IPO performance of the average tech float.

Beyond Meat will see an additional 86% of its scrip released for possible sale in November 2019. CrowdStrike will see 92% of its scrip released in December, Fiverr (85% in December), Lyft (90% September), PagerDuty (88% October), Pinterest (86% October), Uber (90% November) and Zoom (93% November). And a record number of IPOs this year will ensure the pressure doesn’t let up until next year.
Tech IPO investors in Australia won’t be immune from the impact of the 2019 US private equity exit.


Roger Montgomery is Chairman and Chief Investment Officer at Montgomery Investment Management. This article is for general information only and does not consider the circumstances of any individual.


  •   3 July 2019
  • 6
  •      
  •   
6 Comments
Chris
July 04, 2019

Bring it on, I say. Nothing quite like a good market crash to clear the detritus out. I'm waiting with cash and lines of credit to go and press the buy order button, but not right now. Things are too expensive in the USA and the time isn't right.

SMSF Trustee
July 09, 2019

Chris, I don't think Roger is talking about a 'market crash', but simply an issue with a sub-set of the market.

He can't be talking about 'insane prices' for the whole market. The All Ordinaries PE is just under 17 with the index at 6,730. 17 is a little on the high side, but can't be thought of as 'insane'.

The long run growth of earnings in Australia has been 4.7%. If you grow the current level of earnings by that into the future, then the implied discount rate to get us to 6,730 is about 11%. That seems to be a pretty hefty risk premium over the ten year bond rate of 1.25% that's factored in.

Interested in Roger's thoughts, but the word 'insane' is stock specific, not applicable to the whole market. (Haven't done the same maths for the US market though.)

Carlos
July 04, 2019

calling those stocks "worst offenders" is unfair wording as the companies themselves have done nothing wrong. It's the market's fault their prices are so high. The companies themselves are being very well run.

Roger Montgomery
July 08, 2019

Thanks Carlos, yes, the implication is that investors have caused the 'offence'. And Chris, I know that if there are too many sitting on the sidelines waiting, it probably won't happen.

Dudley
July 08, 2019

"investors have caused the ‘offence’":

Not a runaway positive feedback where reducing interest rates pushes money away from cash to speculative capital gains; amplified by central banks pushing cash into markets in a partially successful attempt to increase labour participation but also resulting in increased labour replacing / displacing capital investment?

Wayne
July 08, 2019

Roger, what are you saying won't appen? (pun intended)

Are you suggesting that these insane valuations have more legs in them yet?.... I guess this is your whole point though - that people with cash are chasing returns, and assuming this continues (contrary to Chris's comment), at some point someone will be left holding the can.


Leave a Comment:

RELATED ARTICLES

Collateral damage follows the end of profitless prosperity

Why August company reporting season was poor

How we have invested during COVID-19

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.