Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 87

I will survive! Investing amid structural change

Australia’s economy has fared better than most post-GFC, buoyed primarily by the tail end of the resource boom, solid population growth and a strong financial sector. That said, with the resource boom maturing and the workforce ageing, the Australian economy has slowed – and is likely to grow at a slower pace in coming years than we’ve grown accustomed to. Investors must deal with the challenges of ‘picking winners’ in the new environment.
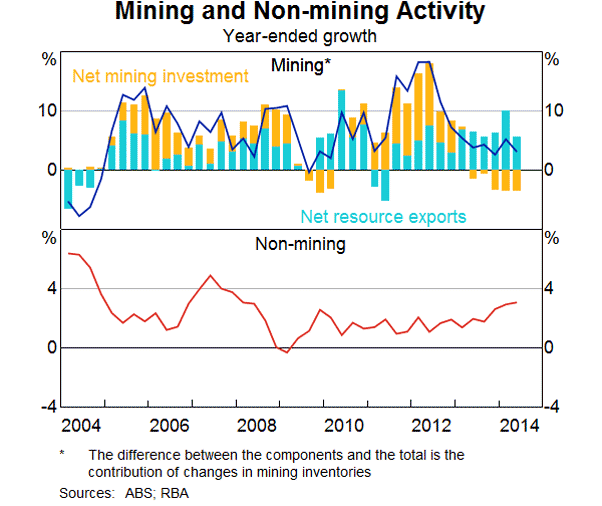
At first glance these changes could be taken as a negative for investors in the Australian share market. But the reality is that our economy has long had to cope with structural change, which has not stopped quality Australian companies from generating profits and wealth for investors over the long term.

Structural change and the economy

Most investors are familiar with Australia’s recent commodity export price boom, and the associated strong lift in mining investment. During this period, national income and employment grew at a healthy pace.

Of course, a by-product has been relatively high interest rates by global standards and a strongly rising Australian dollar, which have been harmful for many Australian sectors not exposed to the resource sector. In effect, interest rates and the $A worked to ‘squeeze’ other sectors of the economy to make room for a rapidly expanding resource sector without threatening a break-out in wages and prices.

Population ageing has also contributed to a fall in labour force participation, which has meant somewhat slower growth in the work force relative to the overall population.
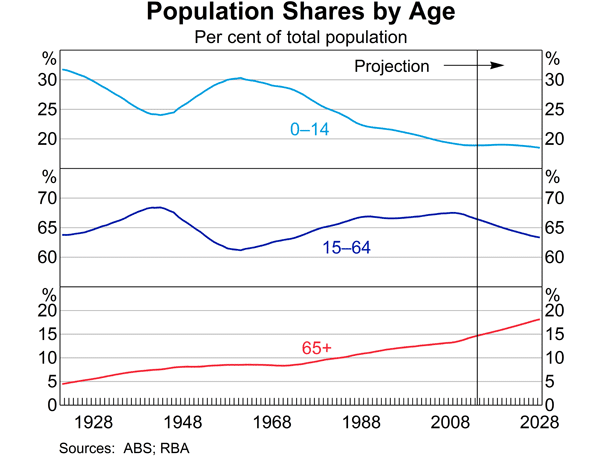
With commodity prices now in retreat, and a falling share of the population of working age, the Australian economy faces slower growth in national income. Indeed, Senior Treasury official Dr David Gruen recently noted gross national income per person grew at an annual rate of 2.3% over the past 13 years but may rise annually by only 0.9% over the next decade.

Reserve Bank Deputy Governor Philip Lowe extrapolates that data to suggest: “we will need to adjust to some combination of slower growth in real wages, slower growth in profits, smaller gains in asset prices and slower growth in government revenues and services.”

The economy’s next phase

The good news, however, is that slower income growth does not necessarily mean falling share prices or lower dividends. For starters, although growth in national income ‘per person’ may be slowing, overall growth in national income should remain well supported by continued solid population growth.

And growth in domestic production should be faster still, due to strong gains in resource export volumes – particularly iron ore and LNG – following the heavy investment in new capacity in recent years. Low interest rates and the weaker $A are also helping the economy unleash activity in sectors once held back by the mining boom, such as housing and non-mining trade exposed sectors like tourism and international education.

Of course, as the baby boomer generation moves into retirement, growth patterns will change. Far-sighted management should identify and respond to these changes – witness the massive investment by our major banks into wealth management businesses, to replace lost mortgage income with the fees earned by managing retirement funds.

More generally, the predicted changes in the economy should be gradual enough for many existing firms to respond in a timely manner to the new challenges and opportunities as they arise. And those that don’t are likely to be usurped by nimble new starters which, if successful, are also likely to stake their place among Australian listed companies.

Apart from changing or amending corporate strategy (which the best companies already do), astute management can also modify their financial management to maintain or boost dividends. Capital management programs can help support share prices and grow dividends, at least in the near to medium term.

In short, thanks to earlier pro-competitive reforms such as deregulation of labour and product markets and the floating of the $A, the Australian economy has demonstrated remarkable resilience and flexibility. It avoided recession over the past 20 years despite the dotcom crash, Asian financial crisis, and the most recent US sub-prime induced global financial crisis.

Picking winners will not be easy

We should not underestimate the ability of corporate Australia to rise to the next set of challenges they face. That said, picking tomorrow’s corporate winners and losers via purchasing individual shares will not be easy. In this regard, investors should note an often little-appreciated benefit of index-based investing such as through exchange traded funds – survivorship bias. The indexing process automatically cuts exposure to poorly-performing companies over time, while re-weighting to new and more strongly-performing competitors – something you don’t get when buying individual stocks.

The structural changes will also give rise to major macro themes relating to technology, climate change, the emerging Asian middle-class, demographics, an ageing population, and energy and natural resource usage. Exchange traded funds can not only target the overall macro themes through diversified portfolios, but also specific sectors within an index. It is a faster-changing, more complex and harder to anticipate investment world. There are many reasons for optimism about the future of Australian companies but some of the star performers of today will struggle to adapt to the inevitable changes.


David Bassanese is the Chief Economist at BetaShares Capital, a leading manager of exchange traded funds. This article is for general information purposes and does not constitute personal financial advice.


  •   7 November 2014
  • 4
  •      
  •   
4 Comments
Tortoise
November 07, 2014

But what effect does the lag between the market rising and share purchases then being made, have on performance?
Likewise with a falling market.

If, say, you buy or sell stocks every 3 months to realign the index, aren't you detracting from performance since you are always behind the eight ball?

Would be interesting to know whether these continuous changes average out or not

David Bassanese
November 10, 2014

The issue you refer to is one the key criticisms of traditional market-cap weighted indices where index weight is determined by market price. However not all indices are created equal.

For example the index we aim to track with our "QOZ" product (see http://www.betashares.com.au/products/name/ftse-rafi-australia-200-etf/#each-overview), is a "fundamentally weighted" index. This Index selects and weights its constituents based on factors related to the fundamental size of a company, reflecting the company's economic footprint rather than its market capitalisation. Use of these factors seeks to overcome the limitations of traditional indices based on market capitalisation by using measures which do not depend on the fluctuations of market prices, while still maintaining the benefits of passive investment.

Breaking this link between index weight and market price aims to produce superior long term performance compared to indices weighted using market capitalisation.

Warren Bird
November 11, 2014

If you have an index fund that holds index weights to all stocks at the start, and some stocks rise faster than others, you don't have to "rebalance". Your portfolio will now hold a higher weight of the better performers, but it will be the new index weight.

So if an index portfolio is being managed properly it shouldn't have any sort of lagged affect. Perhaps that's why index funds usually make index returns, at least before fees. For example, look at the consistency of the CFS indexed Australian share fund over each of the time periods 1, 3, 5 and 10 years - it's net return is around 0.35% below index per annum over all of them. http://www.colonialfirststate.com.au/Prospects/FS1554.pdf?3

This isn't because buy and sell lags even out over time. It's because there is no lag. Managing an index fund properly requires some skills - eg handling cash flows and the timing of buying new stocks that enter the index - but index managers at least don't have to negotiate 8 balls all the time.

Jerome Lander
November 13, 2014

An index fund will usually reliably underperform the index that it tracks (due to costs). Interestingly, indexing was initially designed for benchmarking purposes, and it works well for this purposes (over longer periods of time). Indexing was not designed to be used as an optimal investment strategy.

Indexing reflects the average performance of investors (dollar weighted) in a market. It is questionable whether the average investor will or should be well-rewarded by markets in the long term, particularly when that investor does not perform due diligence on their investments but trusts in markets to deliver them favourable outcomes.

Market cap weighted indices by their very nature overweight past success stories and underweight emerging success stories. They underweight the areas of future potential opportunity, such as some of those mentioned in the article.

Good active Australian equity managers have fairly consistently beaten the index in Australia - for various sustainable reasons - and many of them are also likely to outperform in downmarkets when outperformance is more important to meet investor needs, preferences and long term returns. In addition some Australian equity managers offer their services at low cost relative to their value add given the large amount of competition in Australia and institutional biases for the status quo. Hence the current love for indexing may be more reflective of ideology and politics than a rational assessment of what can be achieved by informed investors.

Indexing is becoming increasingly popular due to various factors but is a suboptimal way to invest over the long term. As a style of investing, indexing is a poor quality momentum strategy (as it doesn't risk manage its positions sizes or its losers very well). Indexing tends to do well in upmarkets and may make sense to use for those making short-term asset allocation plays. As a long term investment approach it has significant weaknesses.

Sometimes cheap and cheerful is just that.


Leave a Comment:

RELATED ARTICLES

The red metal's long game

The challenges of building a lazy portfolio

Global ETFs: insights into a multi-trillion-dollar industry

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.